


EN
Did Lower EPS Estimates Just Shift ONEOK (OKE) Stock Ahead Of Earnings?
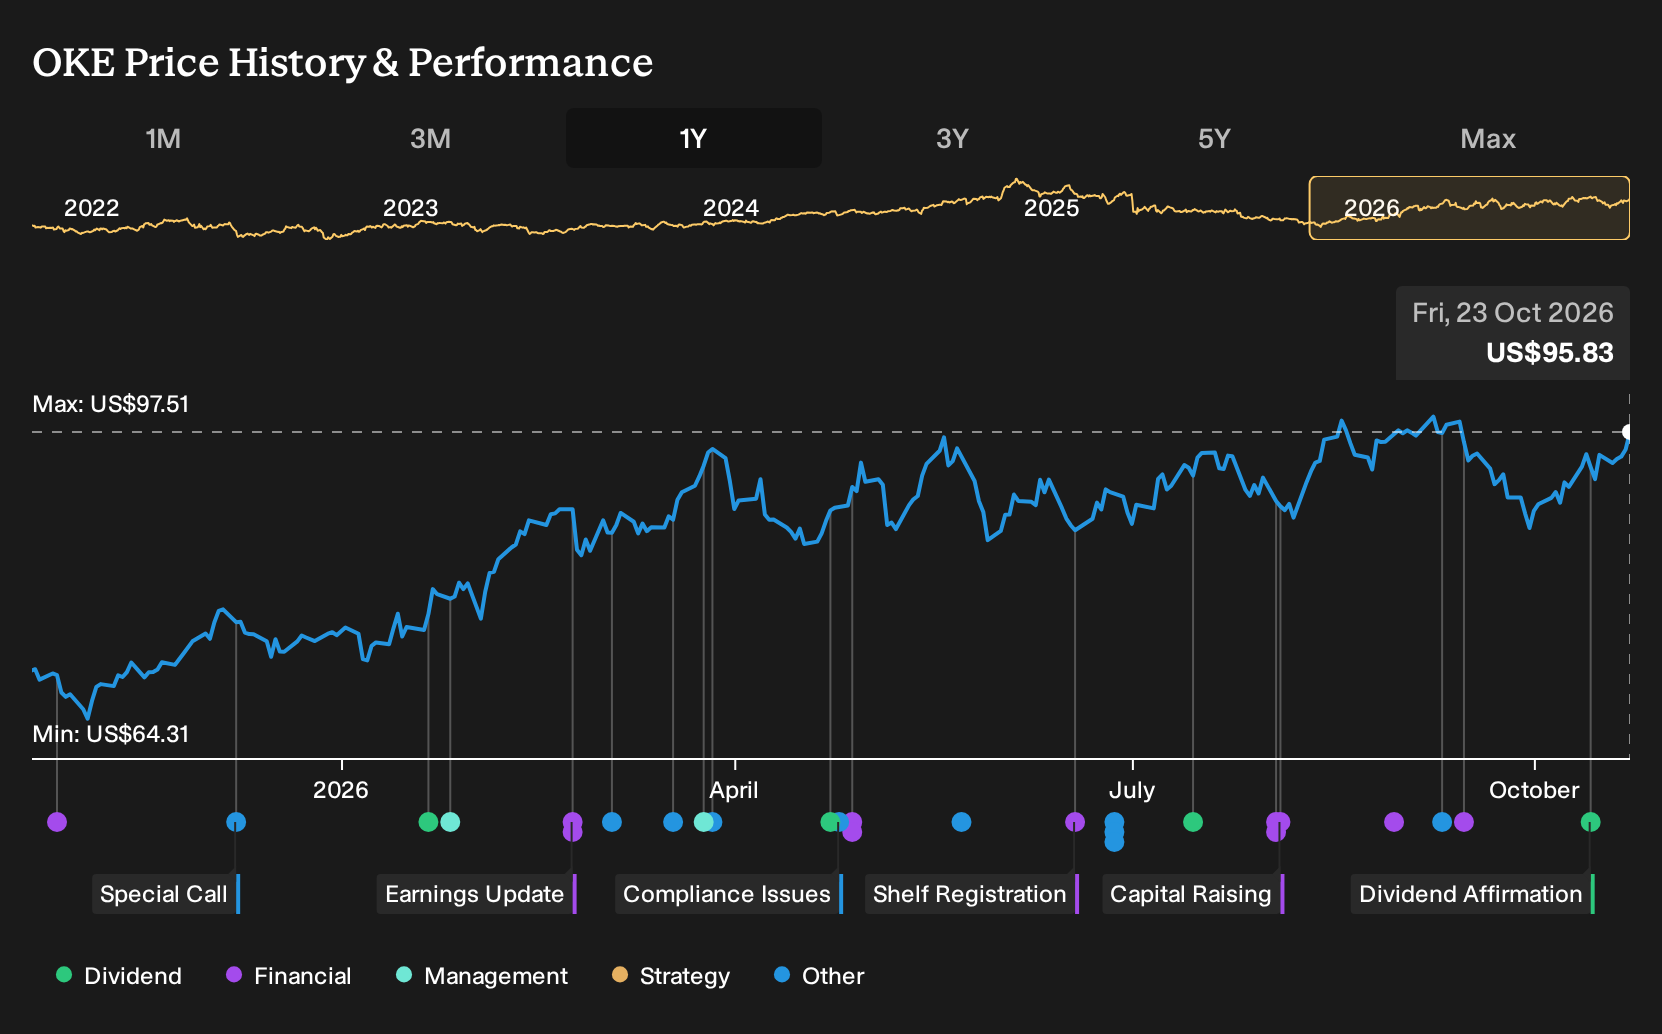
- ONEOK’s board recently affirmed a quarterly dividend of $1.07 per share, unchanged from the prior period, which implies an annualized payout of $4.28 per share for investors of record as of November 2, 2026.
- The steady dividend comes as analysts project $1.46 in quarterly EPS with revenue of $11.77 billion, highlighting a mix of earnings pressure and strong top line expectations.
- We will now examine how ONEOK’s unchanged dividend, together with softer EPS estimates, could influence the company’s broader investment narrative.
Compare ONEOK’s steady payout and shifting earnings expectations with a curated list of income ideas. Scan 5 dividend fortresses to view strategies built around resilient cash flows and higher yields.
ONEOK Investment Narrative Recap
To own ONEOK, you need to believe its midstream footprint can keep generating steady cash flows from natural gas, NGLs, and refined products while it executes on Permian growth and export projects. The unchanged US$1.07 dividend signals management’s preference for stability over short term flexibility. On its own, that decision does not materially shift the near term operating story.
The more immediate swing factors remain earnings sensitivity to Permian pipeline spreads and NGL product mix. Softer EPS expectations underline that risk. If ethane heavy volumes or weaker pipeline differentials persist, margin pressure could outweigh volume growth, especially with leverage and cash flow coverage already key watchpoints for income focused holders.
The dividend affirmation is the announcement that matters most here. A US$4.28 annualized payout, held flat into an earnings print where consensus EPS is drifting lower, ties the ONEOK income thesis tightly to execution on projects like Brazos Midland integration and Permian expansions that support future fee based cash flows.
For you as a shareholder, that means the quarterly check is steady while operational variables still move. The short term catalyst is whether October 27 results and commentary show enough progress on utilization, export build out, and cost control to keep that dividend well supported. Any disappointment on cash generation would sharpen attention on balance sheet risk and payout sustainability.
ONEOK's narrative projects US$40.4b revenue and US$4.4b earnings by 2029. This assumes revenue stays broadly flat over the next 3 years and implies an earnings increase of about US$700m from current earnings of US$3.7b.
Uncover why ONEOK's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on ONEOK leans hard into Brazos and export upside. Before this dividend decision, the most optimistic analysts were penciling in revenue of about US$55.2b and earnings near US$4.9b by 2029, far above the consensus of US$40.4b in revenue and US$4.4b in earnings. Opinions clearly span a wide range. Consider several perspectives before deciding how this unchanged payout fits your own thesis.
Explore 4 other ONEOK fair value estimates, including one that suggests as much as 116% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ONEOK research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ONEOK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ONEOK's overall financial health at a glance.
Looking For More Investment Ideas Beyond ONEOK?
If the ONEOK story has sharpened how you think about income, risk, and long term potential, it can help to weigh those same trade offs across a wider watchlist using structured stock filters.
- For investors who want potential upside with disciplined underwriting on quality, consider a curated set of companies screened for valuation support and financial strength through 29 high quality undervalued stocks.
- If capital preservation and balance sheet strength sit at the top of your checklist, build out a shortlist using a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without relying on aggressive refinancing.
- For readers who care most about consistent income, round out your watchlist with yield focused ideas sourced from a 5 dividend fortresses that screens for higher payouts supported by underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com