


EN
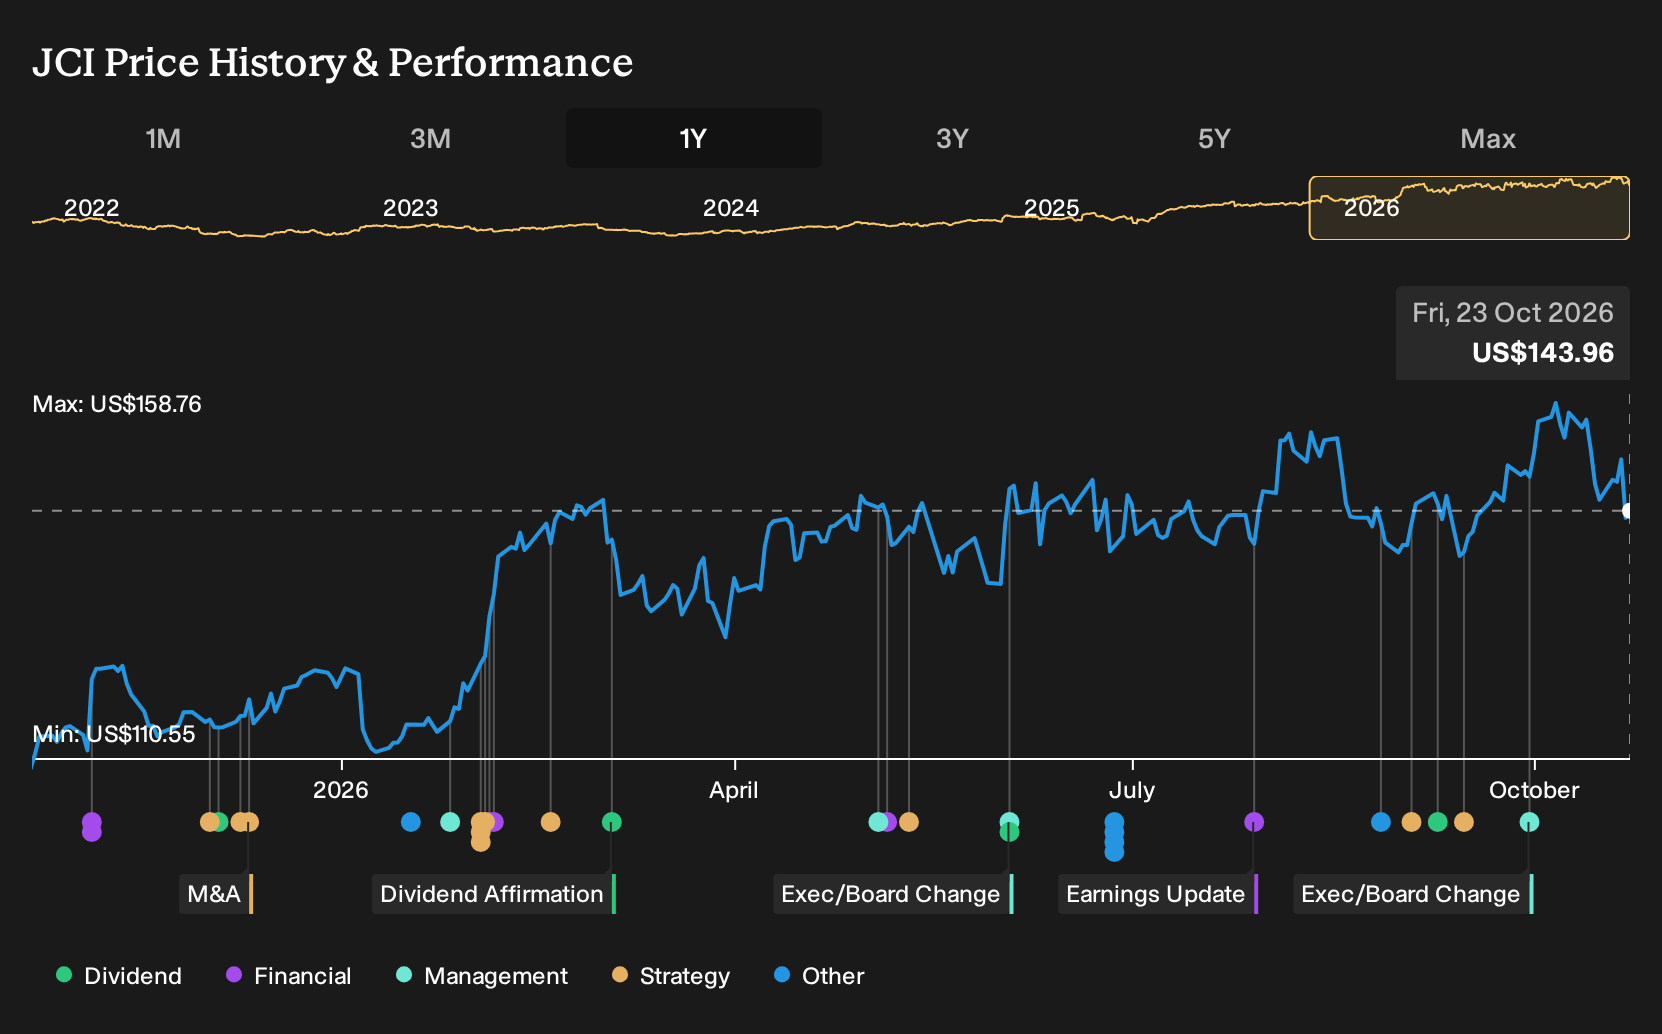
Is Record AI Backlog Altering The Investment Case For Johnson Controls International Stock?
- Johnson Controls International is scheduled to report its fiscal fourth quarter 2026 results on October 27, with analysts expecting profit per share that is 25.4% higher year over year, supported by a record order backlog above US$21b tied to AI oriented data center and infrastructure demand.
- The near 30% organic order growth tied to AI related data centers indicates that Johnson Controls International is increasingly connecting its building solutions to mission critical digital infrastructure, where reliability, energy efficiency, and long term service agreements matter more than one off equipment sales.
- We will examine how Johnson Controls International's investment narrative is influenced by its record AI data center backlog ahead of earnings.
Scan beyond Johnson Controls International and see which other AI infrastructure players are building momentum with our curated list of 55 AI infrastructure stocks.
Johnson Controls International Investment Narrative Recap
To own Johnson Controls International, you need to believe the AI driven data center pipeline can translate into steadier earnings power, not just big orders on paper. The record US$21b backlog linked to these projects supports that idea, as long as execution on installation, commissioning and service keeps pace with demand and project timing.
The key near term swing factor is how efficiently Johnson Controls International converts this backlog into revenue and higher margin service contracts. The biggest current risk sits in operational complexity and uneven performance in security and Fire and Security, which could dilute the benefit from data center strength if simplification and productivity gains stall.
One operational highlight that ties directly to this setup is management’s focus on new thermal management offerings such as absorption chillers, CDUs and AI factory reference designs. These technologies are aimed at lowering cooling power use in data centers, which directly targets a major cost and reliability issue for operators.
When paired with the AI oriented backlog, these offerings give Johnson Controls International more dollar content per megawatt and more touchpoints for long term service work. That is where the key catalyst and risk intersect. Strong execution could support a richer mix of recurring revenue and margins, while any delivery issues or cost overruns on these complex projects would quickly show up in earnings quality.
What The Current AI Setup Implies For Johnson Controls International’s Numbers
Johnson Controls International's narrative projects US$31.3b revenue and US$4.6b earnings by 2029. This rests on analysts assuming 7.8% yearly revenue growth and implies an increase of about US$2.4b in earnings from the current US$2.2b level.
Uncover why Johnson Controls International's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the real catalyst as Johnson Controls International pushing data center related revenue toward roughly one third of the business, with revenue assumptions near US$32.7b and earnings of about US$4.9b by 2029. That is far above consensus, and both narratives were set before this earnings update, so you may want to compare several viewpoints and assess which assumptions appear more realistic to you.
Explore 3 other Johnson Controls International fair value estimates, including one that suggests as much as 34% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Johnson Controls International research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Johnson Controls International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Johnson Controls International's overall financial health at a glance.
Looking For More Ideas Beyond Johnson Controls International?
If you want to pressure test your Johnson Controls International thesis against other opportunities, use the Simply Wall St Screener to scan for stocks that match the mix of quality, valuation, and risk that fits your playbook.
- For investors who want potential upside with some financial resilience, start with a curated group of 21 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation matters more to you than chasing every swing, narrow your focus to a 30 resilient stocks with low risk scores that scores well on balance sheet strength and business stability.
- Income focused readers who care about reliability as much as yield can zero in on a set of 5 dividend fortresses that aim to pair higher payouts with sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com