


EN
CoStar Group (CSGP) Stock Dropped, So What Is Driving Attention Now?
Fresh industrial leasing data from CoStar Group (CSGP) shows new lease activity back at historical highs, with large occupiers driving deals of 200,000 square feet or more in major logistics hubs.
For CoStar Group, that renewed leasing activity sits against a share price of US$33.92 and a sharp disconnect between short bursts of optimism and a tougher longer run. The stock has rallied with a 30-day share price return of 20.75% and a 90-day gain of 16.28%. Yet this momentum comes after a heavy reset, with the year-to-date share price down 48.36% and the 1-year total shareholder return declining 56.45% as investors reassess both growth potential and risk around the real estate data and marketplace story.
Analyze CoStar Group in context by comparing it with our hand-picked list of solid balance sheet and fundamentals (24 results), which also links real assets, data, and recurring revenue to current market sentiment.
CoStar Group appears to be a robust real estate data utility tied to real activity, yet the share price has swung from heavy losses to a sharp short term rebound. Is that business now on sale, or still expensive?
Most Popular Narrative: 9% Undervalued
CoStar Group’s most followed valuation storyline pegs fair value at $37.30, modestly above the recent $33.92 close. This puts the recent share price reset in a different light for anyone focused on long term cash flows.
The key thing that has to go right is that CoStar Group turns Homes.com, Apartments.com, Zonda, international portals and AI products into a durable, profitable multi-vertical platform, despite muted bookings, lower revenue guidance and competitive pressure in multifamily advertising.
The current valuation of CoStar Group implies that the market is discounting execution risk around revenue growth, Homes.com scalability and AI disruption more heavily than the recent uplift in margins and record adjusted EBITDA guidance.
See why 30 investors see CoStar Group as 9% undervalued.
Result: Fair Value of $37.30 (UNDERVALUED)
Still, muted net new bookings, softer 2026 revenue guidance, and pressure on Apartments.com pricing could easily flip the CoStar Group narrative if those trends deepen.
Find out about the key risks to this CoStar Group narrative.
Another View: CoStar Group On Sales-Based Valuation
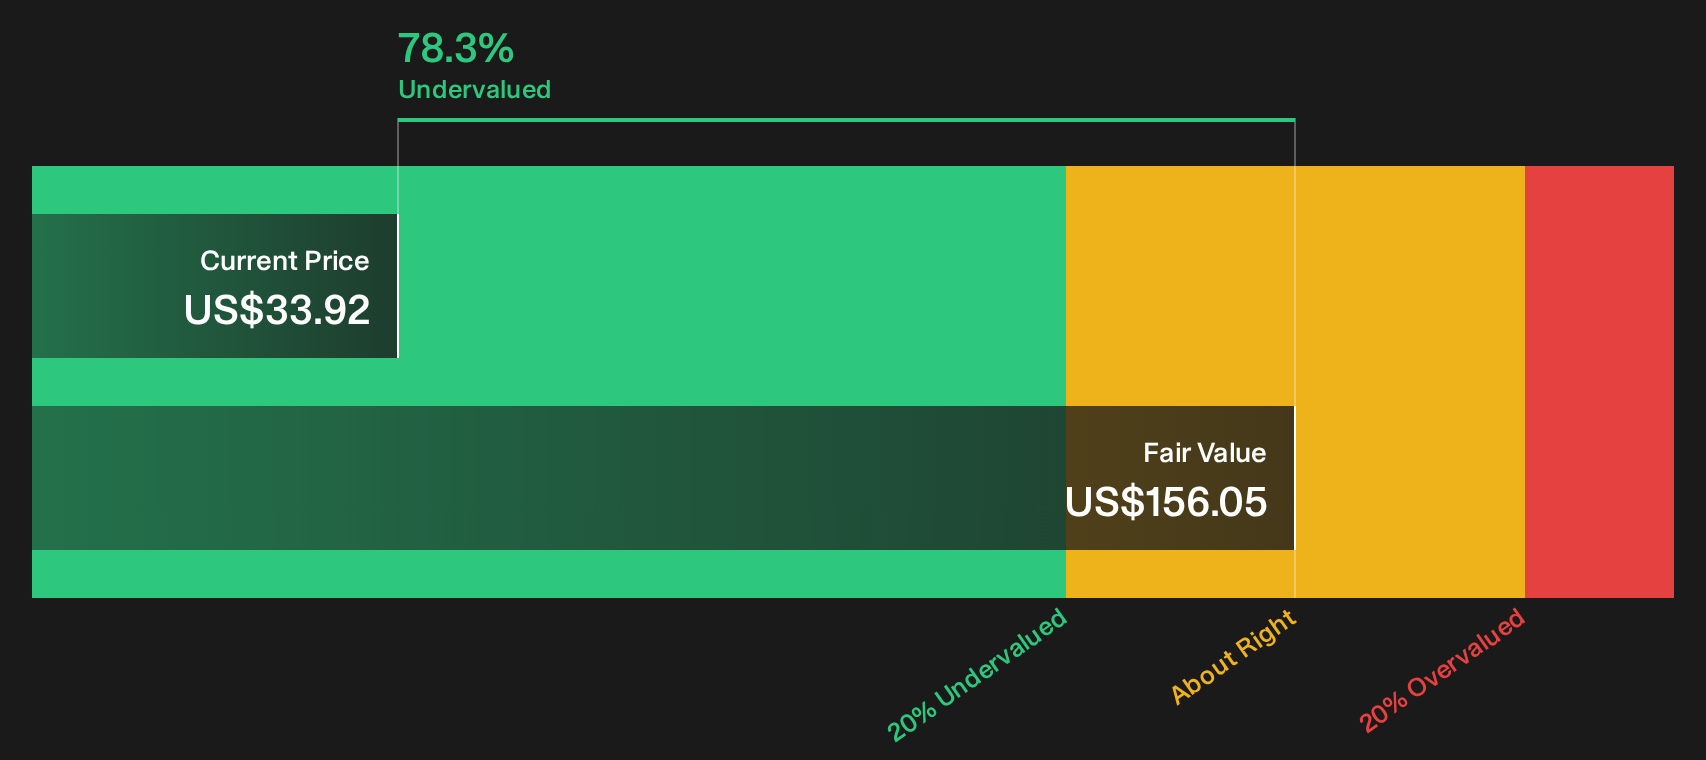
CoStar Group looks very cheap on our DCF work, with the share price of $33.92 compared with an estimated future cash flow value of $156.05. That points to a wide gap, yet it raises a question. Is the market mispricing long term cash generation, or are the cash flow assumptions too generous?
Investors who want to stress test those inputs against their own expectations can walk through how the SWS DCF model is built, step by step, in our valuation breakdown Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in CoStar Group’s story so far. If you want to move before sentiment shifts again, weigh both sides of the data, then check the balance of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond CoStar Group?
If CoStar Group has you rethinking valuation and timing, do not stop there. Fresh opportunities often show up where capital has not crowded in yet.
- Target resilient performance by scanning companies with strong balance sheets and fundamentals through our focused list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by reviewing our data driven lineup of 29 high quality undervalued stocks that may offer appealing fundamentals at current prices.
- Spot potential future leaders early by checking a curated set of 21 high quality undiscovered gems that combine robust financials with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com