


EN
Is Mapletree Industrial Trust (SGX:ME8U) Undervalued Following Strong Inflows And A REIT Rally?
Mapletree Industrial Trust (SGX:ME8U) has moved back into focus after strong investor inflows of S$6.19 million during a sector-wide upswing in data-centre, retail and industrial REITs, prompting fresh debate over valuation and cash distributions.
That fresh interest comes after a mixed year for Mapletree Industrial Trust, with the unit price at SGD1.80 and a 1-day share price gain of 2.27%. This sits against a year-to-date share price return that is down 13.04% and a 1-year total shareholder return that is down 12.13%. At the same time, the 3-year total shareholder return of 1.64% suggests only modest long-run progress and points to momentum that had been fading until this latest sector-driven rebound hinted at a shift in sentiment toward its cash flow profile and perceived risks.
Scan how Mapletree Industrial Trust stacks up against other income-focused real estate plays by reviewing a curated 226 dividend fortresses that could suit a similar cash distribution profile.
Mapletree Industrial Trust owns a sizeable mix of data centres and industrial assets, yet its unit price only just bounced after a weak multi year return profile. Does that combination add up to a fair valuation today?
Most Popular Narrative: 8% Undervalued
The most followed narrative pegs Mapletree Industrial Trust’s fair value at about SGD1.96, implying an 8% gap to the recent SGD1.80 close. This puts execution risk around asset sales and recycling firmly in the spotlight.
Targeted recycling of S$500 to S$600 million of mainly North American data centre assets over 1 to 2 years, following more than S$500 million of divestments already completed at a premium to book value, creates scope for higher quality acquisitions that could support revenue and earnings quality.
See why 39 investors see Mapletree Industrial Trust as 8% undervalued.
Result: Fair Value of SGD1.96 (UNDERVALUED)
Still, the narrative can crack if higher borrowing costs strain distributable income or if North American data centre vacancies extend beyond currently identified non renewals.
Find out about the key risks to this Mapletree Industrial Trust narrative.
Another View: Multiples Flag A Richer Price For Mapletree Industrial Trust
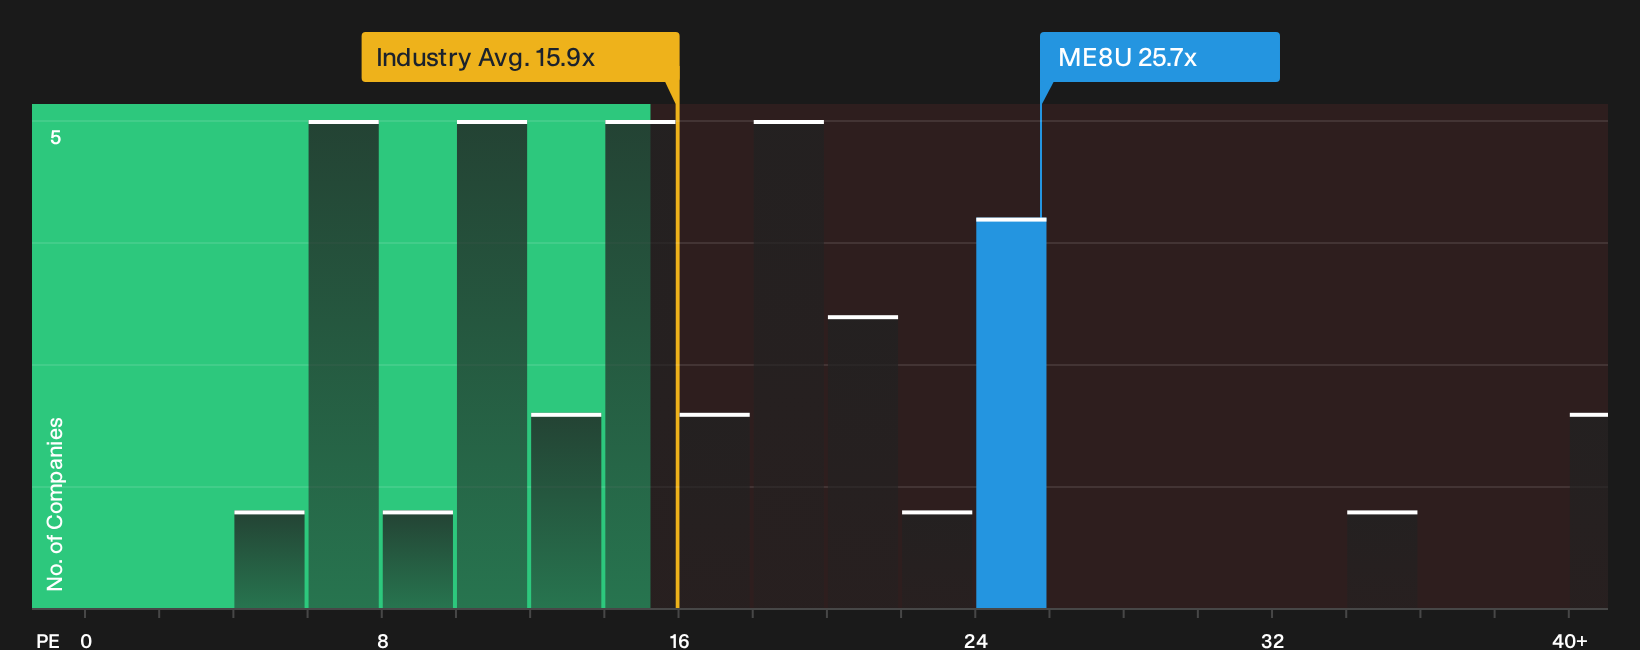
Our DCF lens points to value, yet the earnings multiple tells a tighter story. Mapletree Industrial Trust trades on a P/E of 25.7x compared with 15.9x for Asian industrial REITs and a fair ratio of 17.7x, which leaves less room if expectations slip.
That gap matters because it hints at investors already paying up for execution on recycling plans and distribution stability, with limited protection if things track closer to the sector or that fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Mapletree Industrial Trust often signal that risk and reward are pulling in different directions, so move fast and weigh the trade offs for yourself by checking the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Mapletree Industrial Trust?
If Mapletree Industrial Trust has sharpened your focus on income and valuation trade offs, you may want to broaden your watchlist now with a few targeted screeners tailored to different risk and return profiles.
- Hunt for quality at a discount by scanning a curated pool of 194 high quality undervalued stocks that combine solid fundamentals with more appealing price tags.
- Strengthen your defensive side by reviewing a 221 resilient stocks with low risk scores that highlights companies with more resilient risk profiles and fewer red flags.
- Spot potential early movers by checking a hand picked group of 613 high quality undiscovered gems before they attract wider attention and crowd in more capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com