


EN
What Resona Holders Got Right
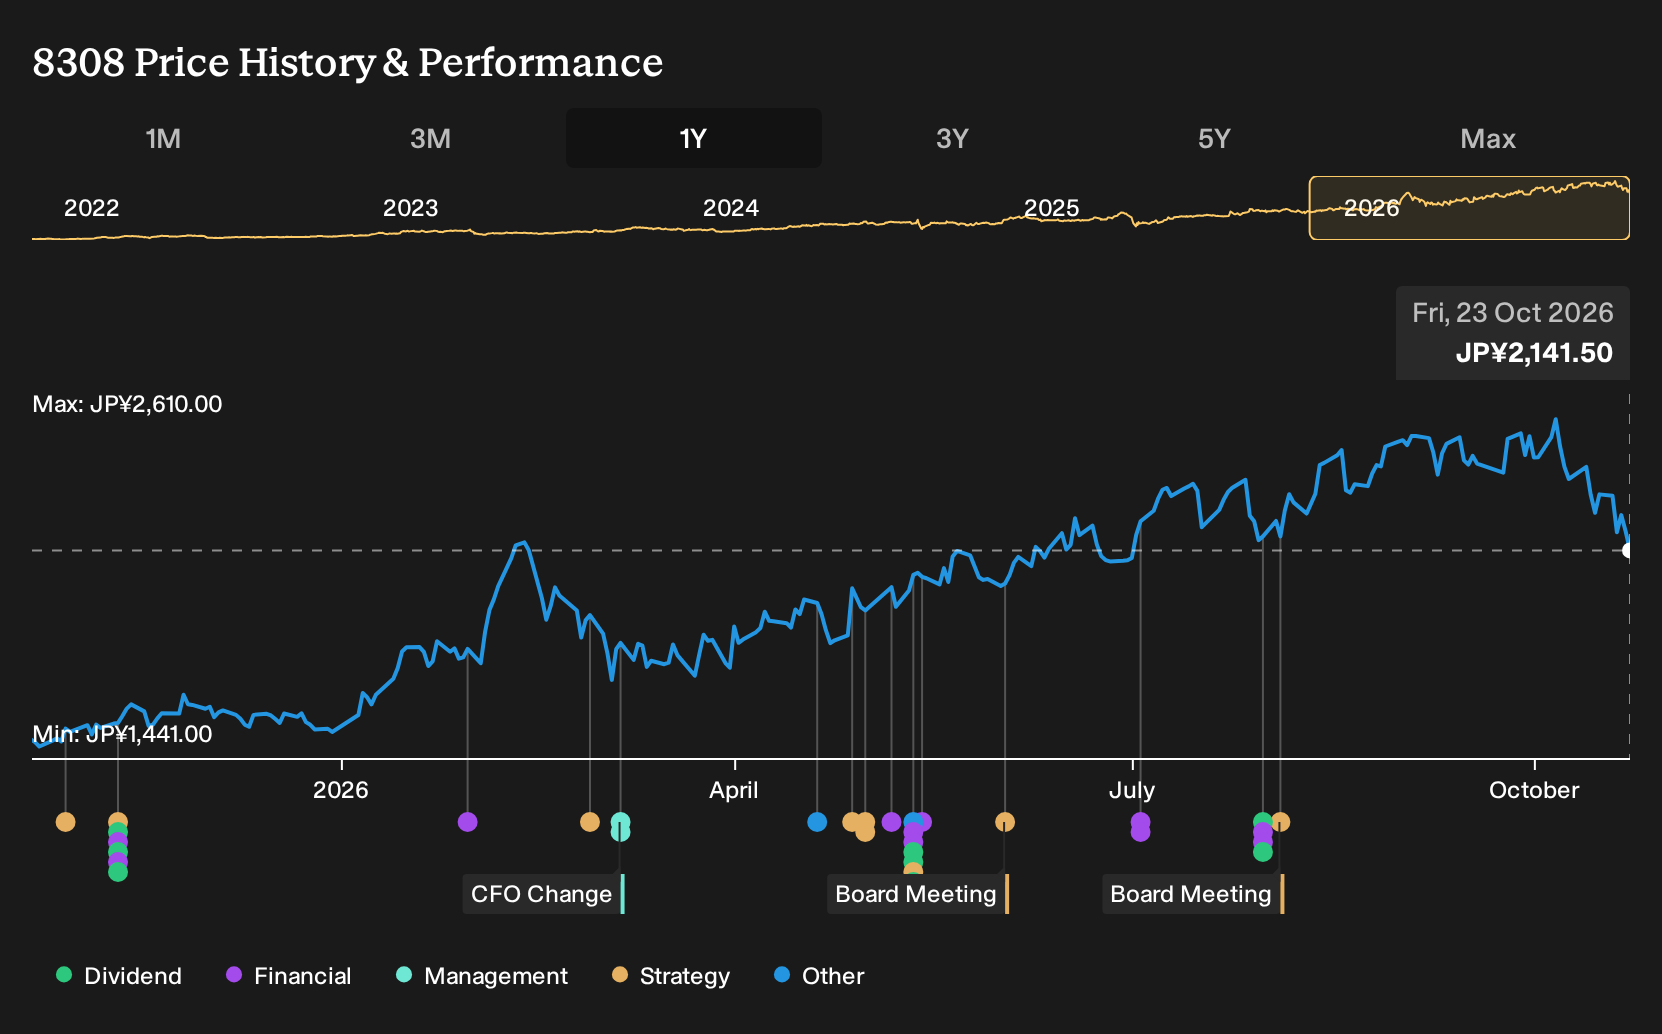
If Resona was on your watchlist instead of in your account over the past year, the outcome may feel expensive. Investors who held Resona over the past year are up 50.9%, including dividends. That move now sits alongside fresh Q1 2027 figures, where revenue and profit were both higher, but the net margin edged down. The real puzzle is whether an investor could have spotted the digitalization and demographic thesis early enough to trust rising earnings quality over falling top line forecasts.
The easy part of this move is behind Resona. Zero in on 14 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Resona
The shares cost ¥1,456 at the start of the period, and the core question for Resona investors was whether digitalization and demographics could transform a traditional bank into a higher quality earnings story.
The bullish narrative pointed to a Fair Value of ¥1,550, essentially the price implied if digital transformation, operational unification, and AI-driven cost cuts pushed profit margins toward 35.2% on slightly declining revenue.
The bearish narrative argued for a Fair Value of ¥950, reflecting concern that Japan's aging population, domestic concentration, and rising compliance and technology costs could drive revenue down 7.3% a year even if margins improved to 32.1%.
What The Results Changed For The Resona Thesis
The clearest new fact was Q1 2027 revenue of ¥288,026m against ¥248,800m a year earlier, with net income at ¥80,526m versus ¥70,530m. Net margin slipped from 28.3% to 28.0%, so profitability quality did not move decisively toward the 35.2% bull target. The evidence cut both ways for the original Resona arguments.
The useful takeaway is where to look next. If the story hangs on digitalization improving earnings quality, future checks should focus on net margin and cost to income, rather than just headline revenue or loan growth.
What Resona's Price Already Assumes Today
Resona now trades at ¥2,142, which leaves this Narrative's Fair Value sitting below the market price rather than above it. That gap reflects concern that deposit funding and fee ambitions may not both progress smoothly.
A buyer today is effectively assuming higher return on equity and better efficiency, so the selected Narrative's questions on deposit pressure and digital adoption need careful testing against that belief.
"Although Resona Holdings highlights earnings leverage to higher interest rates, reliance on a sticky deposit base in an aging society with positive policy rates may prove fragile if customers gradually shift to higher yielding alternatives, which could lift deposit beta and narrow net interest margins. While management targets a larger shift toward fee income and ecosystem services, the need to use these offerings to compensate for macro level pressure on deposits risks prioritising customer retention over pricing power, which may cap future fee revenue and limit the intended uplift to earnings."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Another Way To Think About Resona
Looking at Resona, you are weighing what banking becomes when digital tools meet aging customers.
If that tension interests you, just beside it sits the heavy machinery of global finance.
Here, a different institution leans on scale across consumer banking, markets activity, and asset management.
It helps clients raise capital, move money, manage assets, and process complex cross-border transactions.
The open question is how that breadth, and the shift into data intensive services, might quietly redirect where your attention goes next.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 26% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com