


EN
How Investors Are Reacting To Fifth Third Bancorp Stock As Earnings Improve
- Fifth Third Bancorp reported third quarter 2026 net interest income of US$2,271 million and net income of US$866 million, both higher than the prior year period. Nine month figures reached US$6,420 million and US$1,832 million respectively.
- The bank's net losses charged off in the third quarter fell to US$139 million from US$339 million a year earlier, pointing to improved credit performance alongside stronger reported profitability.
- We will look at how Fifth Third Bancorp's investment narrative aligns with this quarter's higher net income and lower net charge offs.
Scan for other banks showing a similar mix of higher earnings and cleaner credit, such as Fifth Third Bancorp, by running the curated 30 resilient stocks with low risk scores alongside this update.
Fifth Third Bancorp Investment Narrative Recap
To own Fifth Third Bancorp, you need to be comfortable with a deposit-led bank leaning on expansion, technology and M&A integration to keep earnings resilient. The third quarter jump in net interest income and higher net income support that narrative, while the drop in net charge-offs suggests credit costs are not the main headache right now.
The nearer-term swing factor is how deposit pricing and Comerica integration play out. If digital glitches or integration snags reappear, they could pressure deposit growth and fee income. The Dividend solar lending reset and home equity pivot remain watchpoints, although this quarter’s results do not materially change that risk balance.
The earnings announcement for the third quarter to September 30, 2026 is the clearest data point tied to this update. Net interest income of US$2,271 million and net income of US$866 million, alongside lower net charge-offs of US$139 million, speak directly to how Fifth Third Bancorp is managing funding, credit and integration at the same time.
For catalysts, you are effectively weighing whether this earnings power can support the Southeast and Southwest build-out, Comerica synergy goals and technology spending without eroding returns. Lower charge-offs give some room, but deposit competition, solar-related fee pressure and any repeat of online banking issues still sit front and center in the execution story.
Fifth Third Bancorp's story is anchored to analyst expectations that revenue reaches US$16.4b and earnings climb to US$4.3b by 2029, based on a 17.7% yearly revenue growth rate and an earnings increase of about US$2.1b from current earnings of US$2.2b.
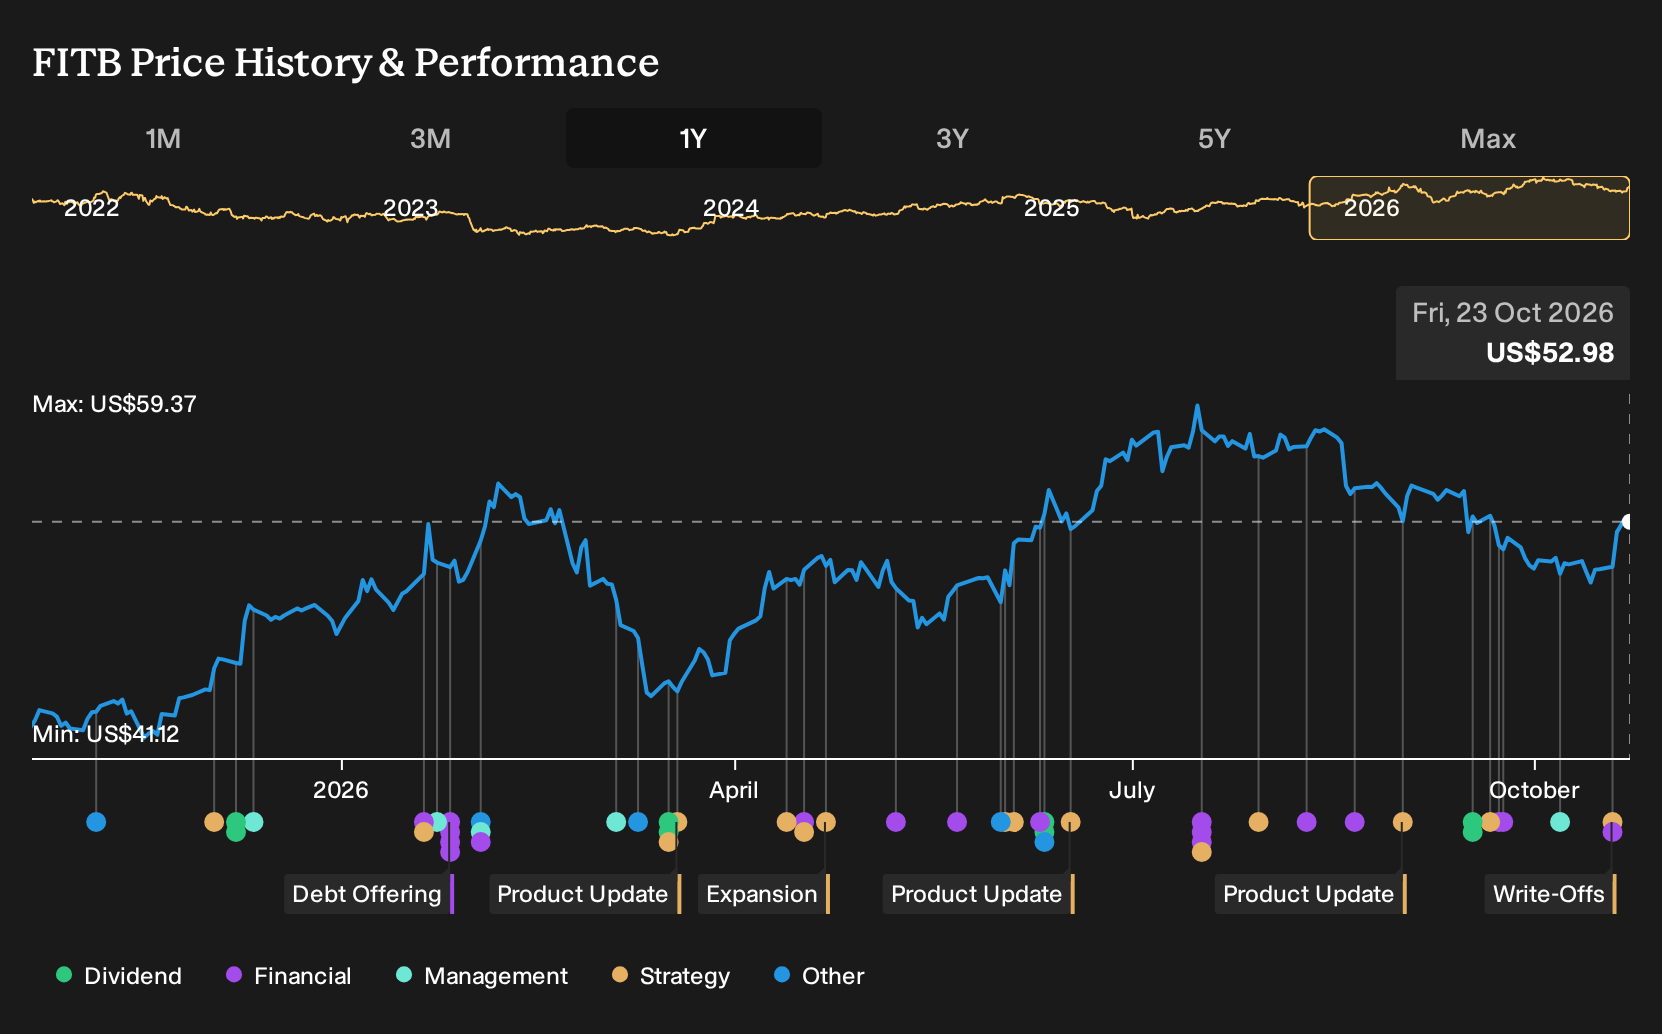
Uncover why Fifth Third Bancorp's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$61 to US$97, so private investors are treating Fifth Third Bancorp as anything from modestly priced to materially undervalued. Set that against risks like tougher deposit competition or solar lending pressure, and you see how sharply opinions can diverge. Explore those alternative viewpoints before deciding how this earnings print fits your own thesis.
Explore 2 other Fifth Third Bancorp fair value estimates, including one that suggests as much as 83% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fifth Third Bancorp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fifth Third Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fifth Third Bancorp's overall financial health at a glance.
Looking for more ideas beyond Fifth Third Bancorp?
Once you have a view on Fifth Third Bancorp, it can help to cross check that thesis against other companies with similar or contrasting traits. A targeted screener keeps you focused on clear criteria instead of headline noise.
- For investors who want cash flow strength without excessive balance sheet strain, start with a list of solid balance sheet and fundamentals (24 results) that pass basic fundamental quality checks.
- If you are hunting for stocks that the market might be pricing cautiously, filter for quality businesses trading below their implied worth using the 29 high quality undervalued stocks as a jumping off point.
- When income reliability matters most, focus on companies that pair higher yields with resilient financial profiles through a curated set of 5 dividend fortresses designed to keep payouts front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com