


EN
How Earnings Estimate Upgrades At RenRe (RNR) Have Changed Its Investment Story
- Recent reports highlighted that analysts have raised earnings estimates for RenaissanceRe Holdings after a period of four consecutive EPS beats, with attention on how underwriting profit, fee income and investment returns support near term performance despite an expected decline in reported revenue.
- An important consideration for investors is how RenaissanceRe Holdings is leaning on its diversified earnings mix, using underwriting discipline, third party capital fees and retained investment income to support profitability even while top line revenue expectations are softer.
- This article will review how RenaissanceRe Holdings' investment narrative is influenced by renewed confidence in its earnings power and estimate revisions.
Scan how earnings driven insurers like RenaissanceRe Holdings compare with peers by reviewing our hand-picked list of 29 high quality undervalued stocks.
RenaissanceRe Holdings Investment Narrative Recap
To own RenaissanceRe Holdings, you need to be comfortable with a reinsurance model that leans on underwriting discipline, fee income from third party capital and retained investment returns rather than headline premium growth. The key short term swing factor is how clean catastrophe experience and casualty loss trends remain relative to that earnings mix.
The biggest risk right now is the increased exposure to U.S. property catastrophe events, especially if several large losses arrive close together. A planned step up in operating expenses into 2026 also raises the bar for underwriting and fee income, and the latest estimate upgrades do not fully remove that execution pressure.
The most relevant development linked to the recent confidence in RenaissanceRe Holdings is the continued build out of its three driver earnings model. Underwriting profit, fee income of about US$80m to US$90m per quarter from capital partners and net investment income above US$300m per quarter provide three distinct levers supporting results.
This mix matters if top line revenue expectations are softer and analysts see earnings declining over the next few years. Stronger than expected EPS in the recent past indicates the model has held up in practice. However, exposure to U.S. catastrophe risk, social inflation in casualty and a higher expense base still shape how reliable those earnings drivers appear in future periods.
RenaissanceRe Holdings Forecast Set Against Analyst Assumptions
Analysts are effectively asking investors to underwrite a very different earnings profile for RenaissanceRe Holdings over the next few years. The stock narrative now leans on a path where reported revenue steps down each year while profit margins compress and earnings settle at a lower but still sizeable level by the end of the decade.
The core assumption is a 13.1% annual decline in revenue over the next 3 years. That is a steep adjustment, and it puts even more attention on how RenaissanceRe Holdings manages its underwriting book, fee income streams and investment portfolio to support profitability when the top line is moving in reverse.
Earnings today sit around US$2.6b. Consensus points to about US$1.3b of profit by 2029, with a more optimistic camp looking for up to US$1.5b. That profile requires investors to accept an earnings drop of roughly US$1.3b from current levels, which is a very different proposition from underwriting a growth story.
On these forecasts, analysts are implicitly valuing a leaner profit stream at a higher multiple. The framework uses a P/E of 11.0x on 2029 earnings compared with about 5.3x on current earnings, paired with a discount rate around 7.2% to 7.24% and an assumption that the share count declines by roughly 7% a year for the next 3 years.
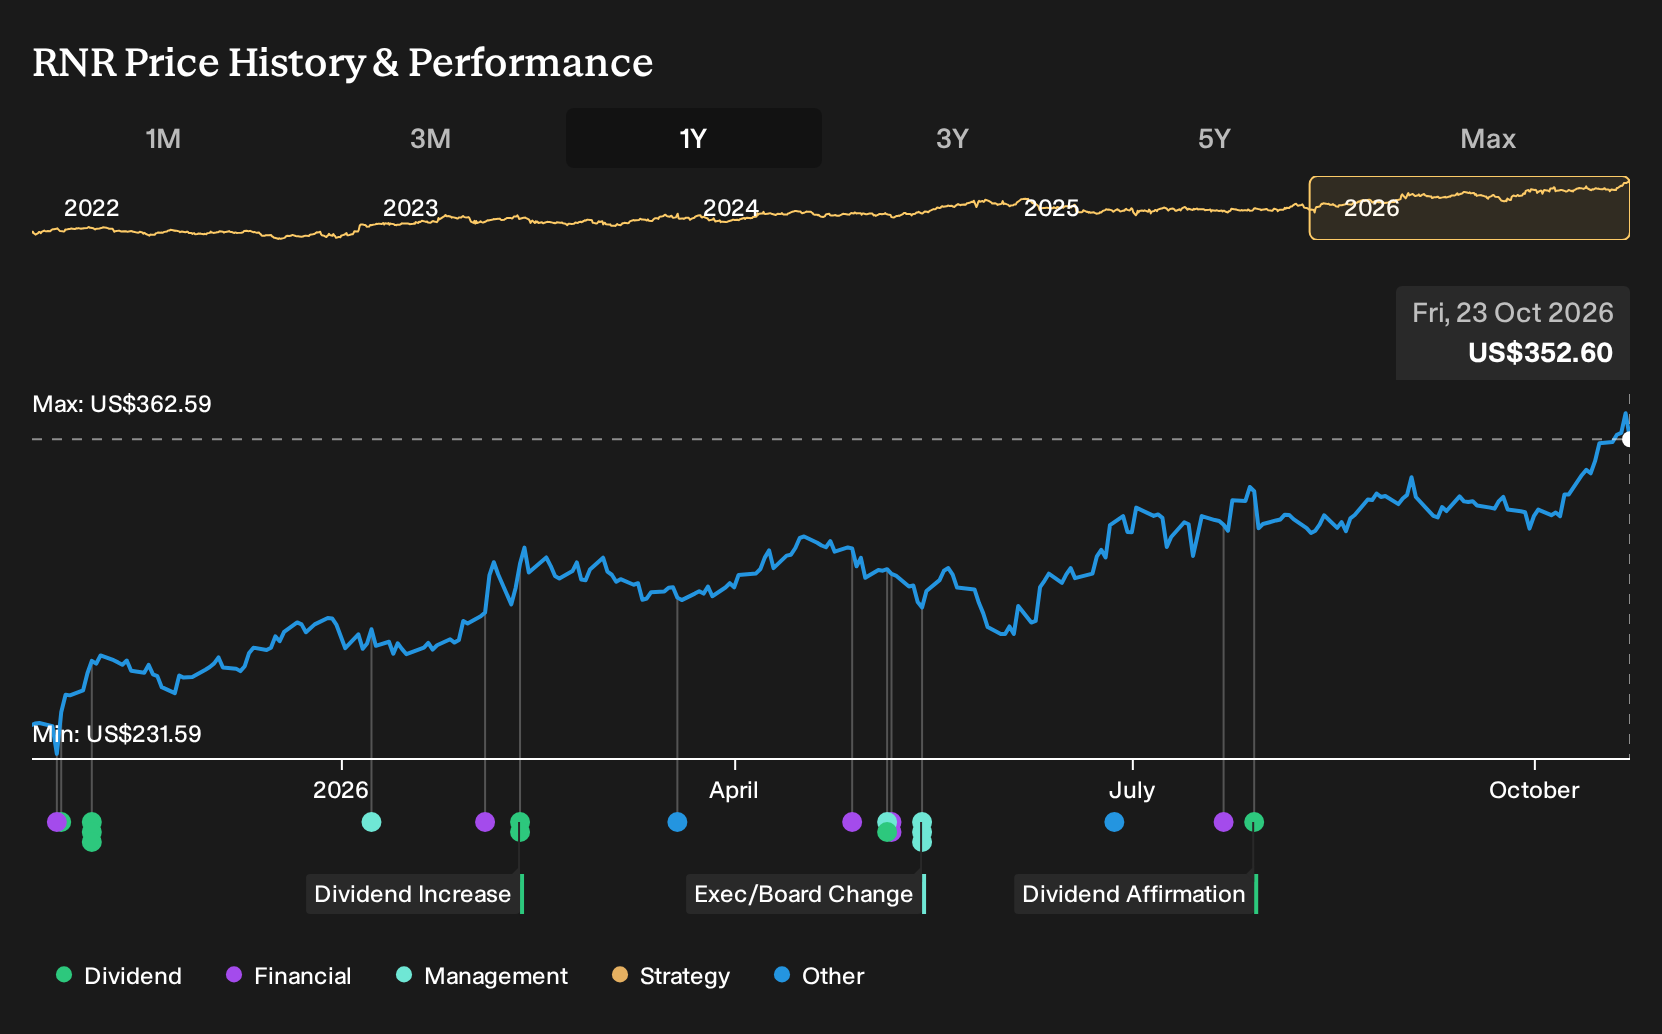
Put together, that bundle of expectations underpins a consensus price target of US$347.31 a share against a current price of US$322.99, with a range running from US$312.00 on the cautious end up to US$422.00 on the most optimistic view. In plain terms, the market is being asked to pay close to fair value today for an insurer that analysts already expect to earn less in 2029 than it does now.
RenaissanceRe Holdings' narrative projects US$7.3b revenue and US$1.3b earnings by 2029. This assumes revenue will decline 13.1% per year and earnings will decrease by about US$1.3b from US$2.6b today.
Discover why RenaissanceRe Holdings' fair value points to a valuation gap that aligns with its current price.
Exploring Other Perspectives
One alternate angle on RenaissanceRe Holdings focuses on capital management as the key upside catalyst. The most optimistic analysts were previously pencilling in about US$8.3b of 2029 revenue and US$1.5b of earnings, leaning on buybacks and mix shift. Those views may evolve as the latest earnings revisions are incorporated.
Explore 2 other RenaissanceRe Holdings fair value estimates, including one that suggests as much as 188% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis.
- A great starting point for your RenaissanceRe Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RenaissanceRe Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RenaissanceRe Holdings' overall financial health at a glance.
Looking for more investment ideas beyond RenaissanceRe Holdings?
RenaissanceRe Holdings might be the starting point for your research, not the finish line. If you want to widen your opportunity set and test your thinking against very different business models and balance sheets, the Simply Wall St Screener offers several focused stock lists that can help you move from theory to a watchlist quickly.
- If you care most about quality businesses trading below what their fundamentals might justify, scan our hand picked lineup of 29 high quality undervalued stocks and see which ones deserve a deeper look.
- If resilience and capital strength matter more to you than headline growth, filter for companies on the list of solid balance sheet and fundamentals (24 results) and compare how their financial footing stacks up.
- If you want ideas that many investors may be overlooking, start with the 21 high quality undiscovered gems and build a shortlist of under the radar stocks worth further research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com