


EN
Why Atlanticus Holdings Stock Is Getting Attention For Its Undervalued Rating
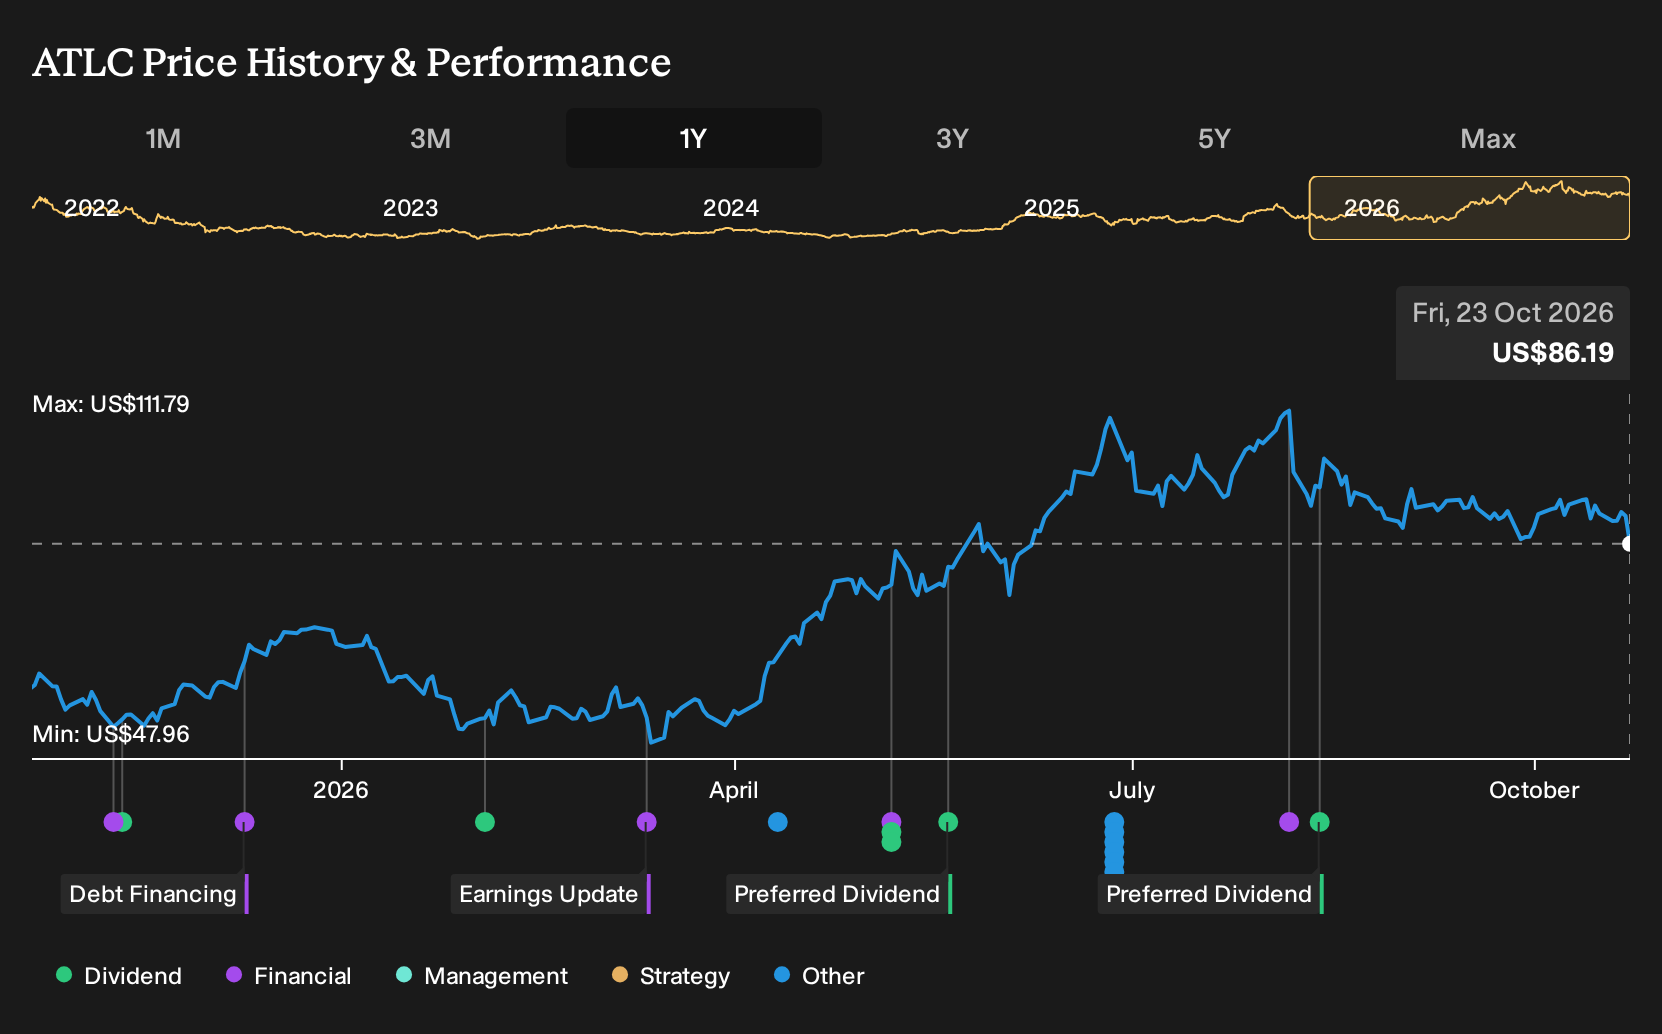
- Recent coverage highlights Atlanticus Holdings as having an A-rated value profile, with its Forward P/E and P/B ratios sitting below consumer finance peers while the business continues to focus on near prime and underserved borrowers through cards and point of sale products.
- The attention on Atlanticus Holdings valuation puts a spotlight on how efficiently management can integrate the Mercury Financial acquisition and potential cost savings from consolidating platforms into a single, larger operating system.
- We will now look at how Atlanticus Holdings valuation-focused coverage interacts with its existing investment narrative built around platform scale.
Atlanticus Holdings Investment Narrative Recap
To own Atlanticus Holdings, you need to be comfortable with a lender that focuses on near-prime and underserved borrowers while trying to scale a larger card and point of sale platform. The key near-term factor is how credit performance holds up across that customer base, given their sensitivity to essential costs and funding conditions. The recent valuation-focused coverage does not materially change that operating backdrop.
The larger operational risk still lies with integrating Mercury Financial within the roughly 18-month plan and achieving the expected cost savings from running one consolidated platform. If those efficiencies slip or servicing costs remain higher for longer, earnings and returns on assets could look less attractive, regardless of Atlanticus valuation metrics.
The most recent data point tied to this news is Atlanticus Holdings carrying an A grade for value, with a forward P/E and P/B below many consumer finance peers, alongside a P/E of about 9x compared with a US market multiple of 18.4x. That relative pricing frames expectations around how well the enlarged platform can convert receivable growth into consistent profit over the next few years.
For catalysts, the Mercury integration and system consolidation remain central. Management aims to bring a roughly US$3b portfolio fully under Atlanticus methods, reduce overlapping vendor and personnel costs, and potentially increase margins on a balance sheet of about US$7b. Any clear operational update on integration timing, funding access, or card response rates is likely to matter more to the story than the latest valuation label on its own.
Atlanticus Holdings Analyst Scenario Check
Analysts currently sketch an aggressive expansion path for Atlanticus Holdings. Their base case points to revenue climbing to US$5.5b and earnings reaching US$451.9m by 2029, off current earnings of US$144.8m. That implies earnings would need to more than triple, roughly a 3x step up from where profit sits today.
Atlanticus Holdings' narrative projects US$5.5b revenue and US$451.9m earnings by 2029. This rests on analysts assuming 96.2% yearly revenue growth and roughly a 3x earnings increase from US$144.8m today.
Uncover why Atlanticus Holdings' fair value indicates a 55% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate take on Atlanticus Holdings leans heavily on Mercury integration as a major upside catalyst. The most optimistic analysts were sketching revenue of about US$5.1b and earnings of roughly US$484.8m by 2029 before this valuation news. You can treat this new A rated value signal as fresh input that might shift those forecasts, then compare several viewpoints before deciding what feels reasonable.
Explore 4 other Atlanticus Holdings fair value estimates, including one that suggests as much as 115631% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Atlanticus Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Atlanticus Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atlanticus Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Atlanticus Holdings?
Once you have a view on Atlanticus Holdings, it can help to compare its profile with other businesses that share similar strengths or offer very different risk and reward trade offs.
- If you want potential mispricing with financial quality, scan our hand picked 29 high quality undervalued stocks and see which businesses match your preferred fundamentals.
- If balance sheet resilience matters most to you, filter for companies through the list of solid balance sheet and fundamentals (24 results) and compare how their financial footing lines up with your risk tolerance.
- If you are hunting for opportunities that are less widely followed, cast a wider net across the 21 high quality undiscovered gems and see what else fits your checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com