


EN
Opendoor Technologies (OPEN) Is Back In Focus, But What Is The Market Weighing?
Opendoor Technologies (OPEN) is back in focus after an executive reshuffle, with President Lucas Matheson stepping down and Chief Executive Officer Kaz Nejatian taking on the President title as well.
Recent market action around Opendoor Technologies has been weak, with the share price down 23% over the past 30 days and 49% over 90 days, and a 1-year total shareholder return that has declined 75%. This points to fading momentum as investors reassess execution risk, housing headwinds and the value of its real estate platform following leadership changes.
Spot opportunities beyond Opendoor Technologies by scanning a hand picked 29 high quality undervalued stocks with stronger momentum and more resilient business models.With Opendoor Technologies sliding to US$1.98 after steep recent losses, the real fork in the road is timing. Does it make more sense to step in at this level, or to wait for a cleaner entry based on valuation?
Most Popular Narrative: 54% Undervalued
At a last close of $1.98 versus a narrative fair value of $4.27, Opendoor Technologies screens as heavily marked down while analysts still frame a path that leans on faster top line expansion and improved unit economics.
Ongoing cost efficiency initiatives and operating as a leaner organization aim to improve net margins by reducing fixed costs, enhancing profitability despite macroeconomic challenges.
Expanding product offerings such as List with Opendoor and the Marketplace, alongside better targeting sellers outside of their buy box, could unlock new revenue streams and grow overall earnings.
See why 78 investors see Opendoor Technologies as 54% undervalued.
Based on this most followed narrative, Opendoor Technologies is modeled with a fair value of $4.27 using a 10.10% discount rate and assumptions that include revenue growth of about 53.8% and a long term profit margin of 5.8% converging toward the wider US real estate sector.
These projections also factor in expected share count expansion of 7.0% per year and a future P/E multiple of roughly 9.9x on potential 2029 earnings of $683.0 million, which is below the current 15.5x P/E used for the broader US real estate industry in the narrative.
For this set of inputs to hold, you would need to be comfortable that Opendoor Technologies can manage inventory risk, higher leverage and a relatively new leadership bench while still lifting margins from a current loss of $1.5b to that modeled earnings level.
Analysts cited in the narrative are split, with targets ranging from $1.00 to $7.00, so the 54% discount to the $4.27 fair value and the 53.6% discount to that same figure flagged elsewhere both rely on a wide spread of opinions that readers may want to test against their own expectations for housing activity and Opendoor Technologies' execution.
Result: Fair Value of $4.27 (UNDERVALUED)
Still, the narrative only holds if Opendoor Technologies can contain inventory risk in a slower housing market and manage its sizeable asset backed borrowings without restricting flexibility.
Find out about the key risks to this Opendoor Technologies narrative.
Another View On Opendoor Technologies Valuation
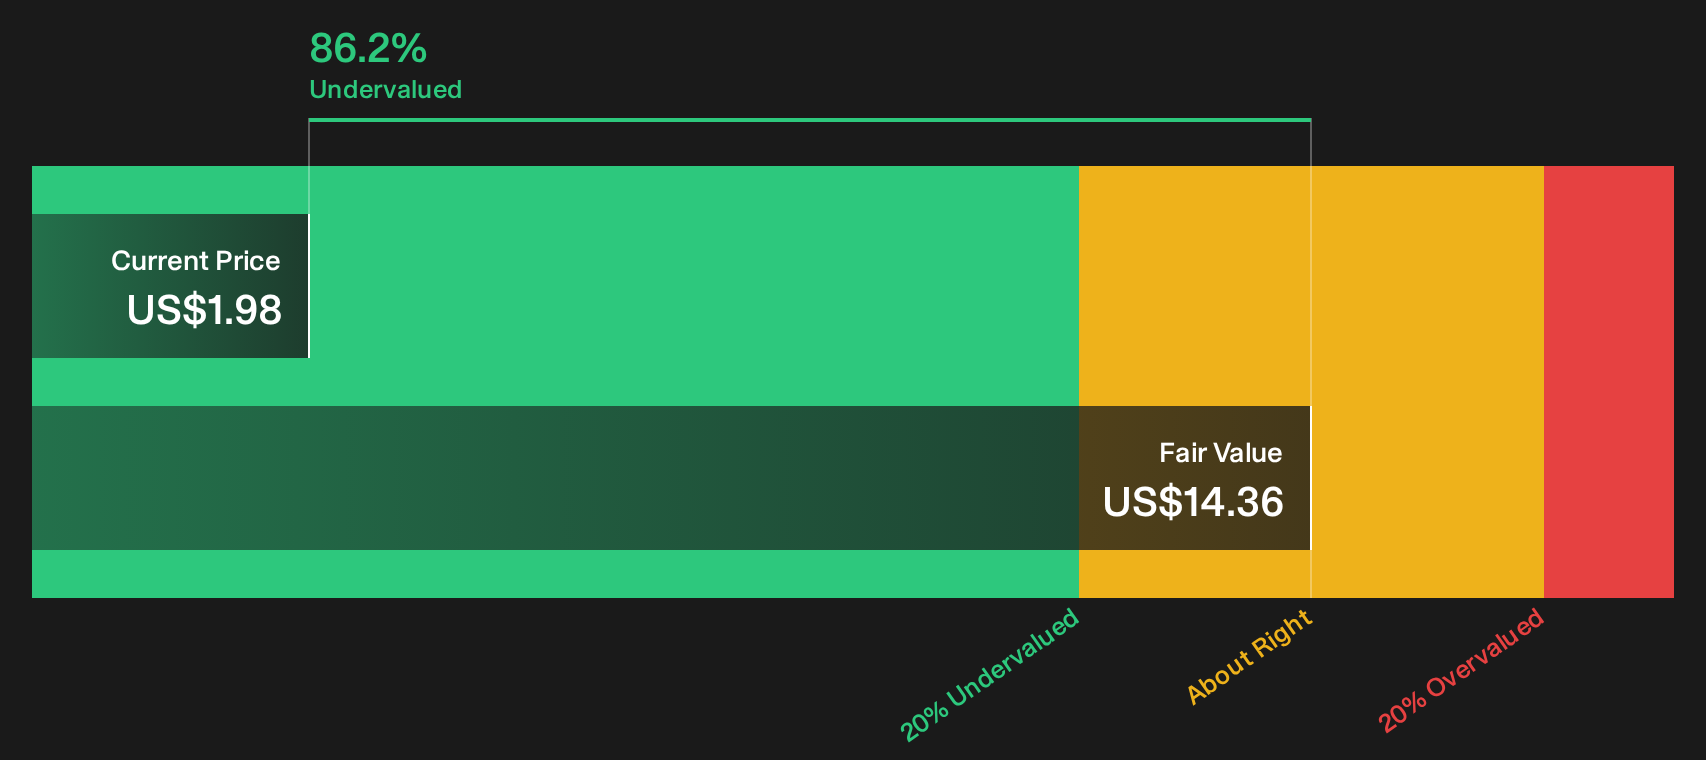
There is a very different signal coming from the SWS DCF model. On that framework, Opendoor Technologies at $1.98 is trading well below an estimated future cash flow value of $14.36. This also screens as undervalued but with much more upside embedded in the assumptions. The real issue for you is which set of inputs feels realistic.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals across Opendoor Technologies will only matter if you act on them, so move quickly and review the full picture of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Opendoor Technologies?
If Opendoor Technologies has your attention, do not stop there. A broader watchlist gives you options when single stories break, disappoint, or surprise.
- Target potential upside by scanning a focused list of companies that may be mispriced on quality and value using the 29 high quality undervalued stocks.
- Emphasize financial resilience by searching for businesses with robust finances through the list of solid balance sheet and fundamentals (24 results).
- Explore underfollowed opportunities before they gain wider attention by checking the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com