


EN
How Earnings Beat At AMN Healthcare Services (AMN) Has Changed Its Investment Story
- AMN Healthcare Services reported second quarter net income of $21.2 million and adjusted earnings of $0.77 per share, both ahead of expectations, supported by strong demand for temporary healthcare staffing tied to labor disruptions, travel nurses and allied professionals.
- Beyond the earnings surprise, the business saw stronger profitability from labor disruption staffing, which raised questions about whether healthier cash flows now align with the current valuation suggested by discounted cash flow analysis.
- We will now examine how AMN Healthcare Services' investment narrative is affected by the earnings beat and surge in temporary staffing demand.
Scan beyond AMN Healthcare Services and see how other staffing and healthcare players are reacting to similar catalysts with a curated list of 29 high quality undervalued stocks.
AMN Healthcare Services Investment Narrative Recap
To own AMN Healthcare Services, you need to believe that demand for flexible clinicians, travel nurses, and allied professionals remains structurally important for hospitals, and that tech enabled staffing continues to improve how efficiently that demand is filled. The recent earnings beat and profitability from labor disruption work point to solid near term execution, but the core story still hinges on sustainable volume, not just episodic strike activity.
The key short term catalyst is whether elevated travel nurse and allied volumes persist after this surge in labor disruption assignments. The biggest near term risk is that hospitals lean harder into permanent hiring or internal float pools, which could affect order volumes, while pressure in Technology and Workforce Solutions or slower Physician and Leadership momentum weighs on margins.
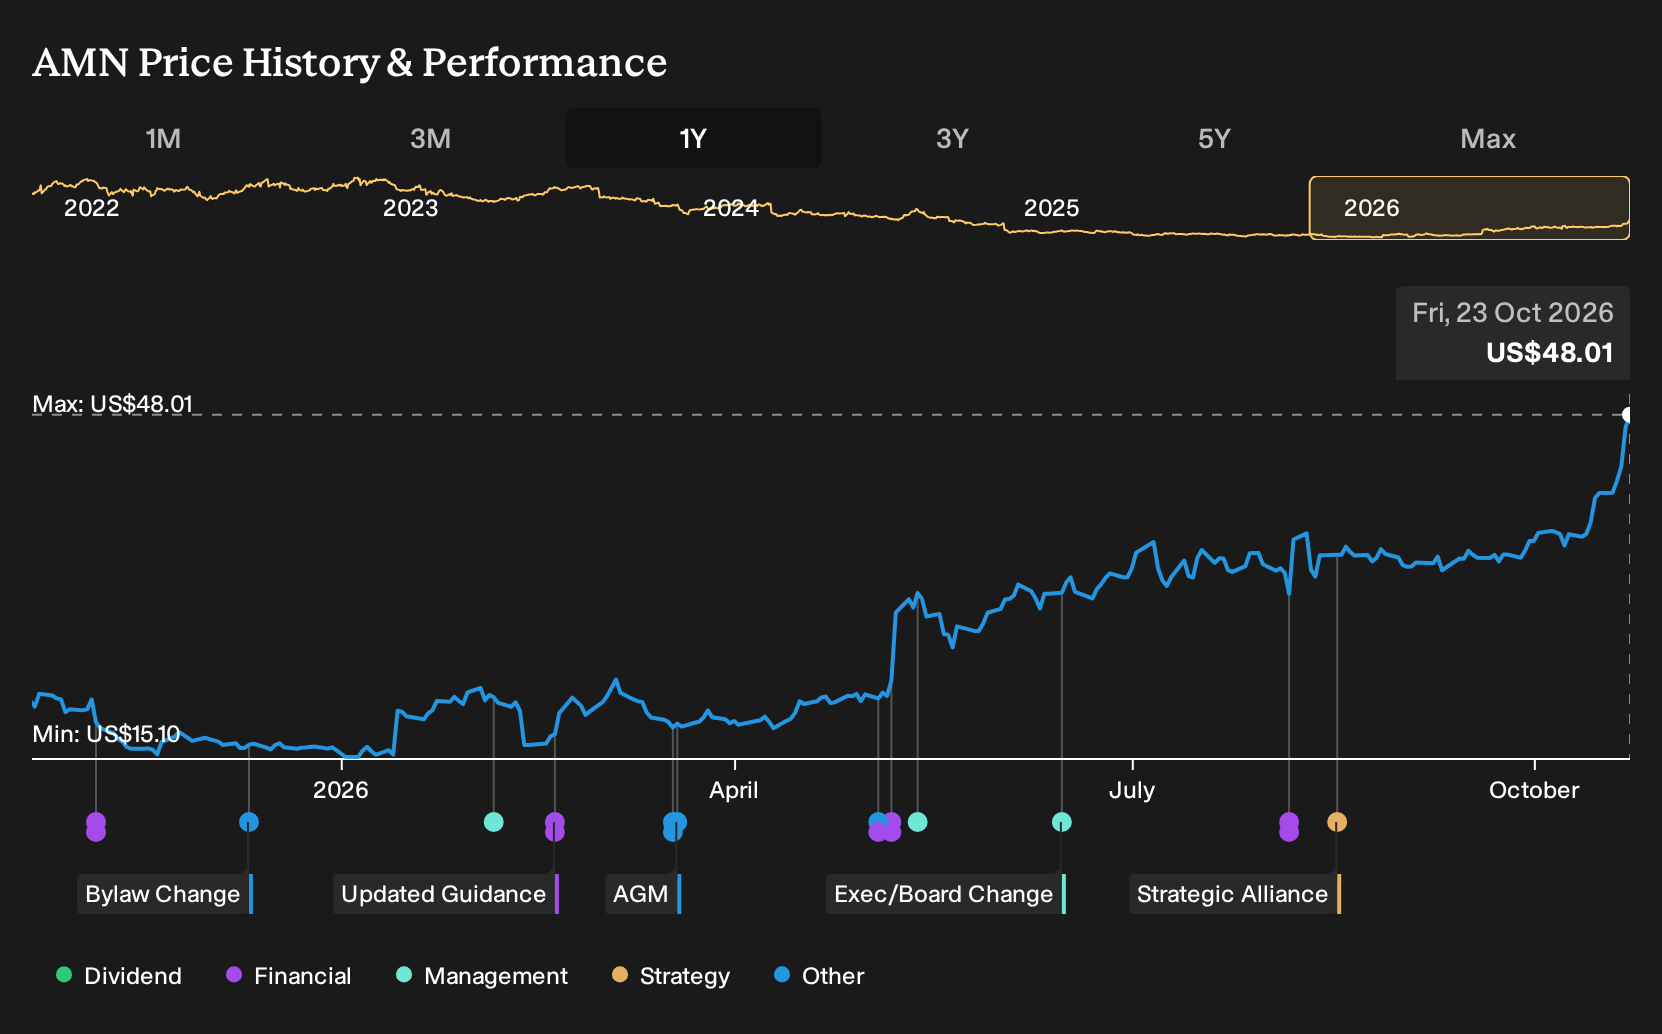
The clearest operational marker linked to this news is the second quarter 2026 result that returned AMN Healthcare Services to profitability, with US$21.2 million of net income and adjusted EPS of US$0.77. That result relied heavily on labor disruption staffing and stronger travel nurse and allied activity, which helps explain the sharp share price move this year.
This rebound in earnings matters for the current catalyst because it shows the platform can still convert volume into cash flow, even as some segments such as language services and VMS experience price and volume pressure. The tension for investors is that analysts model declining revenue and earnings, so execution on tech tools, diversification, and strike readiness will likely be watched closely against that cautious outlook.
What The Analyst Framework Implies For AMN Healthcare Services
Analysts are effectively indicating that the recent rebound in AMN Healthcare Services' profits sits against a forecast that both revenue and earnings step down over the next few years. Their models build in revenue declining 11.6% a year, margin compression from 3.1% to 0.1%, and a sharp drop in net income, even as the latest quarter showed the business still turning high strike and travel volumes into cash.
The expectations are specific. Consensus points to earnings today of US$104.9 million moving to US$2.6 million by 2029, with revenue reaching US$2.4b in that same year. That means the analyst playbook is not anchored on the recent quarter continuing at the same clip. It leans on the idea that pricing pressure, mix shifts and more muted demand in some segments win out over labor disruption surges and tech efficiency gains.
The earnings bridge implied here is steep in dollar terms. Forecast profit of US$2.6 million in 2029 would be US$102.3 million lower than current earnings of US$104.9 million, even before you factor in the disagreement between the most optimistic and most cautious estimates. On the revenue side, the assumed 11.6% yearly decline bakes in a very different trajectory from the recent strike heavy quarter. This is why it is worth asking how much of that drop you think is realistic given your own read of hospital staffing behavior.
Layered on top of those operational assumptions sits the valuation math. To reconcile a price target of US$36.14 per share with earnings of US$2.6 million in 2029, the models use a P/E multiple of 697.5x versus about 13.5x today and a discount rate of roughly 7.6%. That gap between the current and implied future multiple is very large. It shows that a significant part of the story is about what investors might be willing to pay for each dollar of profit rather than just what the income statement delivers.
AMN Healthcare Services' narrative projects revenue of US$2.4b and earnings of US$2.6 million by 2029. This requires 11.6% yearly revenue decline and an earnings decrease of US$102.3 million from current earnings of US$104.9 million.
Uncover why AMN Healthcare Services' fair value indicates a 25% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate take focuses on AMN Healthcare Services’ Technology and Workforce Solutions weakness. Before this earnings surprise, the most pessimistic analysts were penciling in roughly 10.8% annual revenue declines and only US$153.0 million of 2029 earnings on a lower 9.0x P/E. That view could shift if you think this quarter hints at better tech monetization ahead.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AMN Healthcare Services research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AMN Healthcare Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMN Healthcare Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond AMN Healthcare Services?
If this earnings story has you rethinking how you build a portfolio, it can help to scan a broader set of opportunities and compare AMN Healthcare Services with companies that have different risk and income profiles.
- For investors who care most about resilience, start with a 30 resilient stocks with low risk scores that may help you focus on businesses with steadier fundamentals.
- If you are hunting for reliable income, filter for companies offering consistent payouts through a curated set of 5 dividend fortresses that could fit a yield focused approach.
- When you want solid financial footing to be non negotiable, narrow your search to a list of solid balance sheet and fundamentals (24 results) that can help surface companies with stronger balance sheets and underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com