


EN
Kier Group (LSE:KIE) Eyes AMP8 Water Spend, Is The Stock Fully Priced?
Leadership moves and water sector positioning
Kier Group (LSE:KIE) has been in focus after fresh commentary on its role in the AMP8 water investment programme, as the UK prepares for heavier spend on aging, regulated infrastructure.
Alongside that sector backdrop, the contractor has reshaped parts of its senior team. The latest move is the promotion of Sam Kay to deputy company secretary and Group legal director for central functions.
The Kier Group share price at £3.064 has been on a strong run, with a 26.19% 90 day share price return and a 41.52% year to date share price return. The 3 year total shareholder return of 236.03% signals powerful longer term momentum.
Scan beyond Kier Group and line up other contractors with similar infrastructure and water exposure using our curated list of 42 power grid technology and infrastructure stocks.
That surge in Kier Group shares could signal that investors are simply re-rating sentiment around UK infrastructure, or it could be catching up with shifts in the underlying business. The valuation now needs a closer look.
Most Popular Narrative: 12% Undervalued
The most followed narrative on Kier Group pegs fair value at about £3.49 per share, compared with the latest close at £3.064, which frames the recent share price strength against a still supportive valuation gap.
Kier Group's record order book of £11 billion and its strong multiyear revenue visibility are driven by increasing contract wins, particularly in infrastructure. This is likely to enhance future revenue growth.
See why 23 investors see Kier Group as 12% undervalued.
Result: Fair Value of £3.49 (UNDERVALUED)
Still, delays to programmes like CP7 or RIS 3, and any shift in U.K. government spending priorities, could quickly challenge the Kier Group re‑rating narrative.
Find out about the key risks to this Kier Group narrative.
Another View: Multiples Push Back On The Kier Story
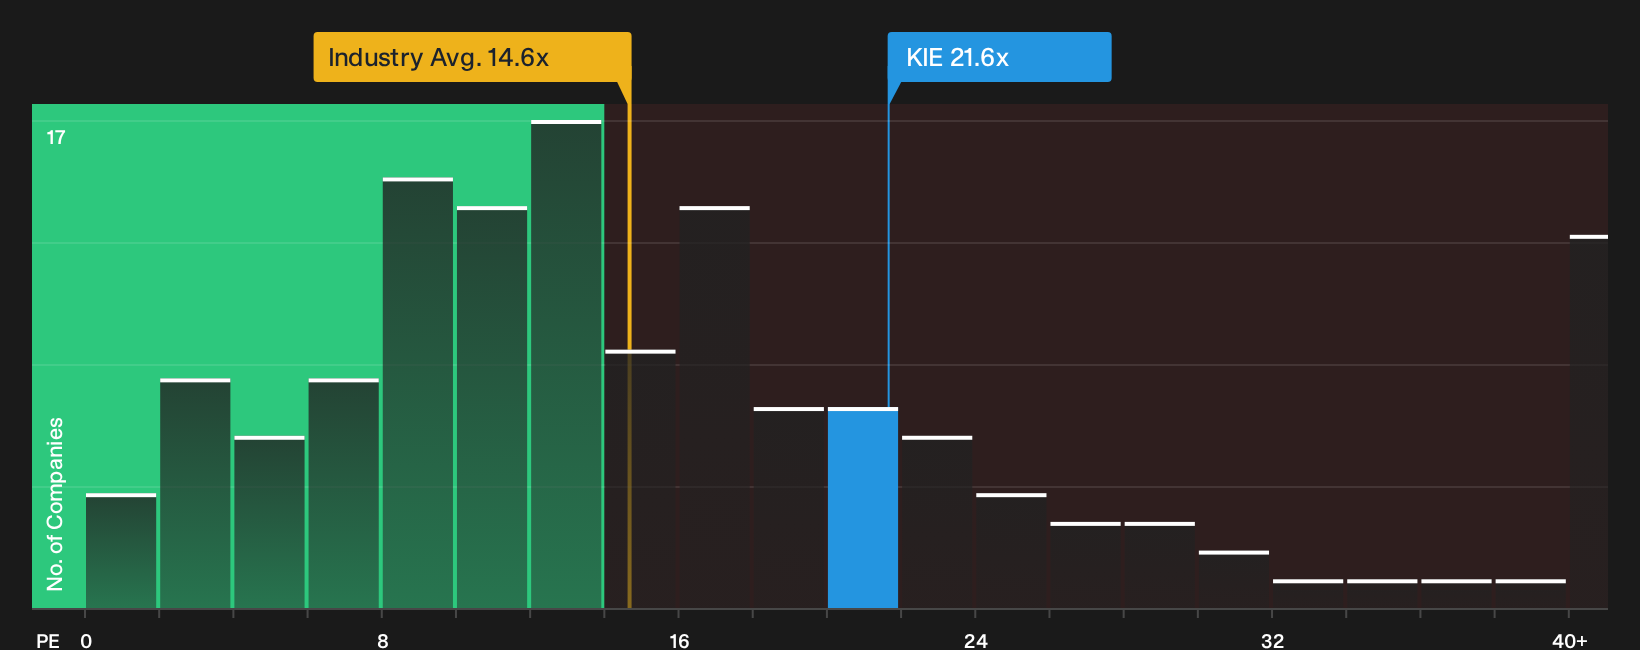
The narrative around Kier Group as 12% undervalued leans heavily on future cash flows and order book comfort. On simple earnings multiples, the picture is less forgiving. The shares trade on a P/E of 21.6x against 14.6x for the European Construction sector and 14x for direct peers.
The fair ratio is 22.7x, only slightly above the current 21.6x. That small gap points to limited room for error. If sentiment or earnings expectations cool, the premium multiple could unwind faster than any slow grind in fair value. Is this a margin of safety or just a thin cushion?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Kier Group leave you undecided, that is the point. Act while sentiment is split and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kier Group?
Use this moment to widen your watchlist, stress test your thesis, and uncover new angles before the next wave of infrastructure stories pulls attention elsewhere.
Right now is when you want to line up alternatives, compare quality, and spot mispriced potential before the crowd moves in and narrows the opportunity set.
- Target potential upside in quality at a discount by scanning a curated set of 8 high quality undervalued stocks that may merit a closer look beside Kier Group.
- Protect your downside first by focusing on resilience through a 4 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier profiles.
- Hunt for tomorrow's potential leaders before they are widely followed by running through a 5 high quality undiscovered gems that highlights under-the-radar companies with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com