


EN
TGS (OB:TGS) Reports Record Backlog, Is The Upside Already Priced In?
TGS (OB:TGS) drew fresh attention after its Q3 2026 update, which paired margin pressure from higher costs with resilient sales, a record streamer backlog, and indications of firm demand into 2027.
At a share price of NOK136.9, TGS has given investors a 45.64% year to date share price return and a 63.06% total shareholder return over the past year, suggesting momentum is still building despite a 4.67% share price pullback over the past month as the market digests the Q3 earnings along with the fresh Pelotas Sul survey and dividend announcements.
Scan for other energy and geoscience plays showing similar backlog strength and earnings momentum with our hand picked 194 high quality undervalued stocks.
The recent swing in TGS, with a strong year yet a softer month, leaves a simple tension: Are you paying for a temporarily crowded trade or for a business whose backlog and earnings profile still look mispriced?
Most Popular Narrative: 7% Undervalued
The most followed narrative pegs TGS at a fair value of NOK146.65, slightly above the NOK136.9 last close. This frames today’s price as modestly discounted rather than exuberant.
The company is expanding its dataset coverage in high-potential regions such as Brazil's Equatorial Margin, Argentina's Malvinas, and the Gulf of Mexico. This positions it to benefit from frontier exploration trends as supermajors invest in securing future energy supplies, which may support top-line growth and library value realization. Active cost optimization, including vessel sales, capacity reductions, and integration synergies, has coincided with improved EBITDA margins despite revenue softness and is expected to further lift net margins and earnings if market conditions normalize.
See why 11 investors see TGS as 7% undervalued.
Result: Fair Value of NOK146.65 (UNDERVALUED)
Still, if oil and gas spending underwhelms or large customers delay big library purchases, the upbeat TGS valuation narrative could quickly feel stretched.
Find out about the key risks to this TGS narrative.
Another View: What TGS’s P/E Is Telling You
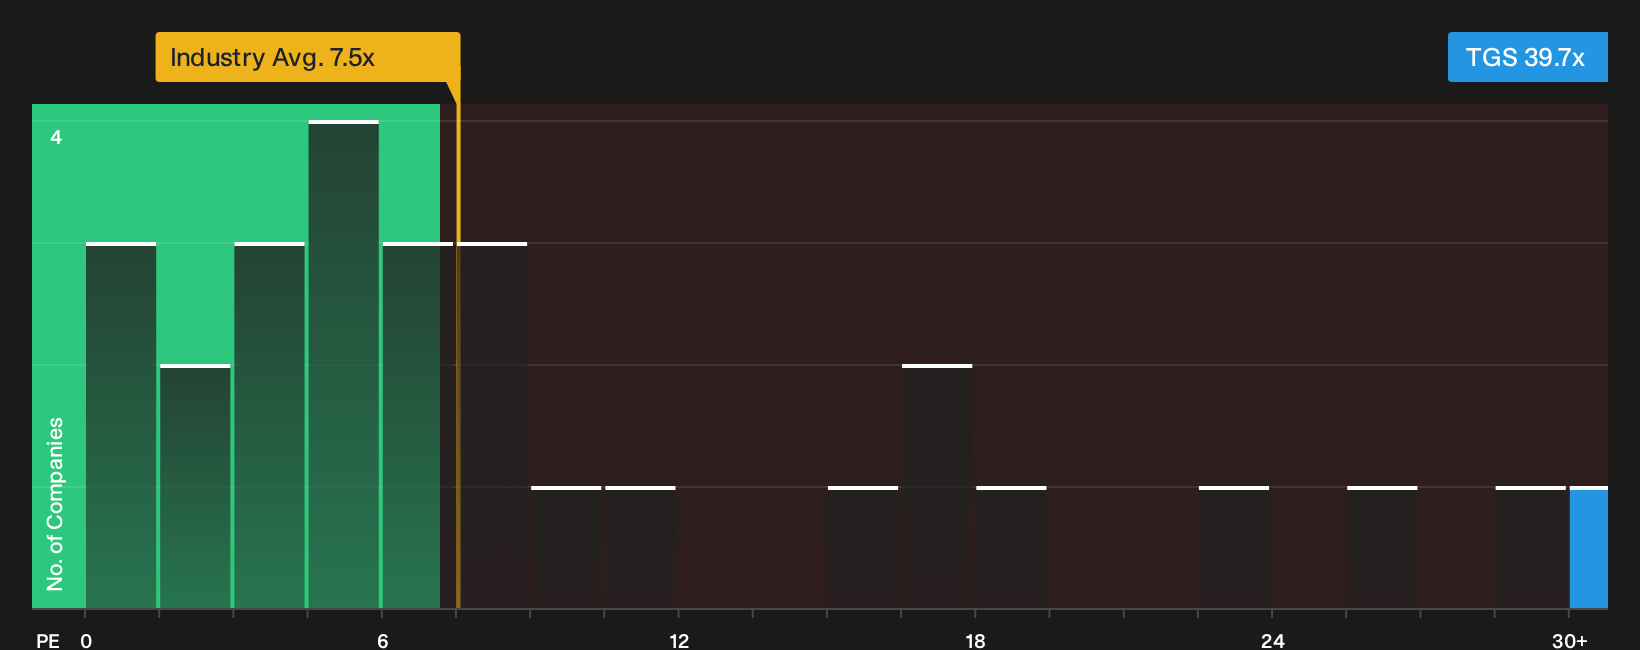
The fair value narrative paints TGS as modestly mispriced. The P/E ratio tells a tougher story. At 39.7x earnings, the stock trades far above the Norwegian Energy Services industry on 7.5x and peers on 8.7x, and above a fair ratio of 22.4x that the market could drift toward.
If that gap closes through a lower multiple rather than higher earnings, investors are dealing less with a quiet bargain and more with clear valuation risk. Which outcome do you think is more realistic for your time horizon?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around TGS do not need to leave you on the fence, especially when fresh information is still being digested by the market. Move quickly, check both sides of the story, and weigh the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond TGS?
If you liked weighing both sides of TGS, do not stop there. Broaden your watchlist with a few focused hunting grounds built from hard numbers.
- Target potential mispricing by scanning companies that combine quality fundamentals with beaten down expectations through our 194 high quality undervalued stocks.
- Strengthen your income stream by reviewing resilient payers with consistent cash support using the 226 dividend fortresses.
- Dial down portfolio stress by filtering for businesses that carry resilient balance sheets and robust fundamentals inside the list of solid balance sheet and fundamentals (205 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com