


EN
HMS Networks (OM:HMS) Reports Higher Sales, Is The Pullback A Valuation Reset?
HMS Networks (OM:HMS) entered the spotlight after its latest earnings release, reporting third quarter sales of SEK 1,024 million and flat quarterly net income, along with stronger nine-month earnings compared with the prior year.
HMS Networks’ recent earnings arrive after a choppy few weeks, with the 7 day share price return down 14.12% and the 30 day move down 12.79%, even though the year to date share price return sits at 19.16% and the 3 year total shareholder return is 30.63%.
Scan other industrial automation and connectivity stocks that show similar earnings momentum and recent share price swings using our hand picked 95 robotics and automation stocks for your next round of ideas.
The recent pullback in HMS Networks after reporting higher sales but flat quarterly profit raises a simple issue. Are you seeing cracks in the business, or just a reset in sentiment that changes the valuation maths?
Most Popular Narrative: 18% Undervalued
HMS Networks closed at SEK478.80 against a widely followed fair value view of SEK586.80. The current slide is being weighed against a narrative that still sees upside based on earnings power rather than short term sentiment.
The recent restructuring into three divisions with full accountability for R&D, sales, and marketing could lead to increased operational efficiency and improved sales strategies, potentially boosting revenue and net margins. The integration of recent acquisitions, such as Red Lion and PEAK-System, is performing well, which could enhance earnings through increased market share and synergies, particularly impacting earnings positively as these acquisitions integrate and contribute to the bottom line.
See why 4 investors see HMS Networks as 18% undervalued.
Result: Fair Value of SEK586.80 (UNDERVALUED)
Still, a 17% decline in organic sales and tariff related cost pressure could quickly challenge the HMS Networks margin story that underpins this fair value gap.
Find out about the key risks to this HMS Networks narrative.
Another View On HMS Networks’ Valuation
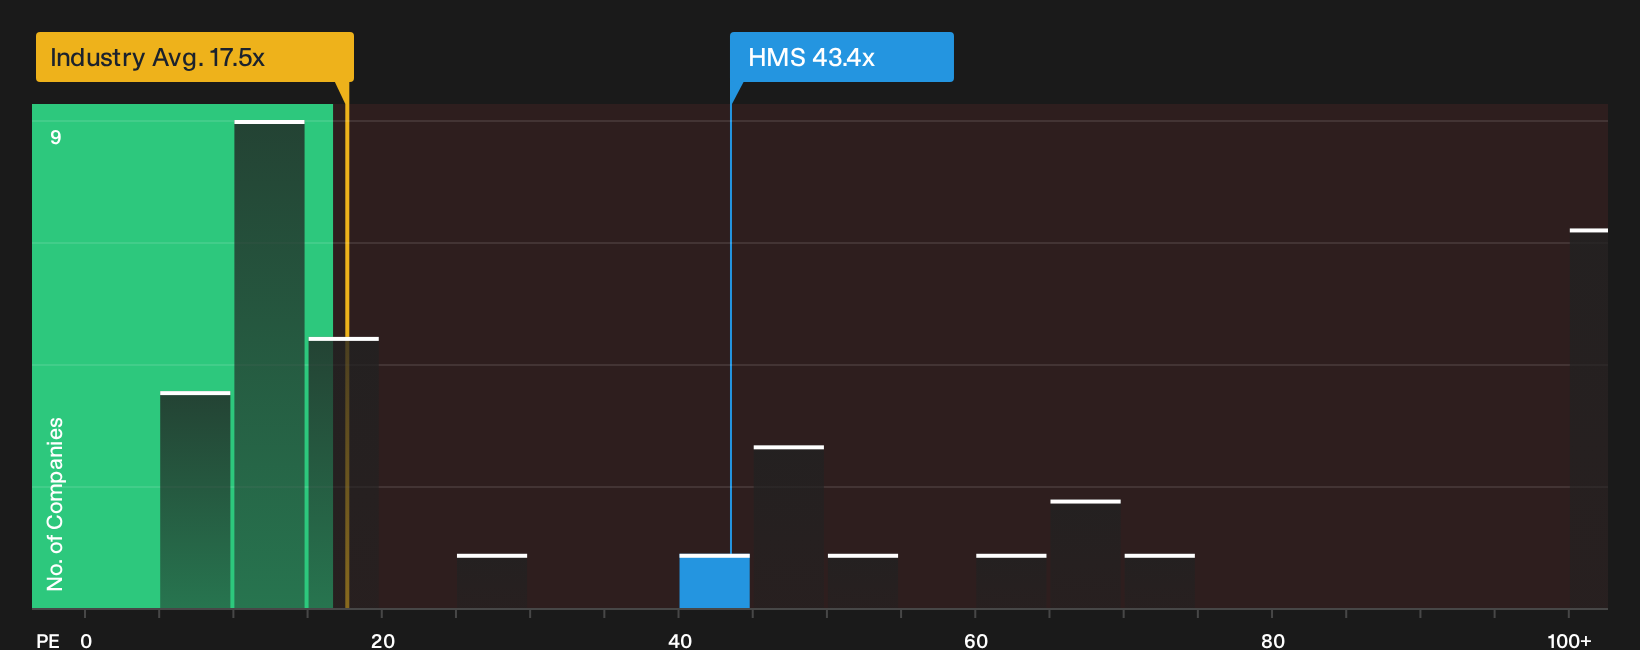
The fair value story around SEK586.80 leans heavily on earnings power. Step back and the picture looks different. HMS Networks trades on a P/E of 43.4x versus 17.5x for the European Communications sector and a fair ratio of 27.9x, which points to a richer pricing that may compress if sentiment cools.
That gap between today’s multiple, peers, and the fair ratio raises a simple question for anyone following HMS Networks. Are you comfortable paying a premium that assumes the upbeat narrative plays out cleanly, or do you see more room for disappointment than the current price implies?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on HMS Networks so far. Act quickly and review the full breakdown of both the upside drivers and downside flags in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond HMS Networks?
Do not stop your research with HMS Networks. A few minutes spent scanning broader opportunities today could shape the ideas you act on next quarter.
- Target higher quality potential by focusing on resilient balance sheets through our curated list of solid balance sheet and fundamentals (205 results) that highlights companies with stronger financial footing.
- Hunt for mispriced opportunities by using the 613 high quality undiscovered gems to spot lesser known businesses with solid fundamentals that the market may be overlooking.
- Prioritise capital preservation by filtering for steadier profiles via the 221 resilient stocks with low risk scores so you are not only chasing upside but managing downside as well.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com