


EN
Saia (SAIA) Opens Deer Park Terminal On An Undervalued Narrative
Saia (SAIA) just put a new pin in its map by opening a Deer Park terminal on Long Island that widens coverage across the greater New York metro freight market.
Recent trading has been choppy for Saia, with the share price down 3.59% on the day and 20.90% over the past 90 days, even as the 1 year total shareholder return of 14.47% stays positive. The Deer Park terminal opening fits into that picture, as investors weigh near term execution risk on network investments against the longer term potential for more efficient coverage in dense freight markets.
Spot similar freight carriers building out their networks and capacity plays by scanning the hand picked list of solid balance sheet and fundamentals (24 results).Saia is pouring capital into dense freight markets just as the share price has cooled off. Is the real upside still ahead, or did most of it arrive before Deer Park opened?
Most Popular Narrative: 21% Undervalued
Saia's most followed valuation storyline pegs fair value at $420.29 per share, above the last close of $332.14. This places real weight on what its expanded network can earn over time.
The ongoing expansion and maturation of Saia's national terminal network, combined with densification of the 218 plus facilities added or upgraded since 2022, is still early in its ramp and is beginning to show operating ratio improvement at newer sites. This could support higher shipment volumes, revenue growth and better net margins as more terminals move from the low 90s operating ratio toward mature system levels.
See why 4 investors see Saia as 21% undervalued.
Result: Fair Value of $420.29 (UNDERVALUED)
Still, that 49.6% jump in Q2 2026 fuel expense and double digit wage and benefits pressure leave Saia exposed if pricing and efficiency gains fall short.
Find out about the key risks to this Saia narrative.
Another View: Saia Through A Cash Flow Lens
The first storyline leans on analyst fair value of $420.29, yet the SWS DCF model paints a very different picture. On that cash flow view, Saia at $332.14 trades well above an estimated future cash flow value of $146.41, which screens as expensive rather than undervalued. Which set of assumptions do you find more realistic?
Look into how the SWS DCF model arrives at its fair value.
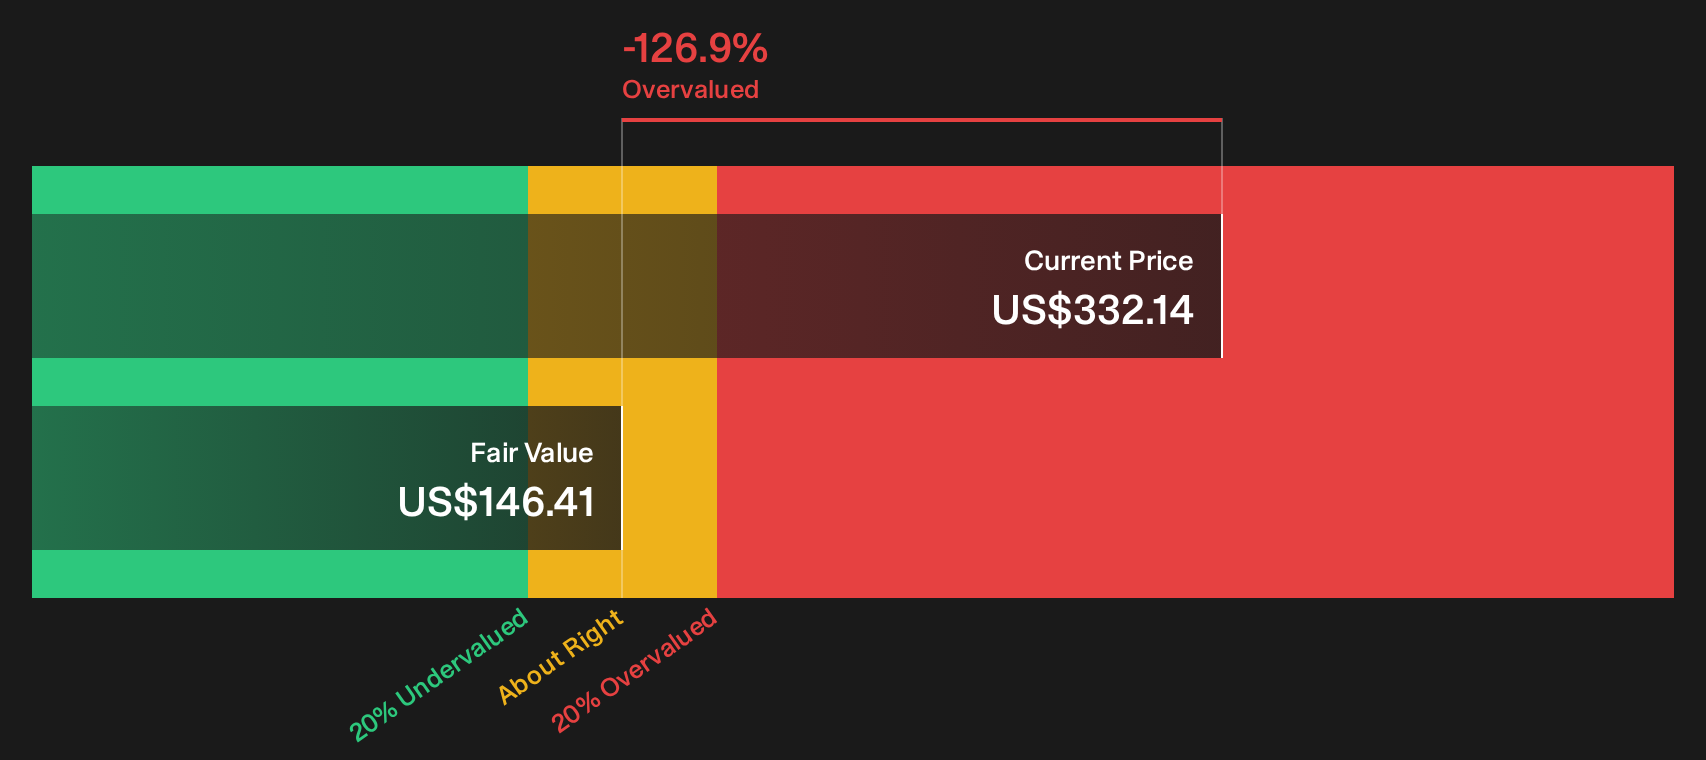
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Saia is split, which is exactly when fresh data helps most. Move quickly and pressure test the upside case by checking the 2 key rewards.
Looking for more investment ideas beyond Saia?
If Saia has you thinking about where capital could work harder next, it makes sense to widen the lens with a curated set of alternative ideas.
- Target resilient compounding potential by scanning a 30 resilient stocks with low risk scores that filters for businesses built to handle shocks without exposing your portfolio to excessive risk.
- Hunt for mispriced opportunity by reviewing a 21 high quality undiscovered gems that surfaces fundamentally strong companies sitting off most investors' radar.
- Boost income potential by assessing a 5 dividend fortresses focused on high yielding payers that still show financial strength behind those distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com