


EN
Should Earnings Beat Require Action From KeyCorp (KEY) Investors?
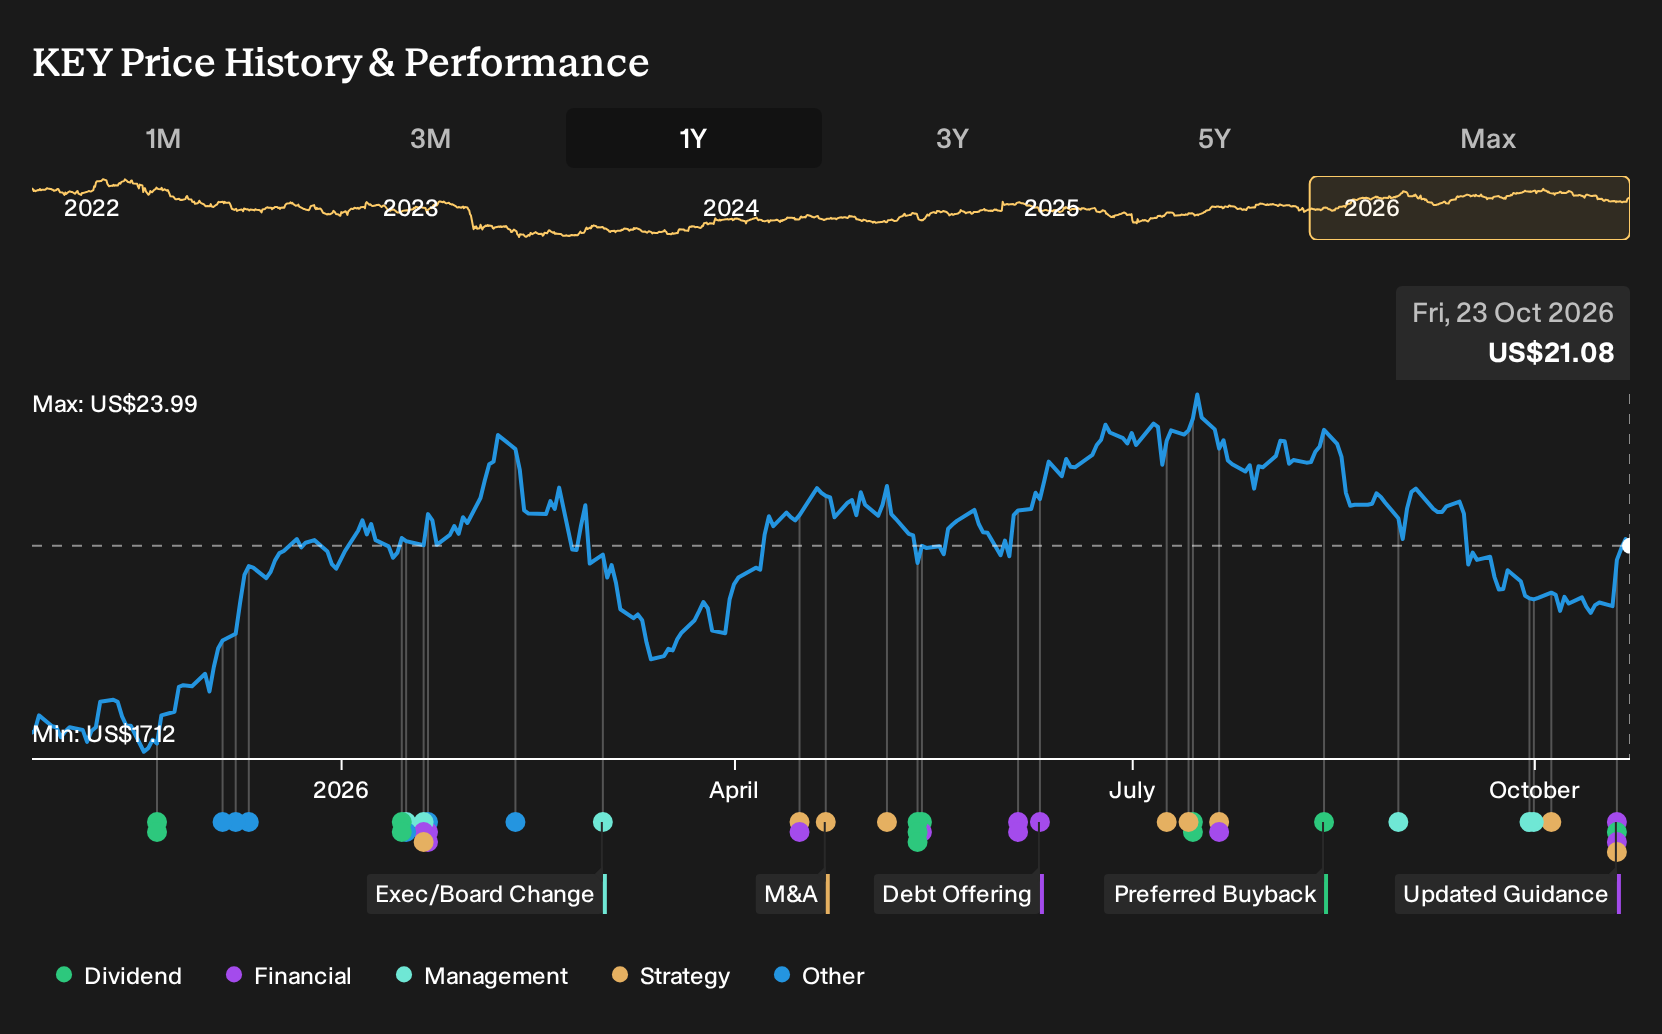
- KeyCorp reported third quarter 2026 results with higher year over year net interest income of US$1,300 million and net income of US$579 million, updated full year 2026 net interest income guidance to about 10% growth, adjusted preferred dividend plans, and completed a US$542.07 million share repurchase program.
- The mix of earnings progress, lower net loan charge offs of US$89 million, and capital actions focused on preferred dividends and buybacks provides insight into how KeyCorp is seeking to fine tune returns while managing funding costs.
- Investors can now assess how KeyCorp's tighter 2026 net interest income guidance could affect the investment narrative that existed before this update.
Scan how KeyCorp's capital moves compare with a hand picked group of banks and lenders with stronger balance sheets in our list of solid balance sheet and fundamentals (24 results).
KeyCorp Investment Narrative Recap
To own KeyCorp, you need to be comfortable with a story built on net interest income, deposit mix and fee growth from wealth, payments and advisory. The tighter 2026 net interest income outlook around 10% growth keeps that thesis intact. The short term swing factor is still how quickly asset repricing and deposit costs support earnings.
The biggest watchpoint remains credit quality after earlier nonperforming asset increases, even though recent net loan charge offs were US$89 million compared with US$114 million a year ago. If credit trends worsen broadly, it would challenge the idea that higher net interest income and fee growth can consistently support returns.
The clearest link to this story is the updated 2026 net interest income guidance at about 10% growth, framed alongside commercial loan momentum and preferred capital decisions that are described as accretive to earnings per share and returns but slightly dilutive to net interest margin. That matters more than headline dividend tweaks.
For investors, this guidance update sets a reference point to judge execution on repricing over US$9 billion of low yielding assets and improving deposit costs. It also connects to capital plans such as buybacks and preferred optimization that analysts tie to earnings per share and return metrics, while leaving credit costs and fee volatility as key ongoing risks.
KeyCorp Long Term Consensus Setup
KeyCorp's narrative projects US$9.5 billion revenue and US$2.5 billion earnings by 2029. This implies 8.9% yearly revenue growth and an earnings increase of about US$600 million from US$1.9 billion today.
Uncover how KeyCorp's fair value indicates a 20% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Some of the most optimistic analysts focus on KeyCorp’s capital strength as the real catalyst. Before this news, they were modeling revenue of about US$9.8b and earnings of roughly US$2.7b by 2029. You can now ask whether the updated preferred dividend plans shift that more upbeat storyline or simply refine it.
Explore 2 other KeyCorp fair value estimates, including one that suggests up to 85% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your KeyCorp research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for KeyCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KeyCorp's overall financial health at a glance.
Looking for more investment ideas beyond KeyCorp?
Once you have a view on KeyCorp, it can help to line that thesis up against other opportunities that fit different risk and return profiles. The Simply Wall St Screener is built for exactly that comparison, letting you move from a single ticker to a curated watchlist in a few minutes.
- If you want to focus on potential mispricings, start with companies that combine quality fundamentals with attractive valuations through our 29 high quality undervalued stocks.
- For income focused portfolios, shortlist businesses with higher yields using the 5 dividend fortresses and see how their payouts line up with your KeyCorp view.
- When capital preservation matters more than upside, narrow your watchlist to companies with stronger balance sheets and steadier metrics using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com