


EN
Intercontinental Exchange (ICE) Extends Risk Model As Undervalued Narrative Stays In Play
Intercontinental Exchange (ICE) has further integrated its ICE Risk Model 2 into interest rate and fixed income derivatives, while also expanding access to ICE Connect Wealth through TradePMR’s advisor platform, enhancing the group’s risk and data toolkit.
The latest product rollouts are landing against a backdrop where Intercontinental Exchange’s share price has climbed 5.46% over the past 30 days and 9.42% over the last 90 days. The 3 year total shareholder return of 61.32% and 5 year total shareholder return of 25.53% point to momentum that long term holders will compare with today’s US$162.74 entry point and shifting views on how much growth and risk is already reflected in the valuation.
Compare how Intercontinental Exchange stacks up against other market infrastructure and data businesses by running your own filters across the 30 resilient stocks with low risk scores.
Intercontinental Exchange appears to be a high quality operator with meaningful data and trading franchises, and the recent share price climb reflects that. The next step is working out whether US$162.74 already captures that strength.
Most Popular Narrative: 13% Undervalued
Intercontinental Exchange is trading at $162.74, while the most followed narrative anchors fair value at about $187.29. This frames the recent share price strength as only a partial re-rating of the story.
The main thing that has to go right is that Intercontinental Exchange successfully executes its higher spending on data centers, AI hardware, and product development so that rising operating expenses and CapEx translate into sustained growth in fixed income, data services, and mortgage technology.
The planned acquisition of MarketAxess and the build out of a combined electronic network for fixed income and private credit, including the new private credit reference data service, create scope to broaden execution and data fees across credit markets and to support recurring revenue and margin expansion over time.
See why 40 investors see Intercontinental Exchange as 13% undervalued.
Result: Fair Value of $187.29 (UNDERVALUED)
Still, this narrative can unwind quickly if ICE’s heavier spending on data centers fails to lift recurring revenue, or if the MarketAxess deal complicates integration and leverage.
Find out about the key risks to this Intercontinental Exchange narrative.
Another View On Intercontinental Exchange’s Valuation
The analyst-led narrative sees Intercontinental Exchange as about 13% undervalued at a fair value of $187.29. A different lens, the Simply Wall St DCF model, points the other way, with an estimate of future cash flow value at $151.89, which frames the current $162.74 price as expensive. Which story do you think fits the risks and cash generation better?
Look into how the SWS DCF model arrives at its fair value.
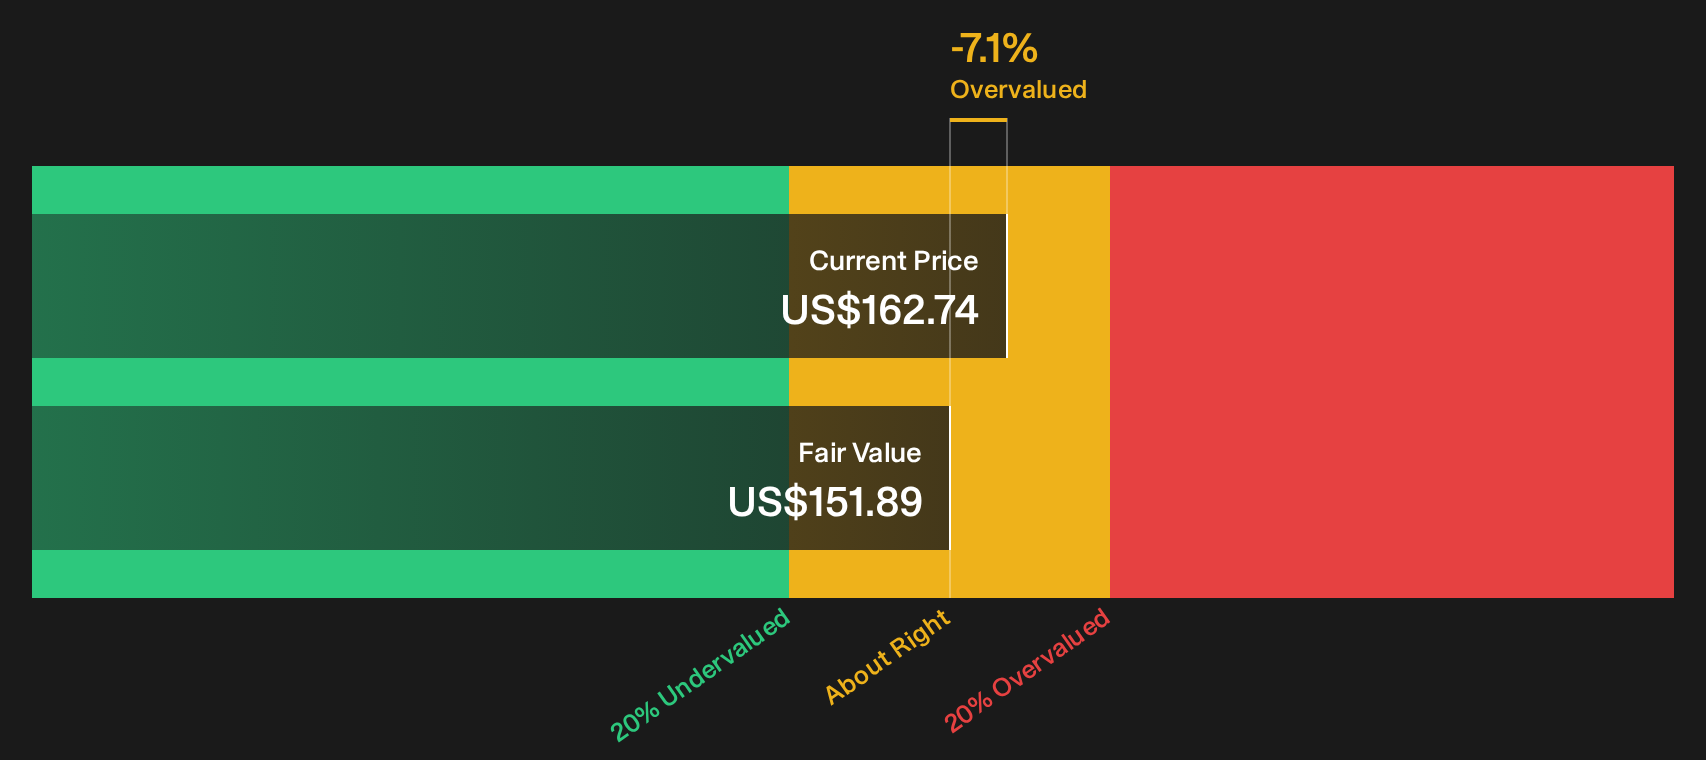
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intercontinental Exchange for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of optimism runs through this Intercontinental Exchange story, but the mix of risks and rewards is what really matters. Move quickly and test the data against your own expectations using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Intercontinental Exchange?
If you stop with Intercontinental Exchange, you only see one angle. Broaden your watchlist now and pressure test your thesis against fresh, data driven opportunities.
- Target resilient wealth builders by scanning for sturdy cash flows and attractive entry points with the 29 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that pair higher yields with durability through the 5 dividend fortresses.
- Prioritise staying power by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com