


EN
3 British Undervalued Stocks Trading Up To 49% Below Fair Value
With the UK government preparing a Budget that channels more than £1b into social and affordable housing, long term capital is being steered toward real economic projects rather than short term financial engineering. That kind of backdrop often rewards companies with solid cash generation. This article highlights three UK-listed stocks that our cash flow focused screen flags as trading below estimated fair value, so you can judge whether any deserve a place on your watchlist.
The three stocks covered next are just a sample set. The full cash flow screen surfaced 28 more UK listed companies with similarly interesting stories that are not unpacked in this article.
If you want to identify and analyze those extra opportunities side by side, head straight to the Undervalued Stocks Based On Cash Flows screener.
Shell (LSE:SHEL)
Overview: Shell is a global energy group whose oil, gas and LNG production underpins large, contract-backed cash flows, complemented by chemicals, retail and renewables.
Operations: Shell generates most revenue from Marketing at about $135b and Chemicals and Products at about $132b, with Integrated Gas and Upstream adding around $93b.
Market Cap: £230.2b
Shell matters for this cash flow focused screen because its oil, gas and LNG engine throws off substantial contractual cash, which supports discounted cash flow based valuation work for value driven investors.
"Shell's renewable energy management agreement with Google in the UK is concrete evidence of this strategy."
What happens to Shell’s cash return profile if a single key assumption around long term LNG pricing and margins shifts meaningfully?
If that LNG swing factor is central to your thesis, read the full narrative for Shell to see how Shell’s cash returns could accelerate or stall under different paths.
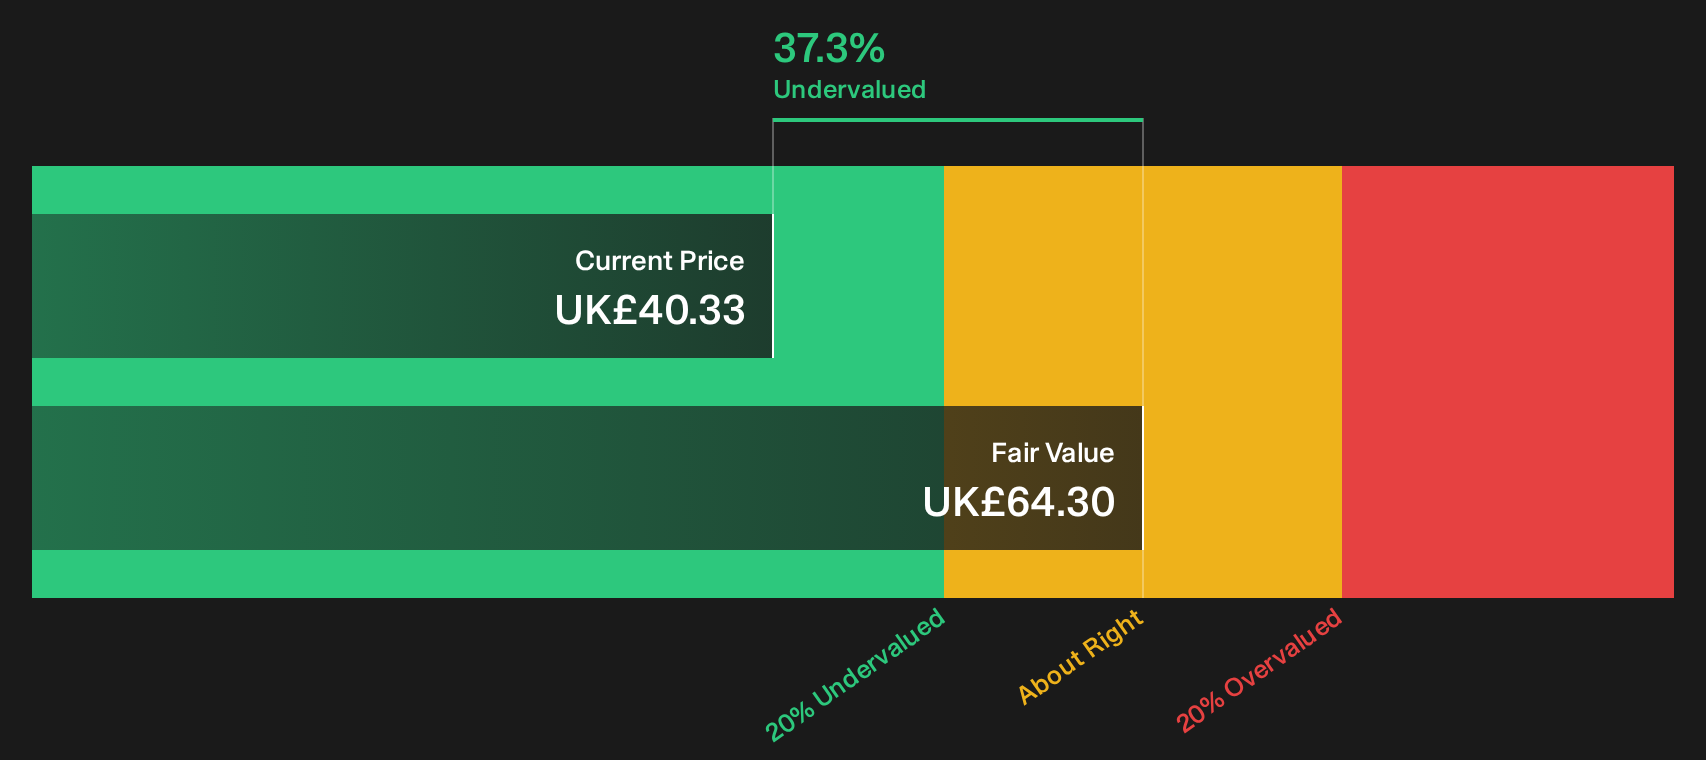
Balfour Beatty (LSE:BBY)
Overview: Balfour Beatty builds, maintains, and invests in large infrastructure projects, with its concession portfolio generating long term contracted cash flows.
Operations: The group earns about £8.0b from Construction Services, £1.5b from Support Services, and £470m from Infrastructure Investments, mainly across the US and UK.
Market Cap: £3.9b
Balfour Beatty matters for a cash flow focused watchlist because those long duration concessions link directly to predictable payments rather than one off project wins. This provides the kind of visibility that can support a discounted cash flow based undervaluation case.
"That positions the company well to profit from the Labour government's initiative for growth, the related, mooted slashing of planning and building regulations in particular."
What happens to Balfour Beatty’s cash rich concessions if a single pressure on future project margins quietly shifts against expectations?
If that pressure point on margins is what you care about, read the full narrative for Balfour Beatty to see whether Balfour Beatty’s contracted cash flows are quietly compounding or at risk of stalling.
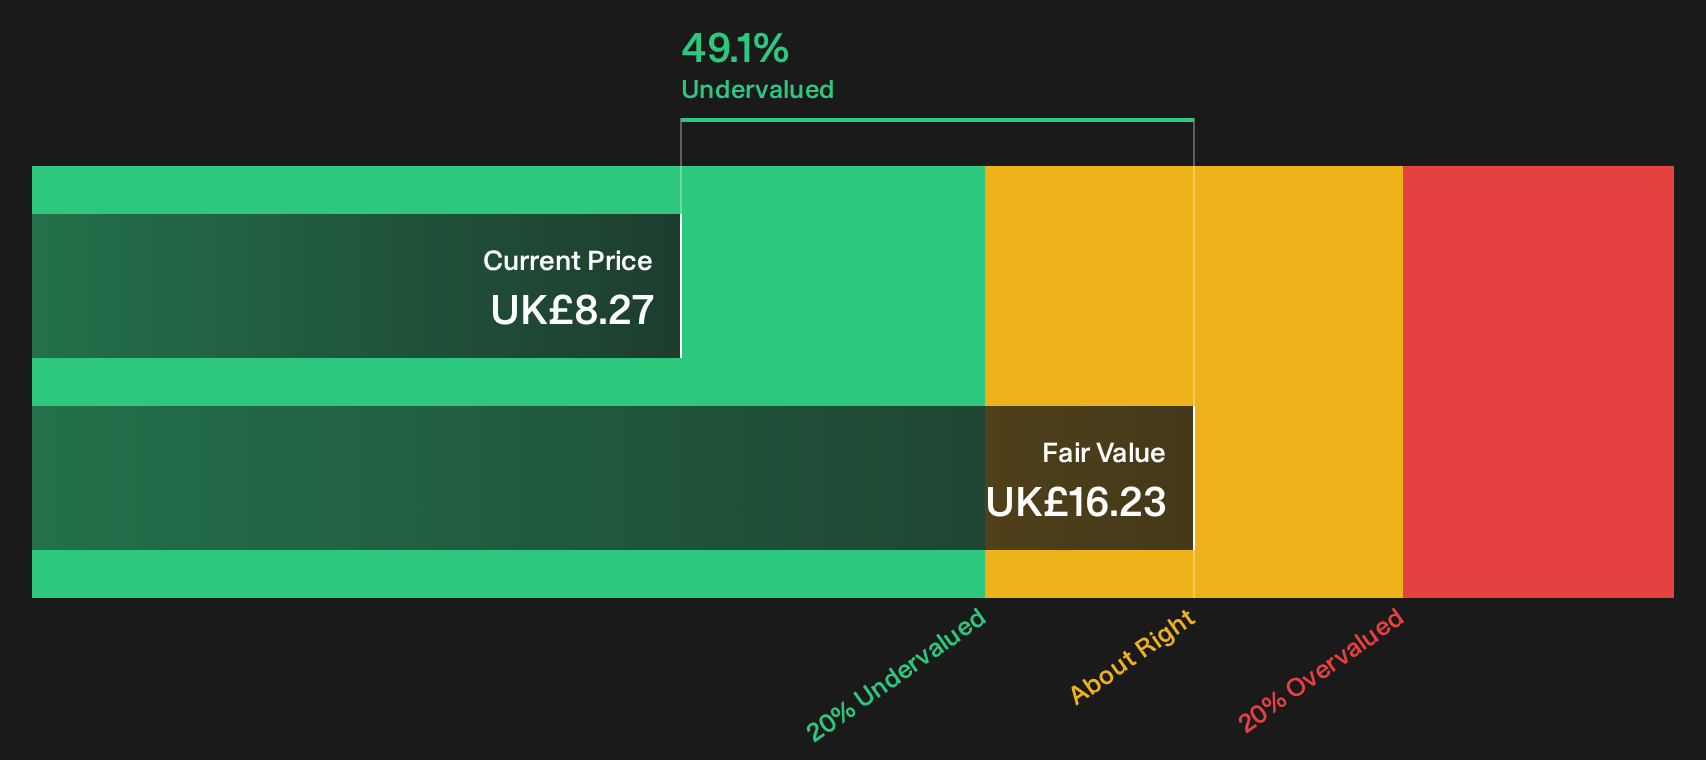
Premier Foods (LSE:PFD)
Overview: Premier Foods manufactures branded and own label ambient grocery and sweet treats, with well known cupboard staples driving steady cash focused sales.
Operations: Premier Foods generates about £860 million from Grocery and £315 million from Sweet Treats, with roughly £1.1 billion coming from UK customers.
Market Cap: £1.7 billion
Premier Foods matters for this cash flow focused screen because its long established ambient brands help turn everyday food purchases into dependable cash generation that can underpin a discounted cash flow valuation.
"Planned step up in annual CapEx to a range of £55 to £60 million in FY27, directed at automated cake lines, insourced sauce capacity, new process plants and energy projects such as efficient boilers and solar arrays, is intended to lower unit costs and improve factory recovery which can support gross margin and trading profit progression."
The real test for Premier Foods now hangs on how one subtle shift in branded mix and pricing power feeds through to future cash returns.
If that mix shift is what you are tracking, read the full narrative for Premier Foods to see whether Premier Foods’ cash engine is quietly accelerating or at risk of stalling.

Curious About What You Might Be Missing?
Fresh ideas move first. Breakout stories, new momentum and under the radar cash generators rarely stay quiet for long. Scan these hand picked lists before the crowd and consider acting while they are still early.
- Identify defensible income streams and use the 5 dividend fortresses to hunt for payouts that could help anchor a diversified portfolio when momentum shifts.
- Look for potential automation leaders at an early stage by scanning the 95 robotics and automation stocks to see which operators already report real contracts and cash flows.
- Monitor infrastructure companies involved in meeting AI demand by reviewing the 55 AI infrastructure stocks while these enablers may still be priced as support players rather than primary drivers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com