


EN
Dell, Lenovo, Cisco, HPE, Supermicro: Why AMD’s New AI Blueprint Has Everyone Signing On
On Oct. 12, Advanced Micro Devices (AMD) announced Helion, an open rack blueprint built on the Open Compute Project for agentic AI infrastructure. I believe this matters to investors looking for the best AI inference stocks over the next five years because it expands AMD’s rack-scale strategy beyond GPUs to include CPUs.
AMD’s CPU-only configuration uses 6th Gen EPYC processors, while the all-in-one version pairs EPYC CPUs with Instinct MI350P GPUs. Dell (DELL), Lenovo (LNVGF), Cisco (CSCO), HPE (HPE), and Supermicro (SMCI) are among the participating partners. The main risk is timing. The configurations are still in development, and their planned November 2026 timing leaves their revenue impact uncertain. However, the company intends to contribute the specification to OCP, which I believe could accelerate adoption. This will directly aid AMD in its growth ambitions.
About AMD
Founded in 1969, AMD began as a small Silicon Valley second-source chipmaker, spent decades battling Intel (INTC) in CPUs, expanded into graphics through ATI, and, under Lisa Su, has evolved into a broad high-performance computing company increasingly positioned as Nvidia’s (NVDA) principal challenger in AI accelerators. The company serves original equipment and design manufacturers, public cloud services providers, system integrators, distributors, and add-in board manufacturers.
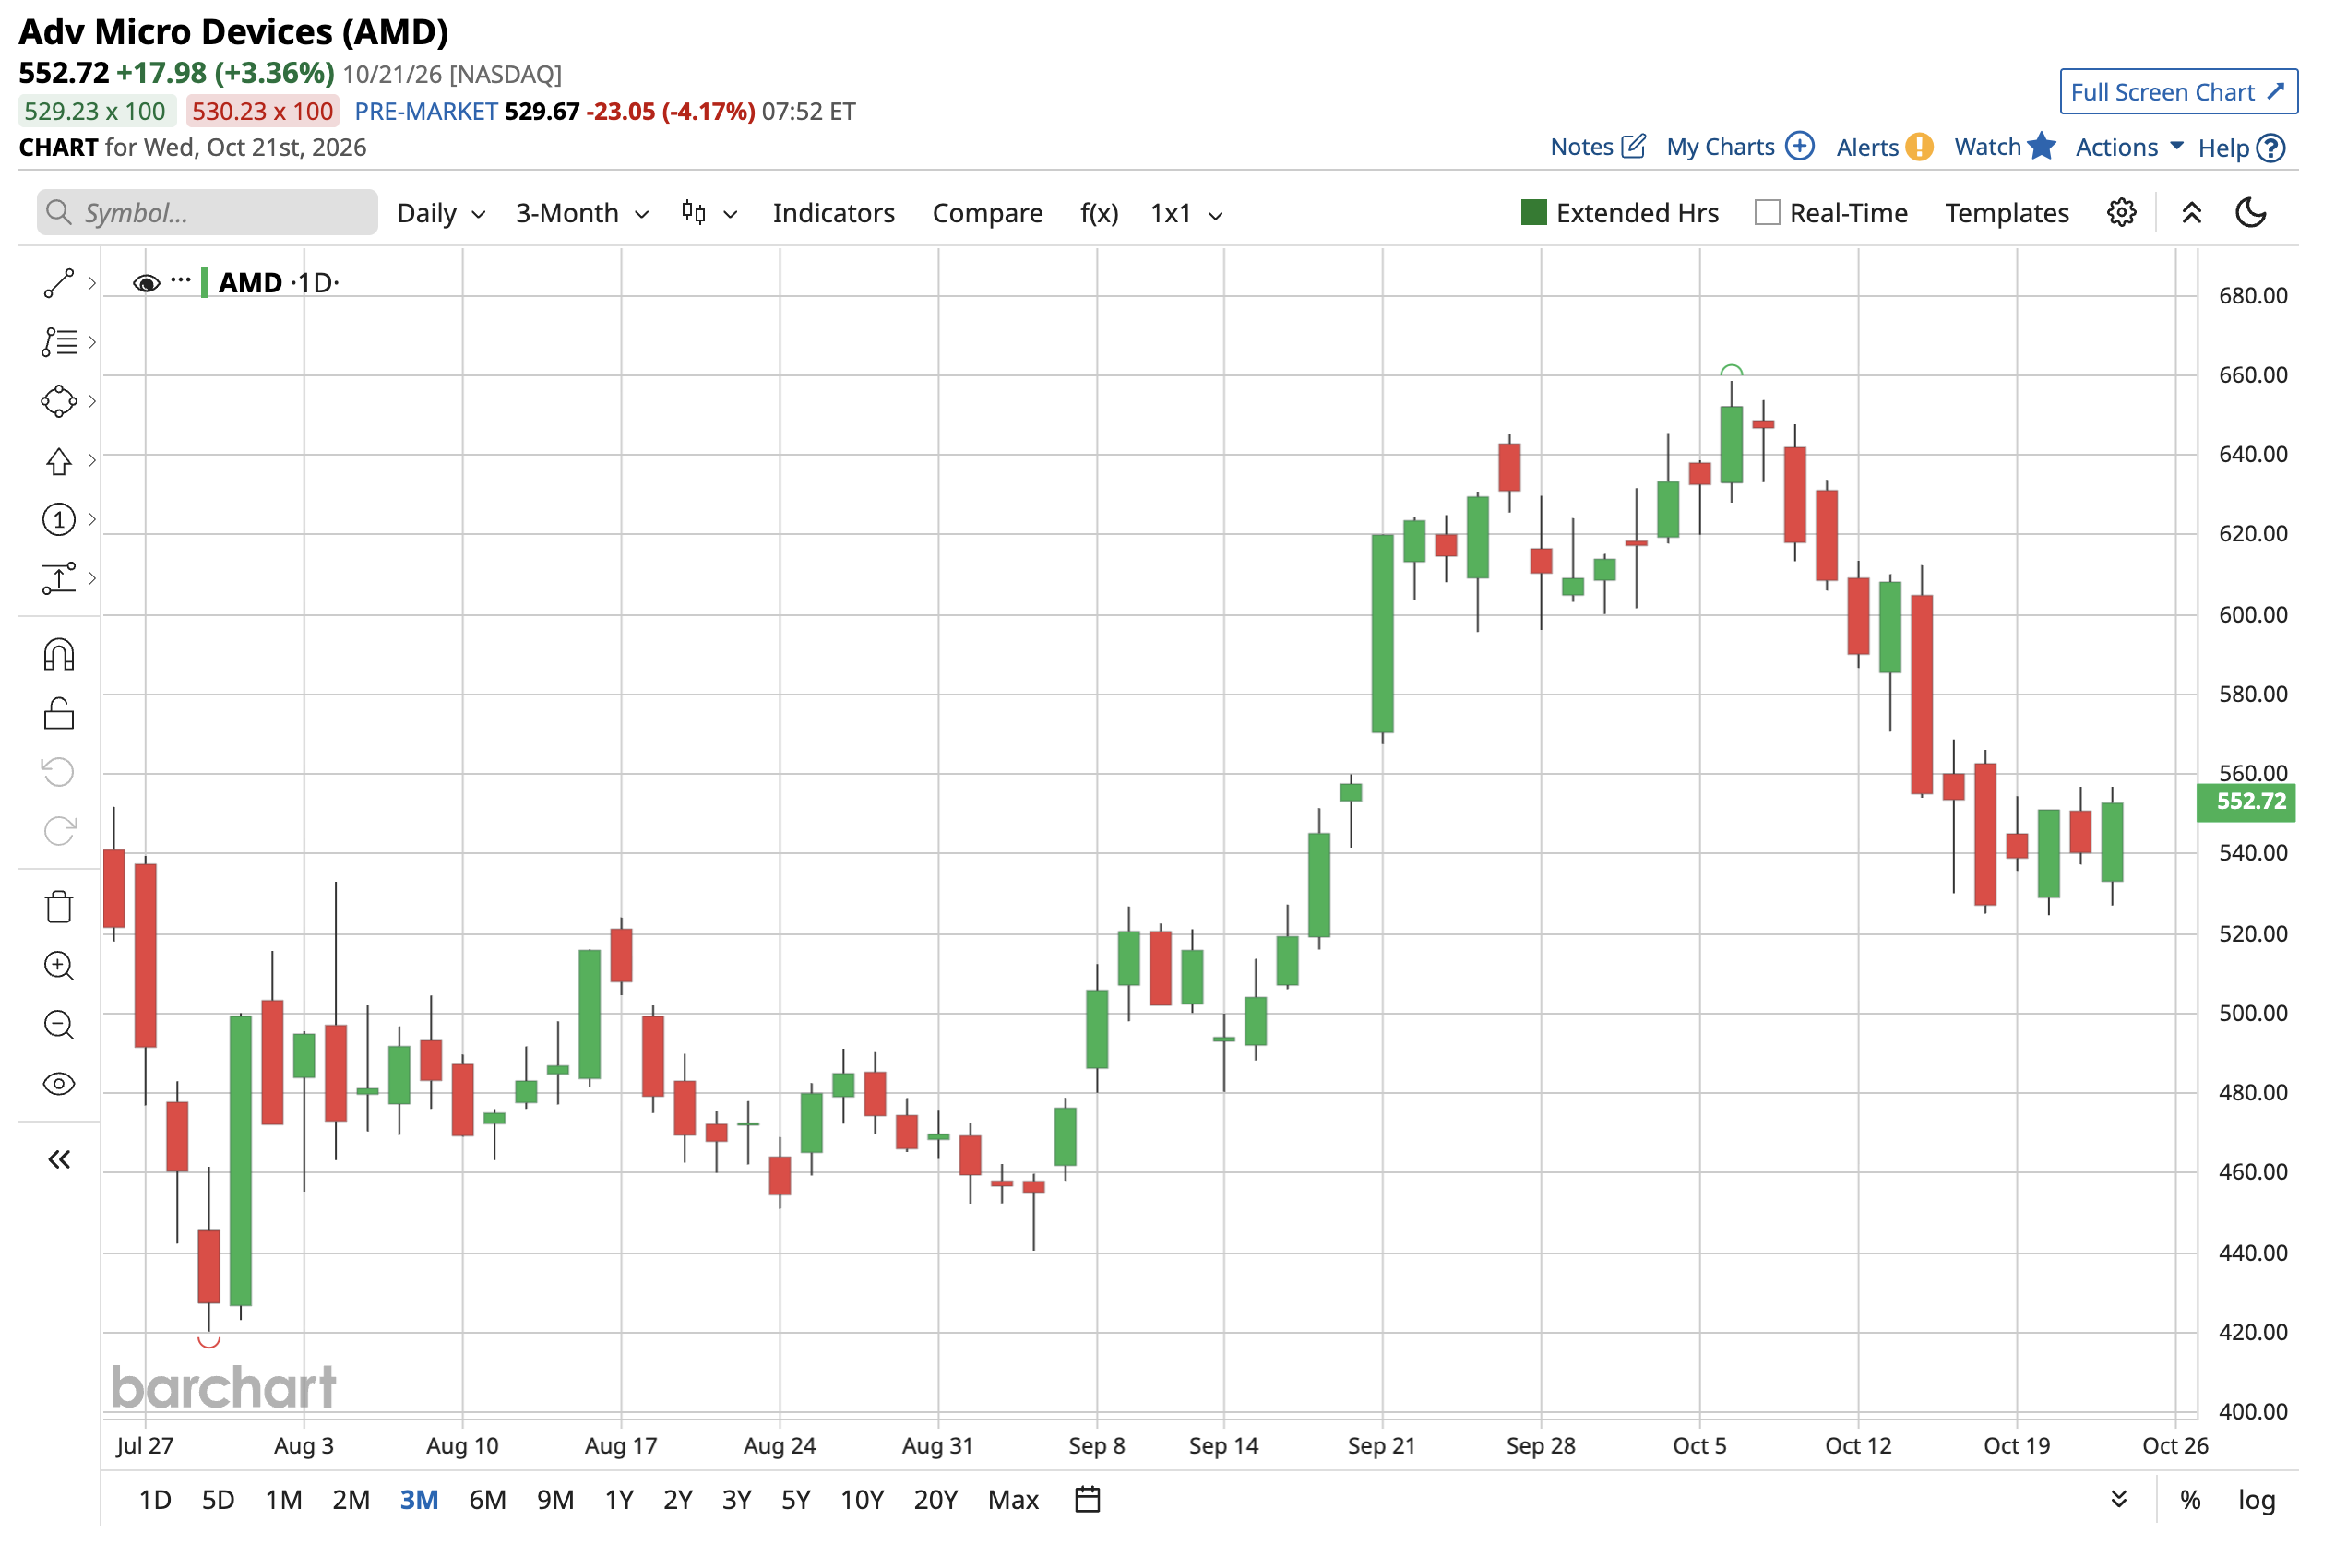
AMD continues to benefit from strong demand for AI chips and server processors. Valued at a market cap of $843 billion, AMD has had a rocking 2026 so far, rallying by 147% on a year-to-date (YTD) basis. It comfortably outperformed VanEck Semiconductor ETF’s (SMH) gain of 49% during the same period. Surging data center sales and rising AI-driven CPU demand pushed it to an all-time high of $658.52 on Oct. 6.
Growth Makes the Premium Look Reasonable
AMD’s valuation remains elevated, with a forward P/E of 75.24x, about 88% above its five-year average of 40.08x. Its forward price-to-sales ratio of 18.29x is also more than twice the five-year average of 8.72x. While these multiples represent a steep premium, strong earnings growth helps support the valuation. Analysts project EPS growth of 81.94% in 2026 and 107.67% in 2027. If those estimates hold, the P/E would fall around 36x on 2027 earnings, below its five-year average. Growth is expected to remain strong through 2029, reducing the multiple to approximately 18x. The company’s balance sheet provides additional room for investment, with $13.11 billion in cash against $4.28 billion in debt. Both figures are relatively modest compared with its $931.85 billion market value.
If Advanced Micro delivers the expected earnings growth and Helion helps it capture agentic AI demand, I believe the company is positioned to grow over the next five years. This potential is why the stock appears on our list of the best American stocks to buy for the period.
Earnings Have Been Strong
Advanced Micro Devices reported its second-quarter fiscal 2026 earnings on August 4. It delivered strong second-quarter 2026 results that largely met high expectations. Despite a share price decline after the release, the company once again delivered a double beat on both revenue and earnings. Revenue rose 50% year-over-year (YoY) to $11.5 billion. Data center revenue reached $6.7 billion, reflecting growth of 107% from the prior year. Gross margins expanded meaningfully to 54% from 40% in the year-earlier period. Earnings per share surged 246% YoY to $1.66, exceeding the consensus forecast of $1.62. This marked the seventh consecutive quarter in which AMD outperformed profit expectations.
Looking ahead, AMD said it expects third-quarter revenue to be between $12.7 billion and $13.3 billion, with the $13 billion midpoint 41% above consensus. Adjusted gross margin is expected to be 56%. Su also said server revenue should grow more than 80% in the second half of 2026. Management now expects long-term revenue growth well above its prior target of over 35%. It also expects to beat its long-term $20 EPS target comfortably.
What Do Analysts Expect for AMD Stock?
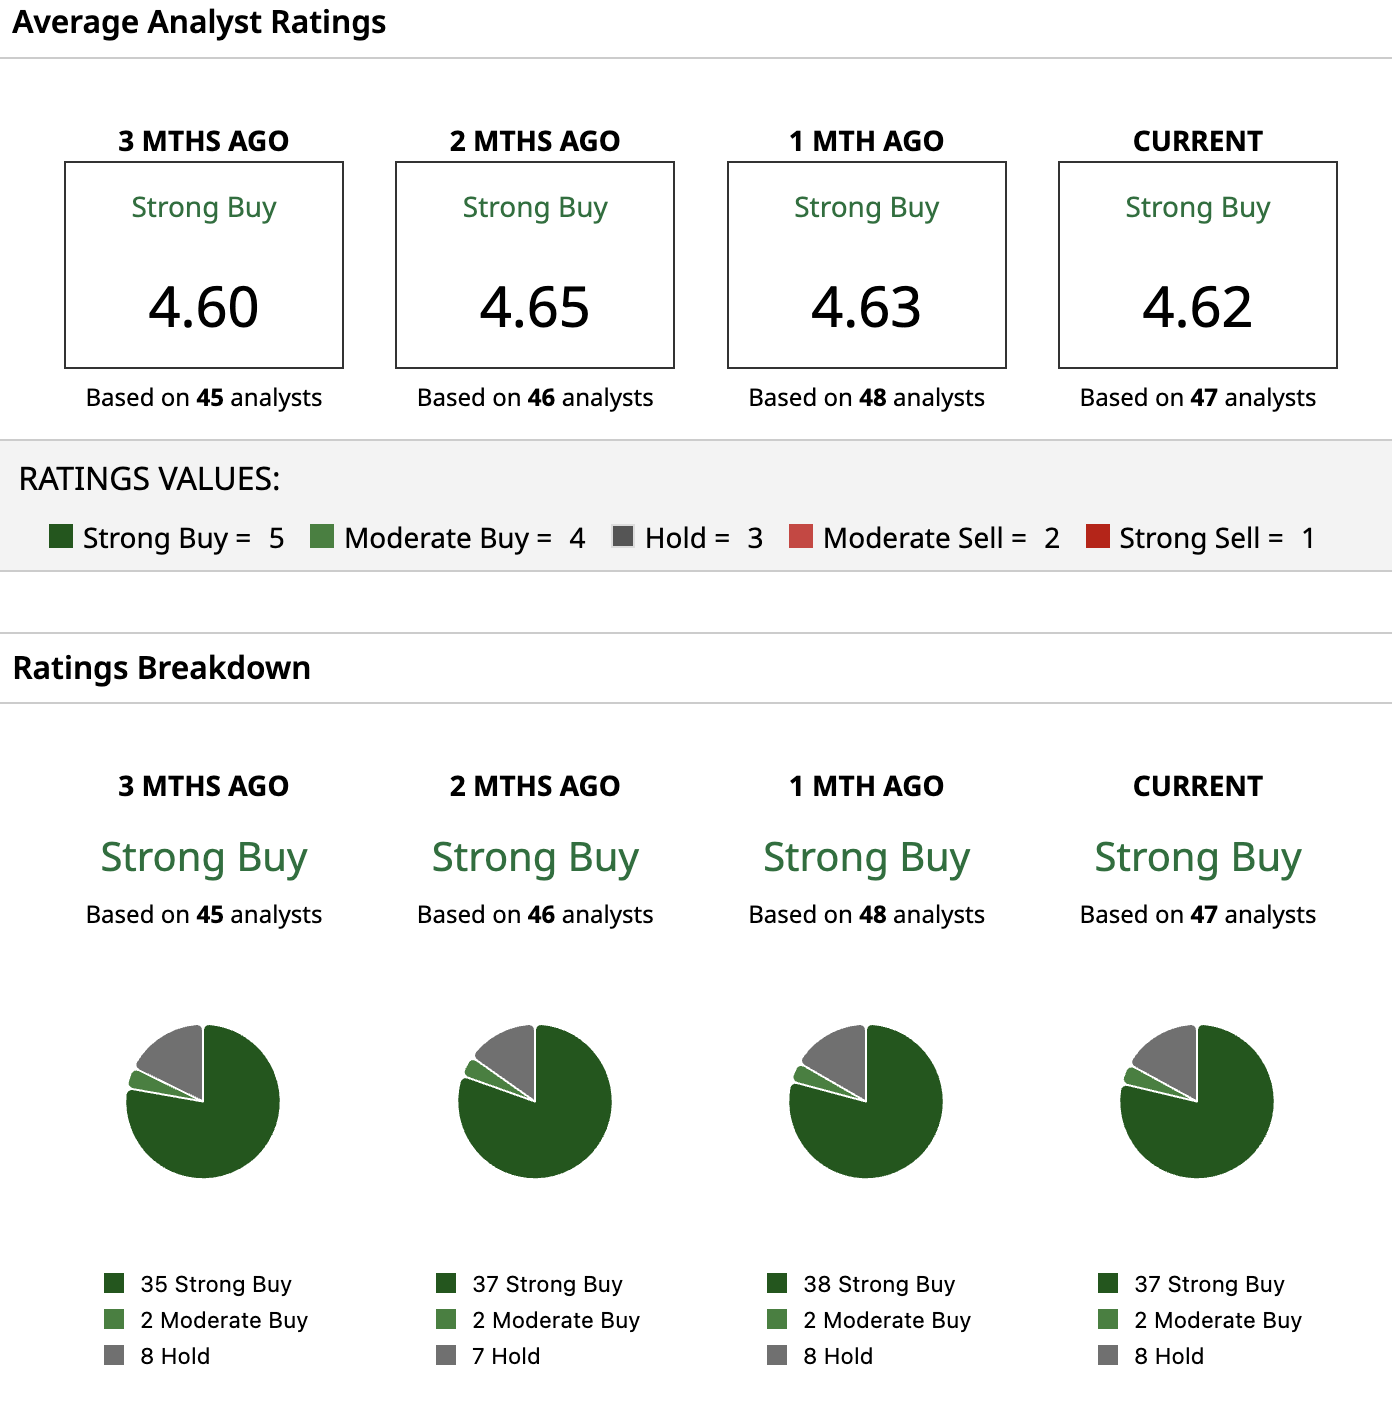
Analysts are bullish on AMD stock. With an overall consensus rating of “Strong Buy,” the mean target price of $653.74 is 18% above AMD's current price. The high target price of $1,250 indicates a potential upside of 126% from current levels. Out of 47 analysts covering the stock, 37 have a “Strong Buy” rating, two have a “Moderate Buy” rating, and eight have a “Hold” rating.
Susquehanna raised the firm’s price target from $550 to $620 and kept a Buy rating on the shares. The firm expects AMD and other semiconductor companies to report slightly better-than-expected Q3 results and provide stronger Q4 guidance. It believes AI demand will continue to drive much of this growth. Similarly, Wedbush also reiterated a Buy rating with a price target of $600.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.