


EN
Freedom Holding (FRHC) Draws Fintech Attention As Investors Ask If The Stock Is Already Pricey
Freedom Holding (FRHC) is drawing fresh attention after its shift from a traditional brokerage to a broad digital fintech platform across 24 countries, supported by proprietary technology and rising institutional investor interest.
Recent trading has been choppy. The share price is up 37.82% year to date with a 9.61% 90 day share price return, yet it has slipped 5.70% over the past week as investors reassess Freedom Holding’s rapid fintech pivot and perceived risk profile.
Scan other fintech and financial platforms showing similar institutional interest and cross-border growth by checking the hand-picked 21 high quality undiscovered gems alongside Freedom Holding.
After a sharp run and a recent pullback, Freedom Holding now presents a simple question for new money: Does the current valuation still leave enough upside to justify the expanding fintech risk profile?
Price-to-Earnings of 74x: Is It Justified For Freedom Holding?
At a recent price of around $171.22, Freedom Holding trades on a P/E of 74x, while the broader US Capital Markets industry sits at 38.1x and peer companies average 11.3x. That is a steep premium for a fintech-oriented financial platform that currently has a 9.6% return on equity.
The P/E multiple compares what investors currently pay for each dollar of earnings to similar businesses in the same space. For a diversified group like Freedom Holding, with brokerage, banking, insurance, and other services spanning multiple countries, a high earnings multiple usually implies that the market is assigning a lot of value to future profit potential rather than the current earnings base.
Recent fundamentals provide mixed signals for that kind of pricing. Earnings grew 86.3% over the past year and net profit margins improved from 5.1% to 8.4%, which helps explain why investors have been willing to assign a richer multiple. At the same time, earnings declined 17% per year over the past 5 years, return on equity is described as low at 9.6%, and the SWS DCF model estimates future cash flow value at $60.23 per share, which is far below the present share price.
The relative comparison is stark. Freedom Holding is described as expensive on its 74x P/E compared with both its 11.3x peer average and the wider US Capital Markets group at 38.1x. That gap indicates that the market is pricing in meaningfully stronger profitability or a much more resilient business model than the typical capital markets stock, and any disappointment in execution or fintech expansion could have an outsized effect on how that valuation is perceived.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 74x (OVERVALUED)
Still, Freedom Holding leans heavily on Kazakhstan for revenue and carries a fintech premium, so any regulatory shock or tech stumble could quickly pressure sentiment.
Find out about the key risks to this Freedom Holding narrative.
Another View On Freedom Holding’s Value
The P/E premium paints Freedom Holding as expensive, yet the SWS DCF model tells a sharper story. On that framework, estimated future cash flows point to a fair value of about $60.23 per share, which is far below the recent $171.22 trading level and firmly in overvalued territory.
This kind of gap raises a simple question for any prospective buyer: Is the market correctly pricing a long runway for the fintech pivot, or is the current share price leaning too heavily on assumptions that the underlying cash generation does not yet support?
Look into how the SWS DCF model arrives at its fair value.
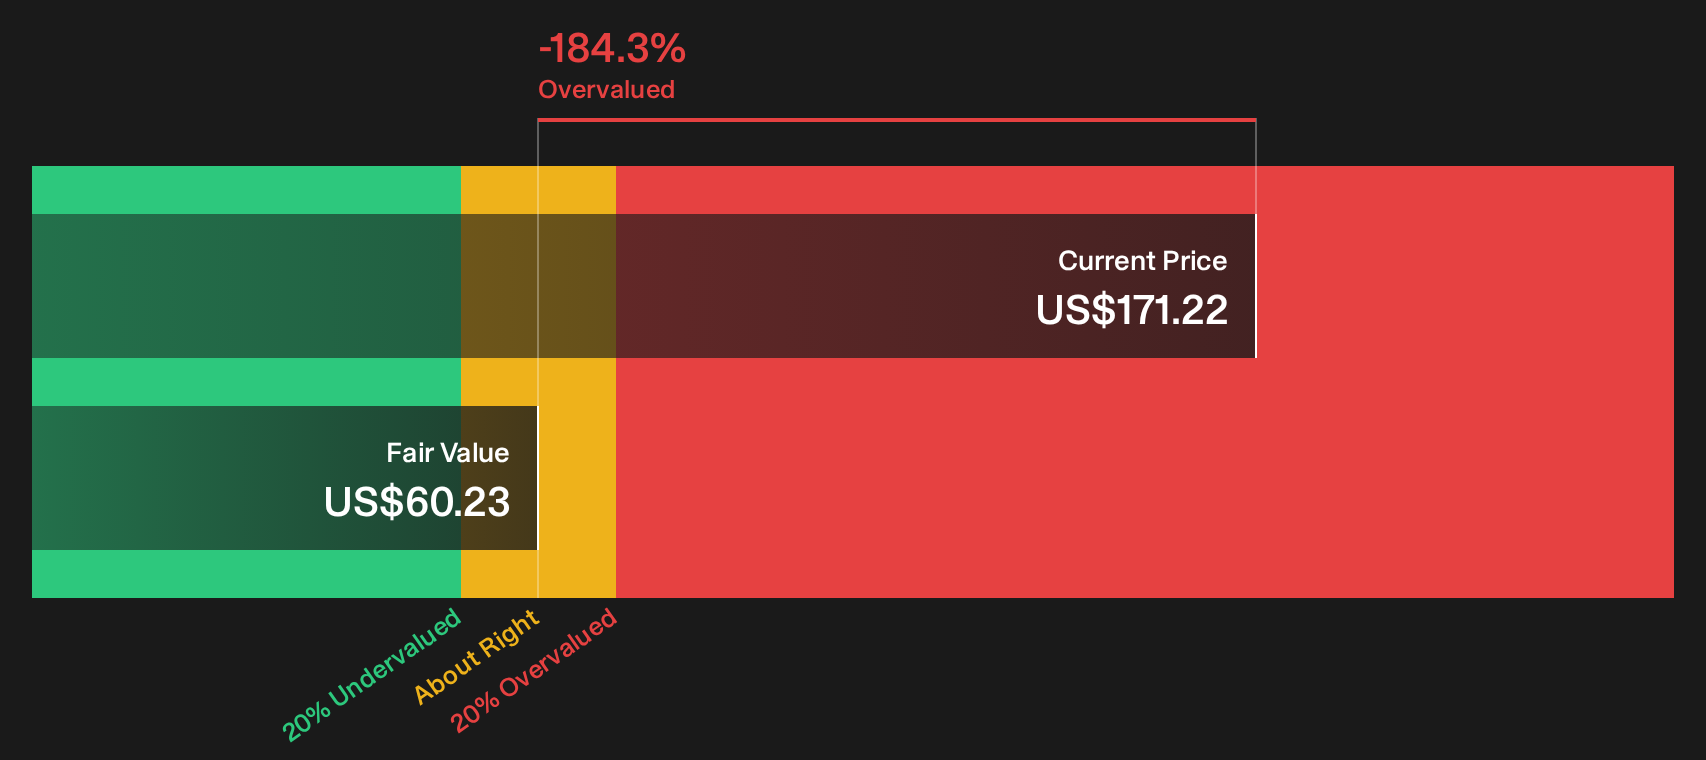
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Freedom Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With mixed signals around Freedom Holding’s valuation and risk profile, do not wait for someone else’s verdict. Instead, interrogate the numbers yourself and weigh up the 1 key reward and 2 important warning signs in the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Freedom Holding?
If Freedom Holding has you rethinking your watchlist, do not stop here. Broader opportunity often sits just outside the tickers everyone is already debating.
- Target potential mispricings by scanning the 29 high quality undervalued stocks and compare fundamentals before sentiment catches up.
- Prioritise resilience by working through the 30 resilient stocks with low risk scores so capital is aligned with steadier risk profiles instead of headline hype.
- Hunt for fresher opportunities by tracking the 21 high quality undiscovered gems that the wider market may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com