


EN
SHIFT (TSE:3697) Could Be 23% Below Fair Value On Raised Dividend And Outlook
SHIFT (TSE:3697) just paired a higher year end dividend with fresh guidance and full year results that showed higher sales but lower net income. The mix provides a clearer picture of management’s priorities.
SHIFT’s recent updates are landing against a sharp rebound in the share price, with a 30 day share price return of 30.61% and a 90 day share price return of 43.25%, even though the 5 year total shareholder return is down 33.38%.
Compare SHIFT’s renewed focus on dividends and capital allocation with other software stocks by scanning our hand picked list of 72 high quality undiscovered gems that pair solid fundamentals with under the radar valuations.
SHIFT shares have jumped, yet still trade at a discount to one estimate of intrinsic value, while sitting above analyst targets. Is the recent optimism racing ahead of what the market’s caution is trying to price in?
Price to Earnings of 39.8x: Is it justified?
SHIFT trades on a P/E of 39.8x, which is a rich tag at ¥1,156 given that peers and the wider JP IT sector are priced materially lower.
The P/E ratio links what investors are willing to pay today to the company’s earnings per share. For a software testing and consulting group like SHIFT, a higher multiple often reflects expectations for stronger profit growth, relatively predictable cash generation, or both.
Here, the market is attaching roughly double the peer average P/E of 19.9x and well above the JP IT industry at 16.4x. That is a strong signal that investors are willing to pay up for SHIFT’s profile. At the same time, the estimated fair P/E of 41.5x suggests the current 39.8x level is not stretched on this framework and could reasonably move closer to that reference point if sentiment stays intact.
Explore the SWS fair ratio for SHIFT.
Result: Price to Earnings of 39.8x (ABOUT RIGHT)
Still, SHIFT’s premium P/E rests on confidence that revenue growth near 13% and net income growth around 36% can be sustained, and that capital allocation remains disciplined.
Find out about the key risks to this SHIFT narrative.
Another view on SHIFT’s value
The SWS DCF model tells a different story to the rich P/E. On that framework, SHIFT at ¥1,156 trades below an estimated future cash flow value of ¥1,503.3, which implies the market is giving limited credit to those forecast earnings gains. Which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
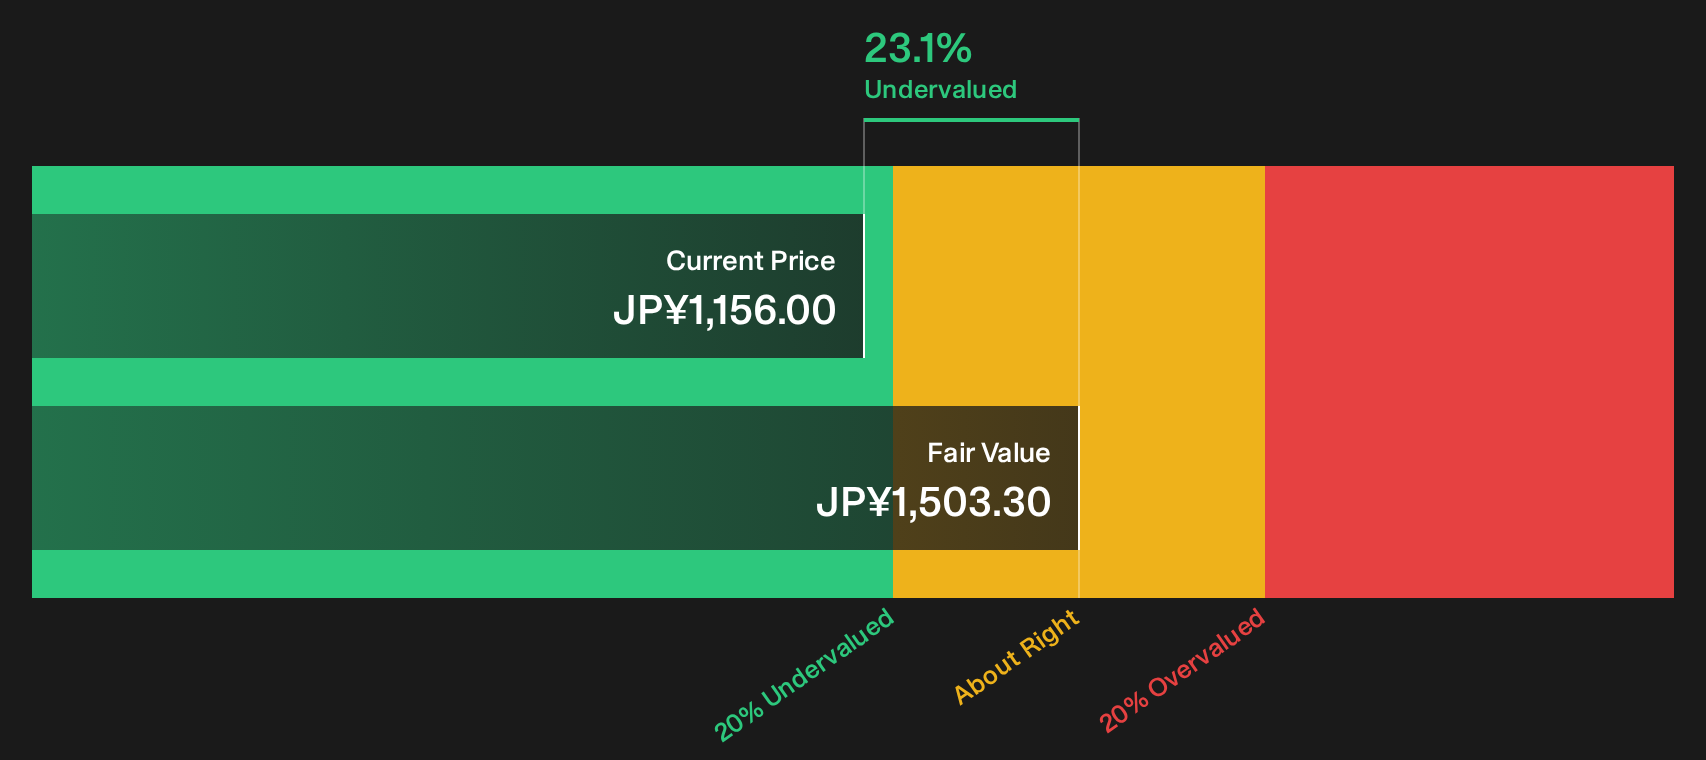
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SHIFT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on SHIFT’s valuation story can feel messy, so move quickly, test the numbers yourself, and decide where you stand by weighing the 2 key rewards and 2 important warning signs
Looking for more SHIFT investment ideas?
Broaden your watchlist beyond SHIFT by using the Simply Wall St Screener to quickly surface fresh stock ideas that fit the way you like to invest.
- Target resilient balance sheets and steady fundamentals by filtering companies through the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by focusing on businesses that pass the 14 high quality undervalued stocks.
- Prioritise consistency and capital protection by reviewing companies highlighted in the 22 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com