


EN
Earnings Guidance Could Be A Catalyst For Yankuang Energy Group Stock (SEHK:1171)
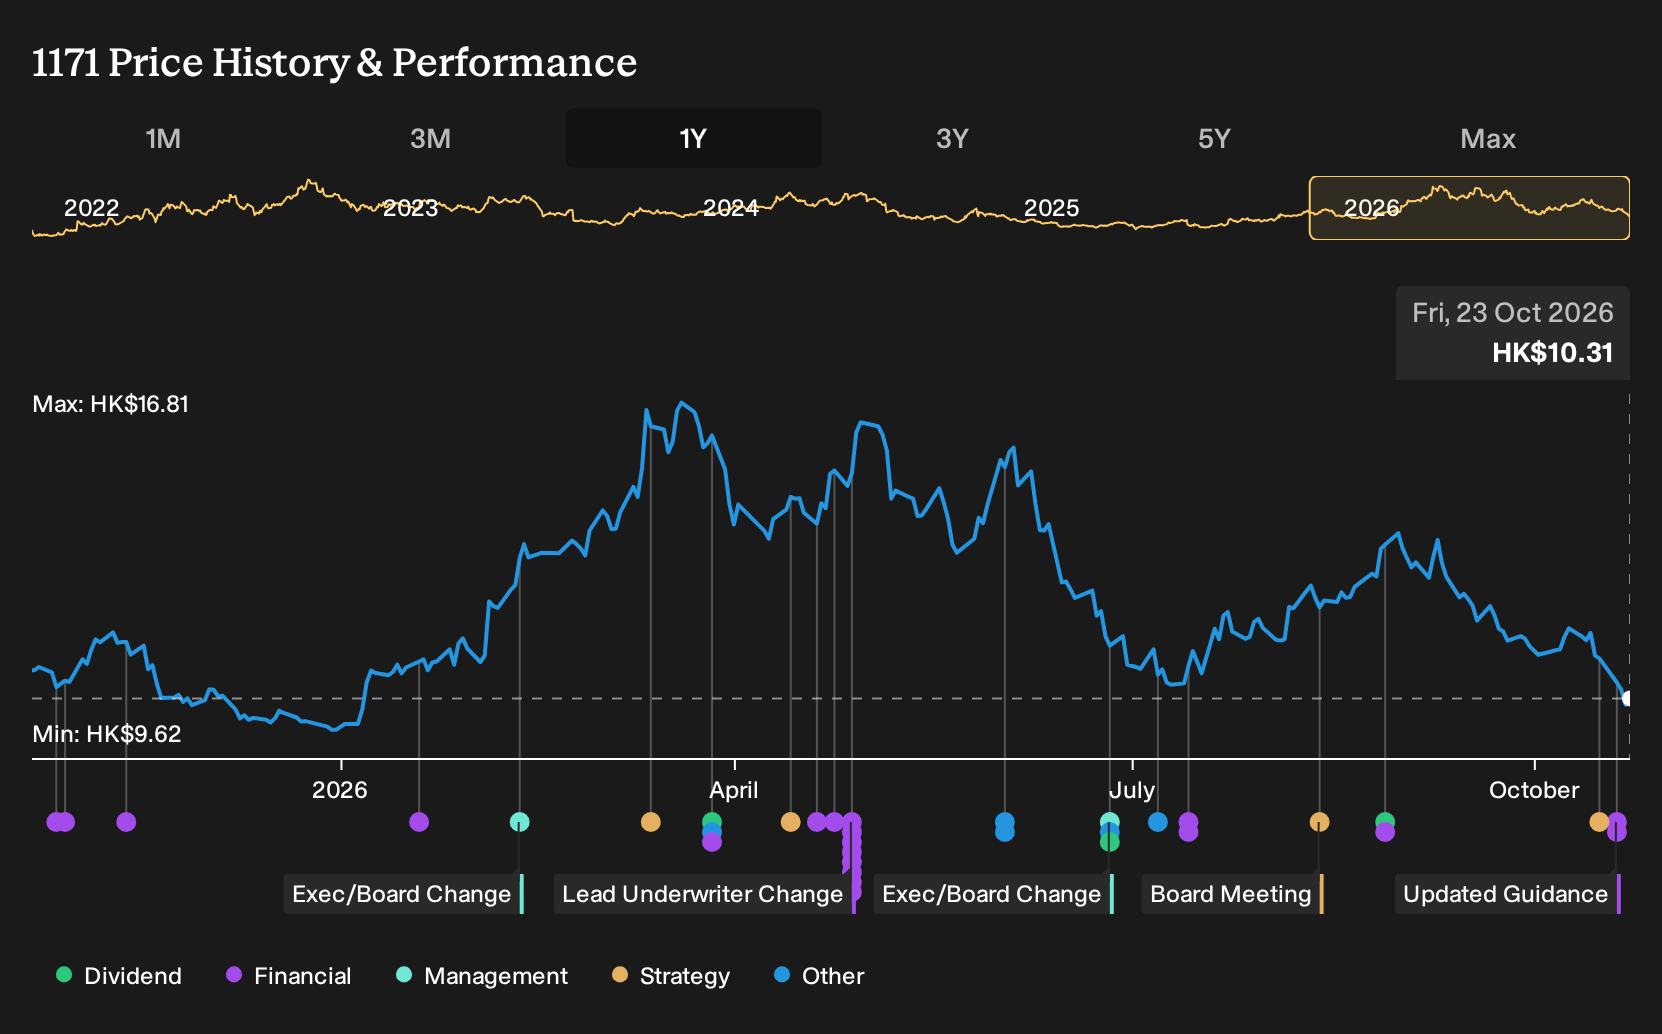
- Yankuang Energy Group issued preliminary guidance indicating net profit attributable to shareholders of about RMB 11.1b for the first three quarters of 2026, with underlying profit after non recurring items of roughly RMB 8.5b.
- The guidance points to higher profitability despite relatively stable coal and chemical production and sales volumes. This puts operating efficiency and pricing power at the center of the Yankuang Energy Group story.
- The next step is to examine how Yankuang Energy Group's investment narrative intersects with this forecasted change in net profit and core earnings.
What Is Yankuang Energy Group's Investment Narrative?
To own Yankuang Energy Group, you have to buy into a fairly simple idea. This is a coal and chemicals producer that leans on operational execution and pricing rather than rapid volume expansion. The latest guidance, with net profit attributable to shareholders of about RMB 11.1b and underlying earnings of roughly RMB 8.5b for the first three quarters of 2026, suggests the current phase of the story is about squeezing more cash out of broadly steady production.
In the short term, the forecasted profit jump intersects with a few moving parts. Volumes in coal and key chemical products for 2026 to date look broadly stable or slightly softer, so recent guidance points you back to pricing discipline, cost control and mix as the real catalysts. On the risk side, the stock screens as good value on P/E and as discounted against some fair value estimates, yet free cash flow coverage of a roughly 5.9% dividend yield already looks tight. If higher earnings do not translate into stronger cash generation, the headline guidance could matter less than it seems.
Even so, there is a structural pressure point in Yankuang Energy Group's set up that is easy to overlook until you look closely at ...
There's only one way to know the right time to buy, sell or hold Yankuang Energy Group. Head to Simply Wall St's company report for the latest analysis of Yankuang Energy Group's Fair Value.
Exploring Other Perspectives
Community views on Yankuang Energy Group are already split, with 2 Simply Wall St Community fair value estimates ranging from RMB 14.88 to RMB 98.15. You are seeing private investors on very different pages. Set that against the latest profit guidance and relatively steady coal and chemical volumes, and then consider how future cash conversion might reshape those opinions.
Explore another Yankuang Energy Group fair value estimate, including one that suggests it could be worth just HK$14.88!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yankuang Energy Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Yankuang Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yankuang Energy Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Yankuang Energy Group?
Once you have a view on Yankuang Energy Group, it helps to compare it with other opportunities that share some of the qualities you care about, whether that is value, balance sheet strength, or resilience through the cycle.
- If you want potential value coupled with solid fundamentals, use the 613 high quality undiscovered gems to surface companies that may not yet be widely followed but already have substance behind them.
- For a focus on durability and capital protection, filter for 221 resilient stocks with low risk scores to find businesses that score well on stability and risk metrics.
- When cash strength and financial footing matter most, lean on the list of solid balance sheet and fundamentals (205 results) to see a list of companies where the balance sheet and underlying fundamentals do much of the heavy lifting.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com