


EN
Is NCC (OM:NCC B) A Bargain After Its October Contract Wins?
NCC (OM:NCC B) has landed a string of fresh contracts that reshapes its project pipeline. October brought new work on the Öland Bridge, a heritage Helsinki school upgrade and an Örkelljunga swim center.
NCC’s latest contract wins come after a mixed share price performance, with the stock at SEK176.2, reflecting a decline of about 20% year to date. However, a 3-year total shareholder return of roughly 82% still indicates that longer term investors have seen sizeable gains.
Scan construction peers winning fresh infrastructure and public building work and see which ones screen well on quality and value using our hand picked list of solid balance sheet and fundamentals (205 results).
NCC now carries a year to date decline of about 20% alongside a strong three year total return and a fresh haul of projects worth several billion SEK. Is this the moment to step in or wait for a clearer entry?
Most Popular Narrative: 14% Undervalued
On the latest widely followed view, NCC’s fair value of SEK205 sits above the recent SEK176.2 close. This puts fresh contract news into the context of a valuation gap that investors are actively debating.
The planned divestment of NCC Industry for an enterprise value of SEK 8.2b, with about SEK 7b of expected cash inflow at closing, is set to leave NCC as a more focused, lower-capital-intensity contracting group, which can influence future earnings, net margins and capital allocation capacity.
See why 11 investors see NCC as 14% undervalued.
Result: Fair Value of SEK205 (UNDERVALUED)
Still, litigation costs around terminated projects and the planned exit from NCC Industry, which removes SEK12.6b of net sales, could easily challenge that 14% undervaluation story.
Find out about the key risks to this NCC narrative.
Another View: NCC Through The Cash Flow Lens
The analyst narrative describes NCC as roughly 14% undervalued at SEK205, based on earnings and margin rebuilding. A very different picture emerges once you switch to Simply Wall St's DCF model, which points to a future cash flow value of SEK62.57. That implies the current SEK176.2 price could be well above what long term cash generation supports. So which version of value do you trust?
To unpack how this cash flow driven result is built and where the assumptions have the greatest impact, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
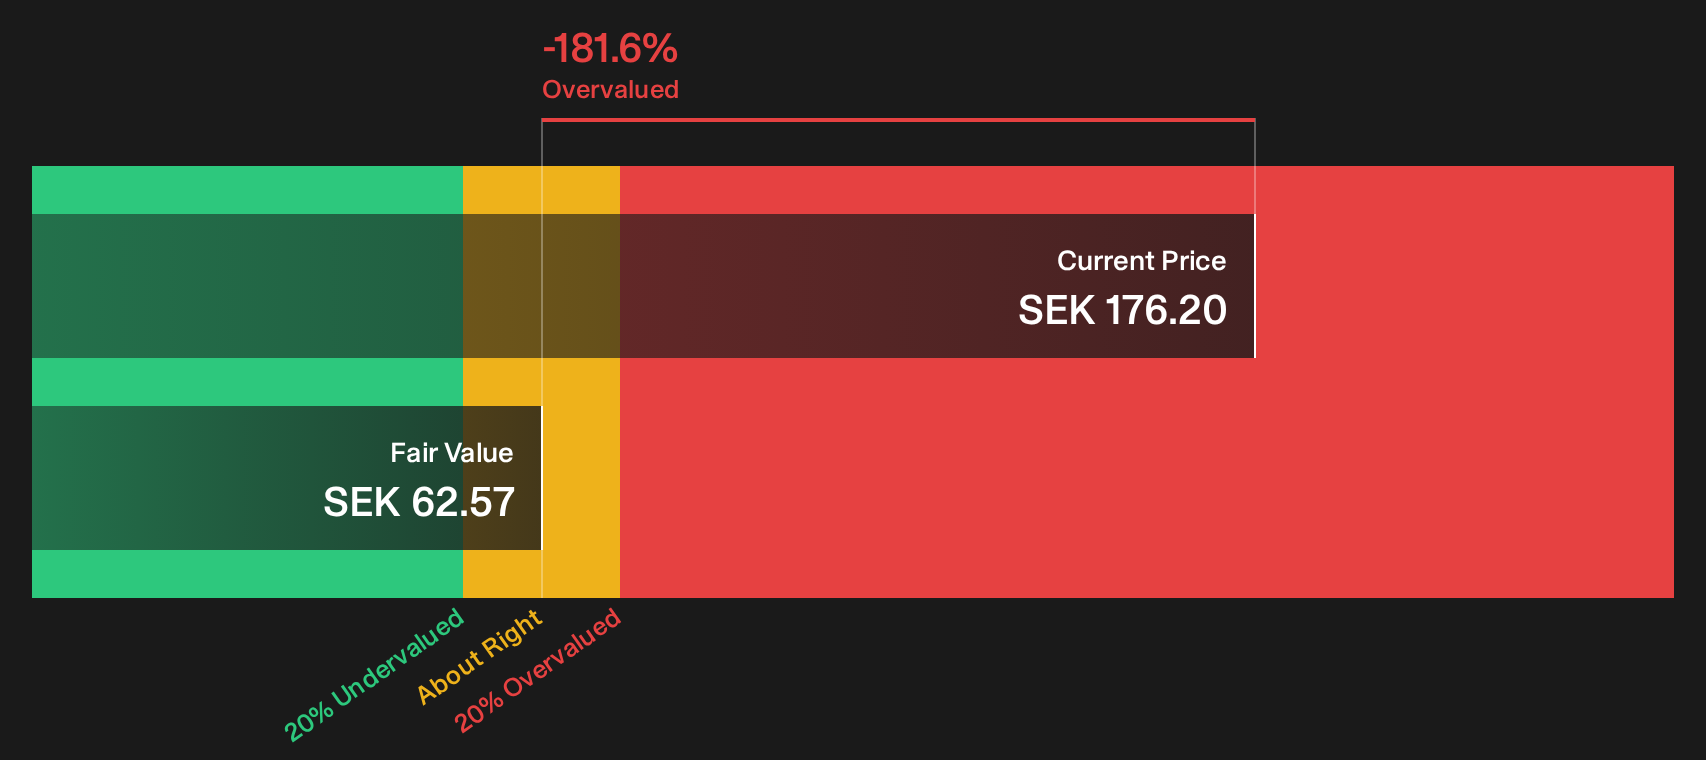
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NCC for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on NCC’s value story. If you want to act while sentiment is divided, weigh the trade off yourself by checking the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond NCC?
Do not stop with one contractor story when the wider market is full of very different risk and return profiles that might fit your goals better.
- Target potential value opportunities by scanning our hand picked 193 high quality undervalued stocks that filters for companies combining quality fundamentals with pricing that may look appealing.
- Prioritise resilience by reviewing a curated 221 resilient stocks with low risk scores focused on businesses with sturdier balance sheets and milder volatility profiles.
- Hunt for under the radar potential with a focused 613 high quality undiscovered gems that surfaces lesser followed stocks backed by stronger financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com