


EN
Loews (L) Pulls Back As Valuation Looks Full After A Strong Run
Loews (L) has been drawing fresh attention after recent trading left the share price at US$112.01, putting a spotlight on how investors weigh its diversified insurance, pipelines, hotels, and plastics businesses.
The recent pullback of around 1.5% on the day comes after a 30 day share price return of roughly 6.9%. The 1 year total shareholder return of about 12.2% and 5 year total shareholder return just above 100% point to momentum that has built over the longer stretch rather than faded.
Scan how Loews compares with other diversified financial and infrastructure plays by reviewing our hand picked 30 resilient stocks with low risk scores that aim to pair resilience with measured upside potential.
Loews now trades near recent highs after a strong multi year run, yet the latest dip has nudged its implied intrinsic value slightly above the market price. Does that still leave enough potential benefit to justify the risk?
Price-to-Earnings of 13.6x: Is it justified?
Loews now trades on a P/E of 13.6x, a level that sits above insurance peers. The recent share price of $112.01 is only slightly above some intrinsic value estimates.
The P/E ratio compares what investors pay for each dollar of earnings. For a diversified insurer and infrastructure group like Loews, this metric often reflects expectations around the stability and quality of profits rather than rapid expansion.
Loews has posted 25.1% earnings growth over the past year and has what is described as high quality earnings. This can help explain why the market is willing to pay a higher multiple than for many insurance stocks. Net profit margins of 9%, up from 7.5% a year earlier, and profit growth that has run faster than the wider insurance sector over the past year, also support a richer earnings tag compared with slower growing peers.
The current 13.6x P/E is described as expensive versus both the US Insurance industry average of 11.1x and a peer group at 11.7x. This means investors are assigning Loews a clear premium relative to comparable insurers and diversified financial groups.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 13.6x (OVERVALUED)
Still, Loews carries clear risks, including insurance underwriting volatility and exposure to energy and travel cycles through pipelines and hotels, which could pressure earnings and valuation.
Find out about the key risks to this Loews narrative.
Another View: Loews Through A Cash Flow Lens
Price multiples tell you what investors pay for current earnings. The SWS DCF model instead asks what future cash flows are worth in today’s dollars. On that score, Loews at $112.01 screens as slightly overvalued versus an estimated future cash flow value of $109.41.
The gap is small in dollar terms, yet it raises a practical question for you as a shareholder. Is paying above that model value a fair trade off for Loews’ diversified mix of insurance, pipelines, hotels, and plastics, or is it a signal to demand a wider margin of safety?
Look into how the SWS DCF model arrives at its fair value.
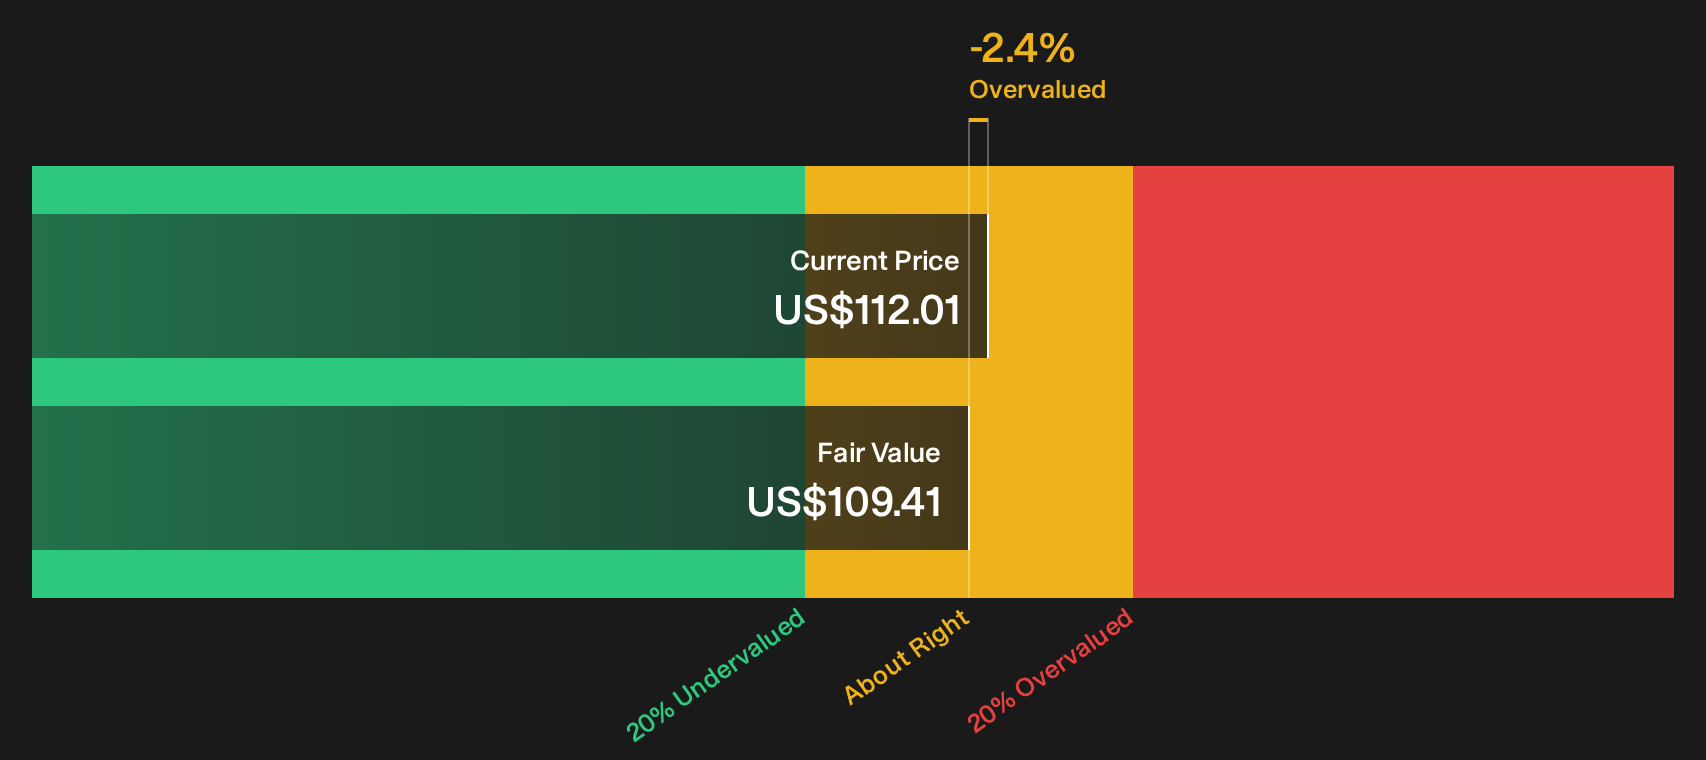
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Loews for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Loews might feel mixed after this, which is exactly why you should move quickly, review the data, and decide where you stand. To see what the upside case looks like in more detail, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Loews?
Do not stop your research with Loews. Broaden your watchlist with fresh ideas built from clear fundamentals and transparent data on Simply Wall Street.
- Target dependable cash generators by scanning companies that appear in the 29 high quality undervalued stocks based on solid earnings and balance sheet support.
- Zero in on income potential by reviewing the 5 dividend fortresses that focus on higher yielding payouts with financial backing behind them.
- Prioritize durability under pressure and track the list of solid balance sheet and fundamentals (24 results) that highlight stronger finances and cleaner leverage profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com