


EN
Did Earnings Beat Just Shift First Bancorp (FBNC) Stock Investment Narrative?
- First Bancorp reported third quarter 2026 net interest income of US$114.8 million and net income of US$51.28 million, alongside net charge offs of US$2.1 million for the period.
- The sharp rise in basic and diluted earnings per share from continuing operations to US$1.24 in the quarter indicates higher profitability even after absorbing credit costs.
- The next area of focus is how First Bancorp's stronger earnings per share profile could reshape the broader investment narrative around the bank.
What Is First Bancorp's Investment Narrative?
To own First Bancorp, you need to be comfortable with a straightforward regional banking story that leans on lending spreads, disciplined credit, and relatively efficient operations. The latest quarter fits that picture. Net interest income of US$114.8 million and net income of US$51.28 million point to solid underlying demand for loans and services. The reported US$2.1 million in net charge offs looks manageable in the context of those earnings, so the near term credit signal is more about normal risk than a clear warning sign.
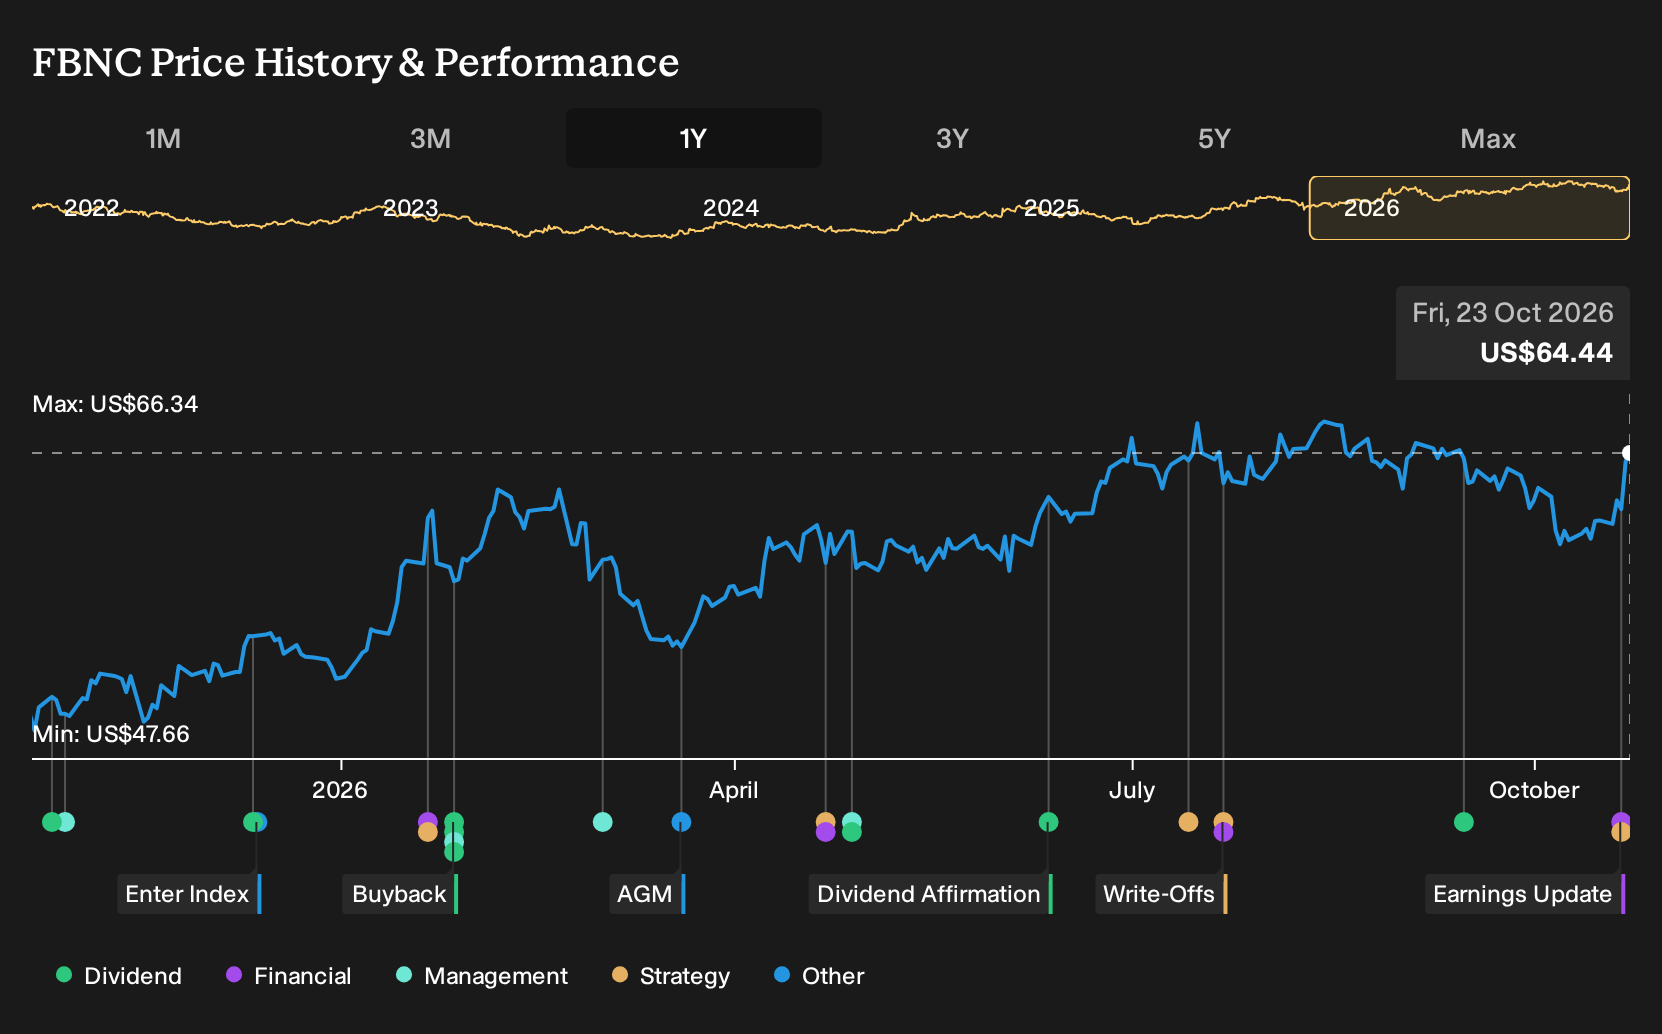
The real swing factor now is whether First Bancorp can keep translating that earnings base into consistent returns without leaning too hard on balance sheet growth or higher credit risk. Forecasts calling for earnings growth of around 15.1% a year and revenue growth near 11.9% suggest expectations are already meaningful, while the P/E of 16.3x sits above both the US Banks industry average and peer levels. With the stock already up strongly over 1 year, the combination of richer pricing, insider selling in recent months, and this latest earnings beat sets up a simple question for you as a shareholder.
That said, tucked inside this stronger story is one pressure point that deserves a closer look before you get carried away with the upside potential.
There's only one way to know the right time to buy, sell or hold First Bancorp. Head to Simply Wall St's company report for the latest analysis of First Bancorp's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$69.60 and US$99.84, so you already see how far opinions on First Bancorp can stretch. Those views were set before the latest US$51.28 million quarterly net income and US$2.1 million in net charge offs, giving you clear reasons to revisit multiple angles before committing fresh capital.
Explore another First Bancorp fair value estimate, including one that suggests it could be worth just $69.60.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your First Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review First Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond First Bancorp?
If First Bancorp has sharpened your focus on quality and risk, use that same lens to broaden your watchlist with a few targeted screens on Simply Wall St.
- If you want potential mispricing opportunities backed by solid fundamentals, start with a focused group of 29 high quality undervalued stocks that may warrant a deeper look.
- For income oriented investing, shortlist companies that combine meaningful yield with staying power by scanning through a curated set of 5 dividend fortresses.
- When capital preservation ranks high for you, build a shortlist from a carefully filtered pool of 30 resilient stocks with low risk scores that score well on resilience and consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com