


EN
Centrus Energy (LEU) Faces A Valuation Test, Is It A Bargain Or Fully Priced?
Recent trading performance and business profile
Centrus Energy (LEU) has drawn attention after a sharp pullback, with the share price closing at US$102.45 and declining about 30% over the past month and about 42% over the past 3 months. The nuclear fuel specialist now carries a market value of roughly US$2.10b, backed by US$473.9m in revenue and US$48.5m in net income from its most recent reported year.
The business runs through two main operations. The larger LEU segment supplies low enriched uranium products and related components to nuclear utilities, while Technical Solutions provides engineering, manufacturing and operations services to public and private customers in the energy sector.
For Centrus Energy, recent trading has been punishing, with the share price return down sharply over the past quarter and year to date, while the 3-year total shareholder return remains strongly positive. This suggests that long-term holders have still seen meaningful gains despite the current loss of momentum.
Spot opportunities across the nuclear fuel chain by lining up Centrus Energy against a curated 16 nuclear energy infrastructure stocks that are also exposed to reactors, enrichment, and supporting infrastructure.Centrus Energy appears to be a solid nuclear fuel business based on recent numbers, yet the share price has been hit hard in a short span. Does that reset leave the valuation appealing, or is it still demanding as things stand today?
Most Popular Narrative: 46% Undervalued
Centrus Energy closed at $102.45, while the most followed narrative on the stock anchors on a fair value of $190. That gap frames the current selloff less as a simple momentum break and more as a valuation reset that some investors see as overdone.
Centrus Energy (LEU) offers the most direct public-market exposure to U.S. HALEU production, a critical bottleneck for advanced nuclear deployment.
HALEU fuel scarcity could constrain next-gen reactor rollouts, making LEU's enrichment capabilities strategically vital as AI-driven electricity demand surges.
See why 44 investors see Centrus Energy as 46% undervalued.
Result: Fair Value of $190 (UNDERVALUED)
Still, the Centrus Energy narrative hinges on continued government backing for HALEU and timely advanced reactor deployment; both of these could easily slip or be scaled back.
Find out about the key risks to this Centrus Energy narrative.
Another View: Centrus Energy on earnings multiples
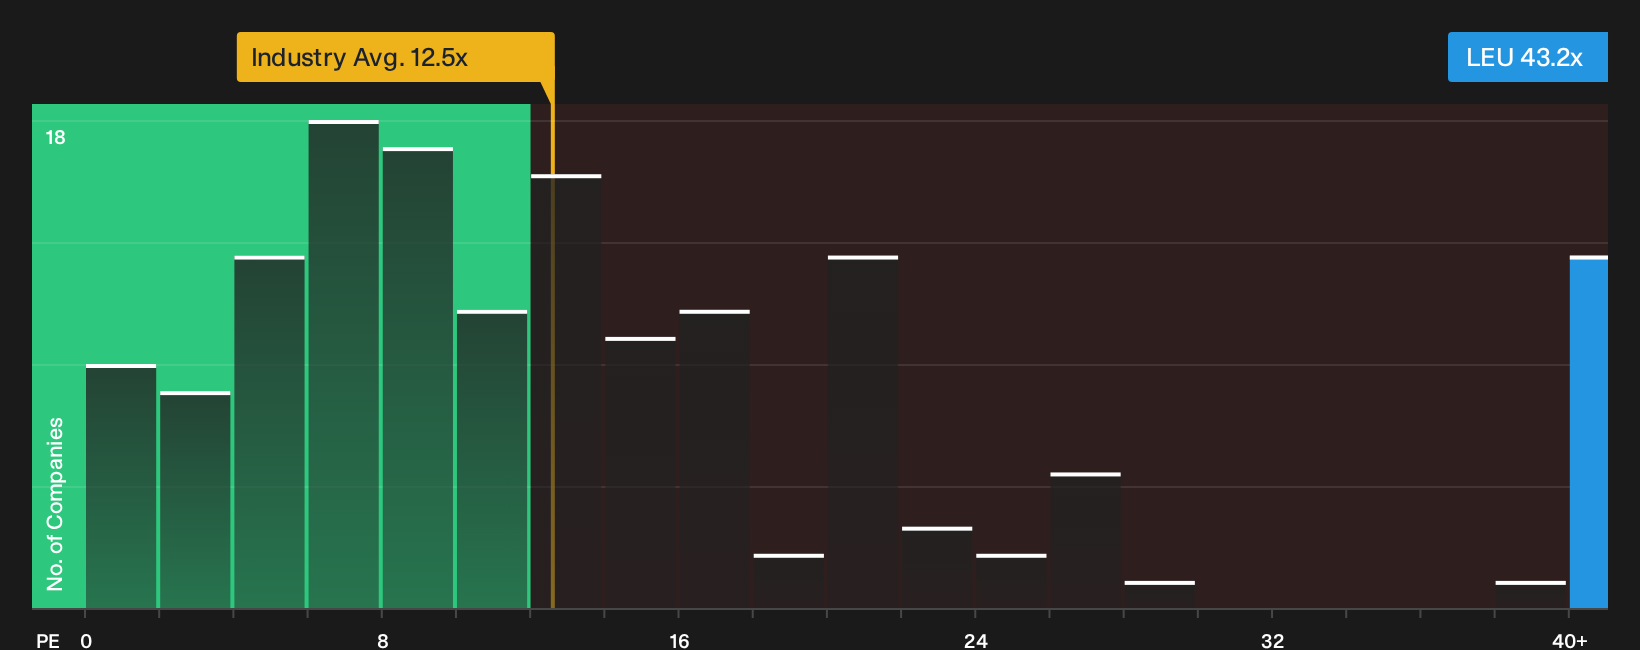
Centrus Energy might look inexpensive relative to the $190 fair value suggested by some narratives, yet its current P/E of 43.2x is high compared with the US Oil and Gas industry at 12.5x, peers at 22x, and a fair ratio of 9.6x. That kind of gap points more toward valuation risk than a straightforward bargain. Which lens feels more realistic to you right now?
Investors who focus on earnings multiples may want to see how that pricing gap appears in a full breakdown of profitability, peer comparisons, and the fair ratio trend over time, then consider whether the current setup aligns with their risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Centrus Energy so far, right, with both concern and optimism showing up in the numbers and narratives. Act quickly by reviewing the key risk flags and potential upsides for yourself, starting with 1 key reward and 2 important warning signs.
Looking for more Centrus Energy investment ideas?
Do not stop at Centrus Energy alone. Broaden your watchlist with a few focused stock shortlists that can surface fresh ideas aligned with how you like to invest.
- Target potential mispricing by scanning a curated pool of companies that screen as high quality yet out of favour through the 29 high quality undervalued stocks.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that leans toward steadier balance sheets and lower historical risk scores.
- Hunt for underfollowed opportunities by combing through a 21 high quality undiscovered gems that highlights strong fundamentals outside the usual headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com