


EN
Does Profit Rebound Change The Bull Case For Hexagon (OM:HEXA B)?
- Hexagon reported Q3 2026 sales of €1,049.1 million and net income of €446 million, a return to profit compared with a loss a year earlier, with earnings supported by cost savings, tariff refunds and a sizeable one off gain from equity investments.
- The rebound in profitability also came with progress in Autonomous Solutions and Manufacturing Intelligence, which helped support higher earnings per share despite the dilutive setup from the pending Waygate acquisition and rising robotics investment.
- We will now look at how Hexagon's investment narrative is affected by this profitability rebound, which is driven partly by a large one off gain.
Scan beyond Hexagon and line up other automation and inspection specialists that could benefit from similar profitability themes with the hand picked 95 robotics and automation stocks in minutes.
Hexagon Investment Narrative Recap
To own Hexagon, investors need to believe the refocused measurement, inspection and autonomy portfolio can keep generating high quality earnings as cost programs bed in and robotics spending climbs. The Q3 profit rebound supports that view, but the large one off gain limits how much comfort can be taken from headline net income and margins.
The near term swing factor is whether Autonomous Solutions and Manufacturing Intelligence can support margins while Waygate integration and higher R&D outlay weigh on the P&L. The key risk remains pressure on profitability if tariffs, input costs or robotics expenses move against Hexagon at the same time.
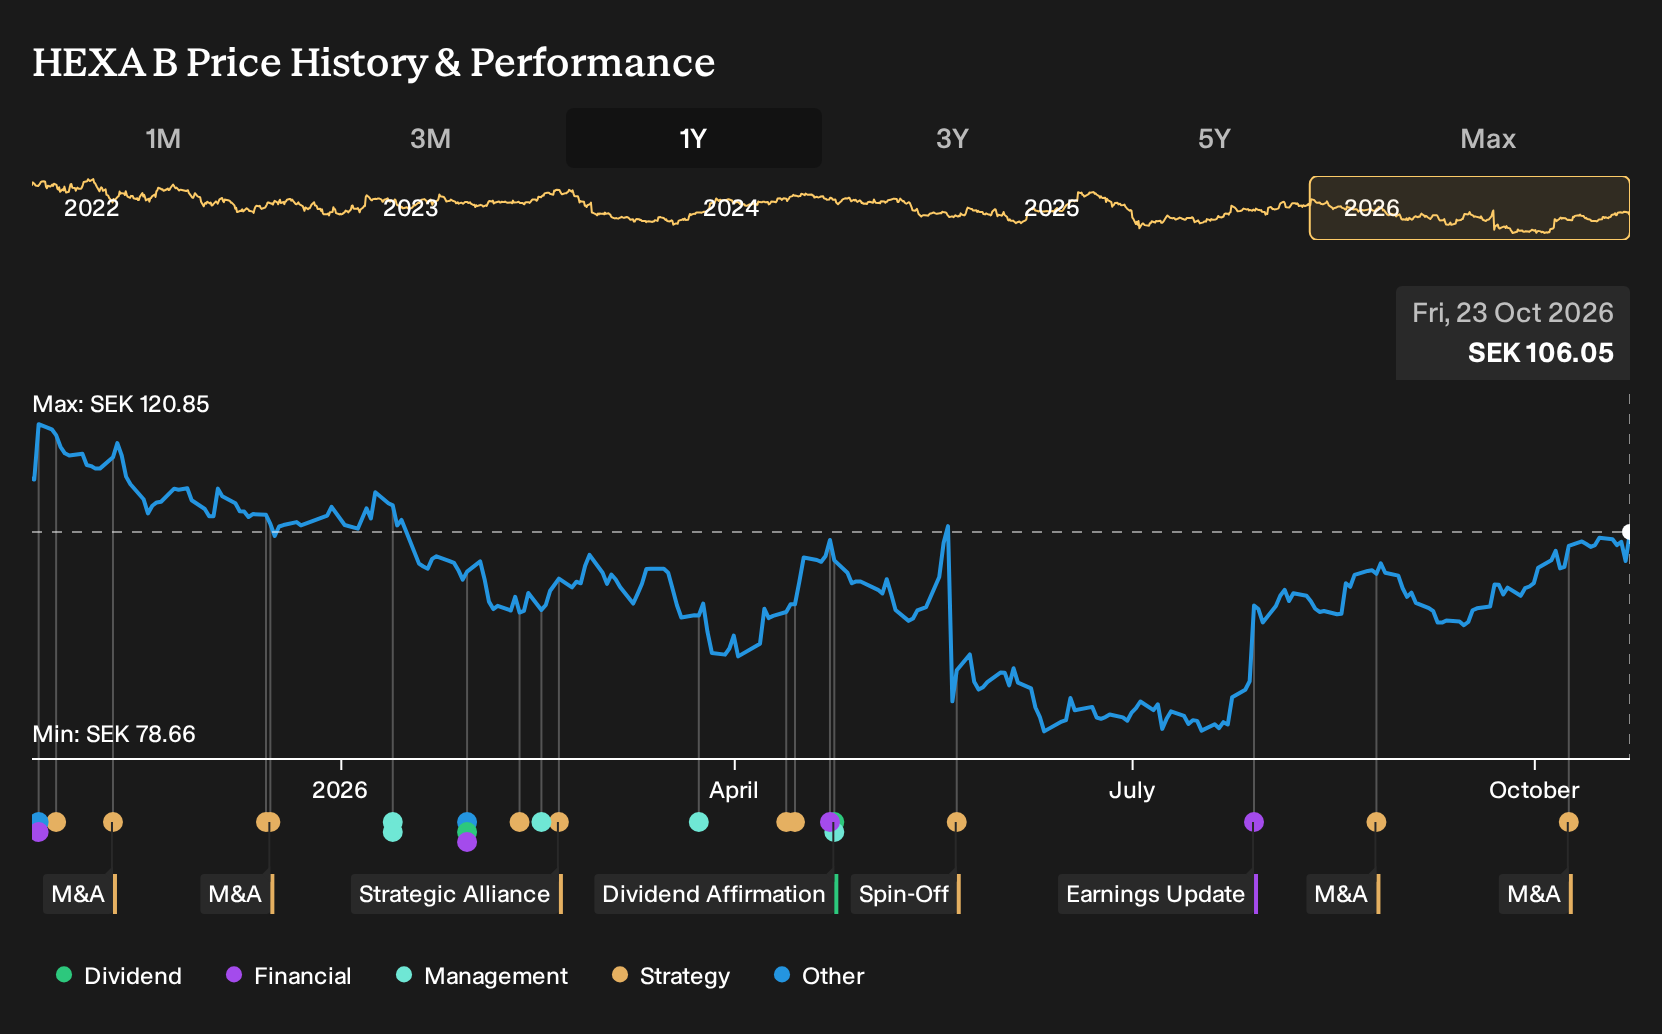
The Q3 2026 earnings release is the announcement that matters most in this context. Hexagon reported €1,049.1 million of quarterly sales and net income of €446 million, compared with a loss a year earlier. Management also highlighted support from cost savings, tariff refunds and a sizeable non recurring gain from equity investments.
For catalysts, that print provides a clearer line of sight on how the Hexagon Way cost program and higher margin autonomous and inspection activities can offset robotics and Waygate dilution. It also underscores a risk highlighted in the data that large one off items have a meaningful effect on recent profit quality and make forward comparisons more difficult.
Hexagon's consensus narrative points to revenue of €5.4b and earnings of €942.3 million by 2029, with analysts expecting fairly flat top line performance and a change in profit from €2.1b today to that lower earnings figure, which implies an earnings reduction of about €1.2b instead of growth.
Uncover why Hexagon's fair value points to a valuation that is roughly in line with its current price.
Exploring Other Perspectives
One alternate view on Hexagon stresses rising Robotics and AEON spending as the real swing factor. The most bearish analysts were pencilling in revenue of about €4.7b and earnings of €557.4 million by 2029 before this Q3 report, which is far below consensus. That gap shows how widely opinions differ. Use it as a prompt to compare several narratives rather than anchoring on just one.
Explore 3 other Hexagon fair value estimates, including one that suggests there could be as much as 20% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hexagon research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hexagon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hexagon's overall financial health at a glance.
Looking for more investment ideas beyond Hexagon?
Once you have formed a view on Hexagon, it can help to compare it with other opportunities that fit different risk, income, and quality profiles using the Simply Wall St Screener.
- If capital preservation matters most, review a focused 221 resilient stocks with low risk scores that aim to pair steadier business models with tighter risk scores.
- If income is the priority, scan a curated set of 226 dividend fortresses that combine higher yields with detailed payout and coverage data.
- If you prefer searching off the beaten path, work through a hand picked group of 613 high quality undiscovered gems that show solid fundamentals yet attract relatively little attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com