


EN
Tennant (TNC) Is Drawing Fresh Attention, So What Are Investors Missing?
P1 VAC launch puts Tennant in focus
Tennant (TNC) has drawn fresh attention after unveiling the P1 VAC, its first autonomous soft floor cleaning robot, which extends the robotics lineup into commercial vacuuming for everyday environments.
Tennant shares trade at US$66.26 after a steep 90-day share price return decline of 23.6%, and the 1-year total shareholder return of 17.5% in the red suggests recent momentum has faded even as the P1 VAC launch injects fresh attention around its robotics ambitions.
Scan beyond Tennant and compare this robotics push with other cleaning and automation players using our curated list of 95 robotics and automation stocks for potential ideas in the same theme.
Tennant now has a growing robotics story, yet its share price has fallen sharply over the past year. Does that mismatch signal a bargain or a value trap as you weigh the valuation next?
Most Popular Narrative: 24% Undervalued
The most followed narrative pegs Tennant’s fair value at $87.75, which sits well above the last close at $66.26 and frames the recent robotics news against a wider earnings and ERP story.
Accelerated adoption of autonomous mobile robots and equipment-as-a-service programs is still expanding Tennant's potential recurring revenue base, and the company now targets robotics revenue of about US$250 million in 2028 supported by 10 planned product launches and recent 56% year-over-year growth in first half 2026 robotics sales, which is likely to matter most for long-term revenue and earnings quality.
See why 12 investors see Tennant as 24% undervalued.
Result: Fair Value of $87.75 (UNDERVALUED)
Still, the Tennant story can break if ERP rollout issues continue to disrupt operations or if rising low cost competition in EMEA keeps pricing under pressure.
Find out about the key risks to this Tennant narrative.
Another View: Tennant Looks Expensive On Earnings
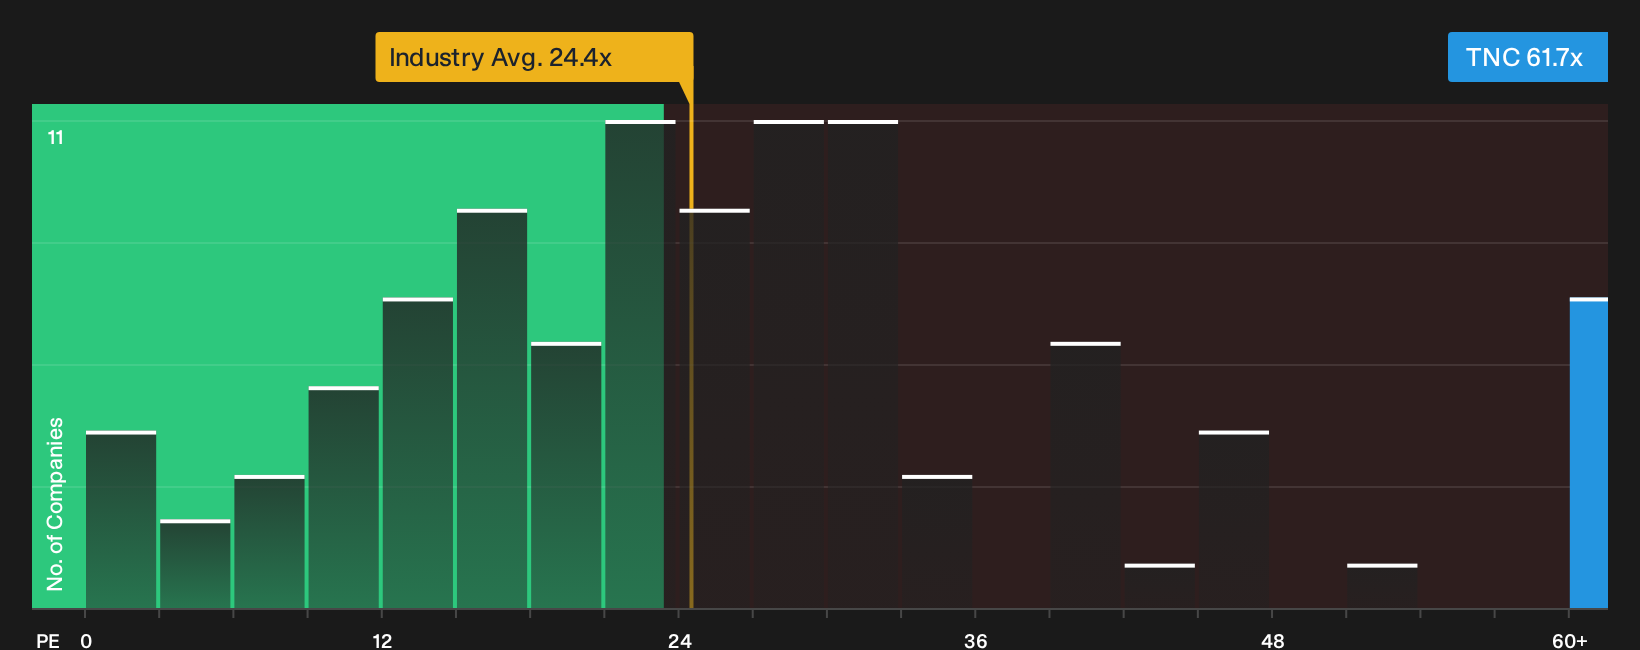
The first story paints Tennant as undervalued, yet its P/E of 61.7x tells a different story when stacked against the US Machinery industry on 24.4x and direct peers on 25.5x. Even versus a fair ratio of 54.2x, the current multiple leaves little room for disappointment.
That kind of gap can work in your favour if everything plays out perfectly, or it can amplify downside if earnings or sentiment slip a little. Which side of that tradeoff fits your risk tolerance as you weigh Tennant against other options in the sector?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Tennant's valuation story do not have to leave you stuck on the sidelines, especially when fresh data is right in front of you. Act while the facts are current, review the full balance of potential upside against the issues investors are worried about, and weigh the 3 key rewards and 4 important warning signs.
Looking for more Tennant investment ideas?
If Tennant has your attention, do not stop at a single ticker when you can scan fresh opportunities that might better match your risk and return goals.
- Target higher potential upside by comparing Tennant against a broader pool of quality opportunities using our 29 high quality undervalued stocks.
- Strengthen portfolio resilience and limit unpleasant surprises by filtering for sturdier balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Spot future contenders before the crowd catches on by scanning our 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com