


EN
Why Freeport-McMoRan (FCX) Is Back In The Spotlight
Freeport-McMoRan (FCX) is scheduled to release its third quarter 2026 earnings before the opening bell on October 27, with management expecting favorable copper prices along with higher unit costs and softer sales volumes.
Freeport-McMoRan’s share price has eased in recent weeks, with a 7-day share price return of down 6.27% and a 30-day move of down 9.86%. However, the year-to-date share price return of 25.52% and 1-year total shareholder return of 59.02% point to momentum that has cooled rather than reversed, as the market weighs strong copper pricing against softer expected volumes and higher costs.
Scan how Freeport-McMoRan stacks up against hand-picked peers by running the 16 top copper producer stocks on Simply Wall St before the next earnings print lands.After a sharp run over the past year followed by a cooler month, Freeport-McMoRan now trades at a clear discount to both analyst targets and intrinsic estimates. Is that gap signaling opportunity, or a call for restraint on expectations?
Most Popular Narrative: 18% Undervalued
Against a last close of $65.18, the most followed narrative pegs Freeport-McMoRan’s fair value at $79.07, using an 8.99% discount rate and tying the upside case directly to copper volume projects now in motion.
Freeport-McMoRan’s large above-ground copper stockpiles and progress with new leach additives and heated solutions, already producing around 200 million pounds per year with a target of 800 million pounds annually within 3 to 4 years, point to potential low incremental cost volume growth that could support higher future revenue and structurally lower unit net cash costs.
See why 113 investors see Freeport-McMoRan as 18% undervalued.
Result: Fair Value of $79.07 (UNDERVALUED)
Still, the narrative can crack if Grasberg or the Indonesian smelters hit fresh delays, or if higher Bagdad capital costs further squeeze projected project returns.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View: Freeport-McMoRan Through The P/E Lens
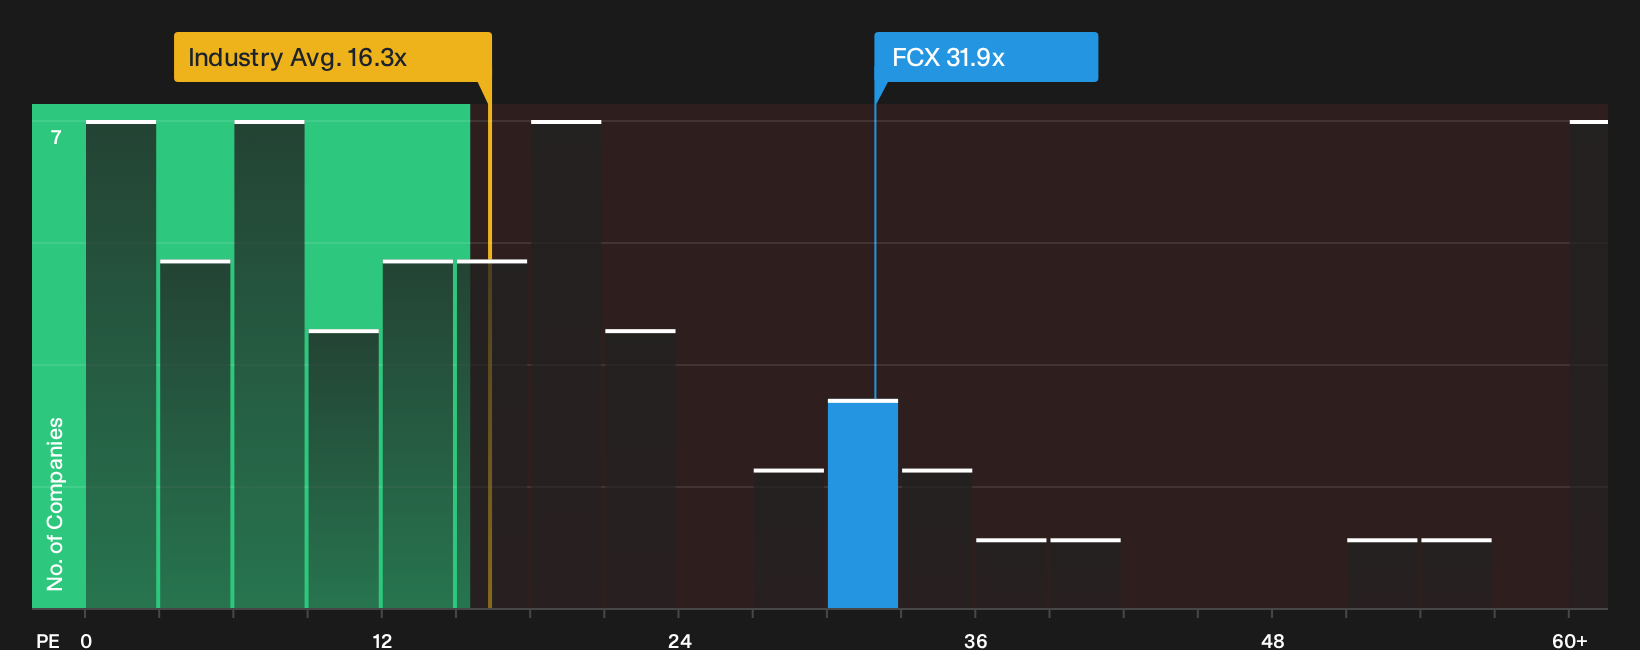
That 18% undervaluation story runs into friction once you look at Freeport-McMoRan through its P/E. The shares trade around 31.9x earnings, compared with 18x for peers, 16.3x for the wider US Metals and Mining group, and a fair ratio estimate of 28.2x. Is the premium a cushion or a cliff for future returns?
To see how those valuation gaps line up against the underlying numbers, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of enthusiasm and caution around Freeport-McMoRan feels familiar, use it as a prompt to move quickly and test the numbers yourself. The easiest way to get a balanced view is to line up both sides of the ledger and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Freeport-McMoRan?
Do not stop with Freeport-McMoRan. Use the same discipline across a wider watchlist so you are not relying on a single copper story.
- Target long-term upside by scanning a 21 high quality undiscovered gems that surfaces lesser known businesses with strong fundamentals before they hit the mainstream.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that focuses on companies with robust finances that can better handle shocks.
- Dial down portfolio stress by filtering for 30 resilient stocks with low risk scores that highlight businesses with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com