


EN
BJ's Restaurants (BJRI) Stock Dropped, So What Is Driving Attention Now?
Argus cut its price target for BJ's Restaurants (BJRI) to US$62, drawing fresh attention to how the casual dining stock compares with its recent share performance and fundamentals.
Recent trading tells a mixed story for BJ's Restaurants. The share price is down 3.9% on the day, extending to a 6.0% decline over the past month and a 17.9% drop across three months. However, the year-to-date share price return of 37.5% and 1-year total shareholder return of 71.4% point to earlier momentum that has cooled as investors reassess growth prospects and risk around the current US$56.51 level.
Spot fresh opportunities with a similar risk reward profile by scanning our hand picked 29 high quality undervalued stocks alongside BJ's Restaurants after this target cut.BJ's Restaurants now trades well below the average analyst target after a sharp pullback in the share price. Is that discount pointing to mispricing, or is it a fair reflection of the risks on the table?
Most Popular Narrative: 25% Undervalued
Compared with the latest close at $56.51, the most followed narrative for BJ's Restaurants points to a fair value of $75.43, which suggests investors are weighing solid execution gains against richer expectations already reflected in the stock.
Planned acceleration of new restaurant openings based on a refreshed prototype, following gains in average unit volume, restaurant cash flow and an approximate 240 basis point margin improvement over the past two years, positions BJ's Restaurants to apply strengthened unit economics to unit growth. This is aimed at expanding systemwide revenue and cash generation.
See why 1 investors see BJ's Restaurants as 25% undervalued.
Result: Fair Value of $75.43 (UNDERVALUED)
Still, the bullish BJ's Restaurants narrative weakens quickly if digital ordering continues to lag peers or if cost pressures squeeze already modest gross margins.
Find out about the key risks to this BJ's Restaurants narrative.
Another View: What BJ's Restaurants P/E Is Telling You
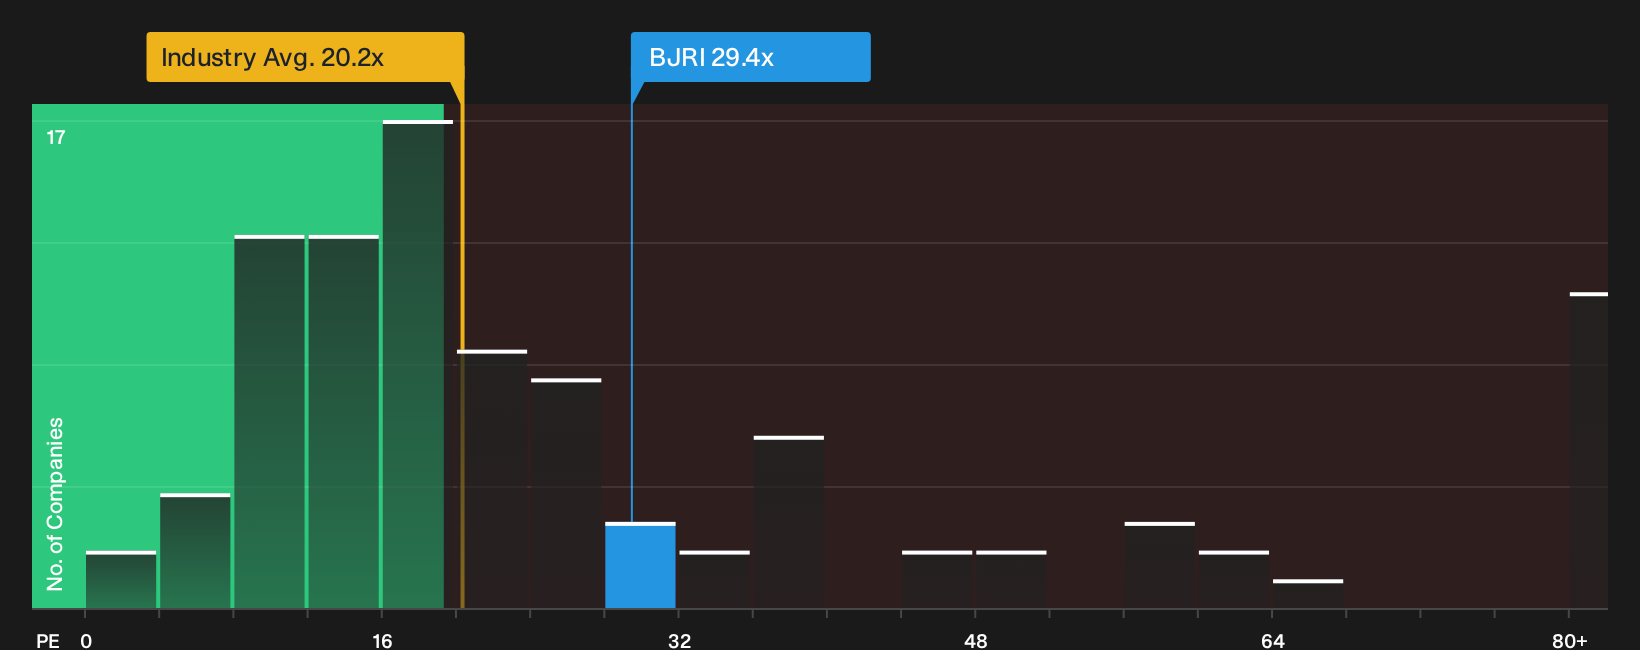
The analyst narrative presents BJ's Restaurants as undervalued versus a fair value around $75, yet the current P/E of 29.4x presents a more demanding picture. That multiple sits above the US Hospitality average of 20.2x and the fair ratio of 19.6x, even though it is below the peer average of 37.3x.
For you as an investor, that gap means paying a richer price than the wider industry for BJ's Restaurants, while still getting a discount to closer peers. The question is whether earnings growth and execution are strong enough for the P/E to remain elevated, or if the share price eventually moves back toward the fair ratio instead.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around BJ's Restaurants can feel confusing, so review the full picture promptly and form your own judgement using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BJ's Restaurants?
If you stop with BJ's Restaurants, you miss the wider opportunity set. Let the data surface fresh ideas, then decide where the real upside fits your plan.
- Target steadier compounding by scanning a 30 resilient stocks with low risk scores that aims to keep downside in check while you focus on long term gains.
- Hunt for quality at a discount through a 21 high quality undiscovered gems that highlights underfollowed companies with solid fundamentals.
- Build staying power into your portfolio by using a list of solid balance sheet and fundamentals (24 results) so weaker financial positions do not quietly drag on returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com