


EN
MasTec (MTZ) Stock May Be Below Fair Value On Earnings Power
MasTec has pulled back sharply in recent months, yet over a three year stretch the stock has still delivered a very strong return, which puts a spotlight on whether its current US$171.05 share price can be supported by the earnings power of the business. With that kind of swing in the rear-view mirror, the key issue for you is whether the construction and engineering group’s profit profile lines up with where the market values it today.
- Over the past 3 years the stock has gained 189.2%, which raises the question of whether the earnings that underpin MasTec now fully reflect that kind of move.
- For a project driven contractor like MasTec, profitability often hinges on execution quality and contract mix, which can affect how consistently it turns booked revenue into lasting earnings.
- There is a second opinion on MasTec worth weighing. See what analysts think MasTec's shares could be worth.
The issue now is whether MasTec’s share price is justified by what its earnings currently show and what they can realistically support over time.
If you want a cleaner benchmark on whether MasTec’s earnings-driven story still stacks up, it helps to compare it directly with other construction and infrastructure contractors screened through 42 power grid technology and infrastructure stocks
Is MasTec Still Cheap on Earnings?
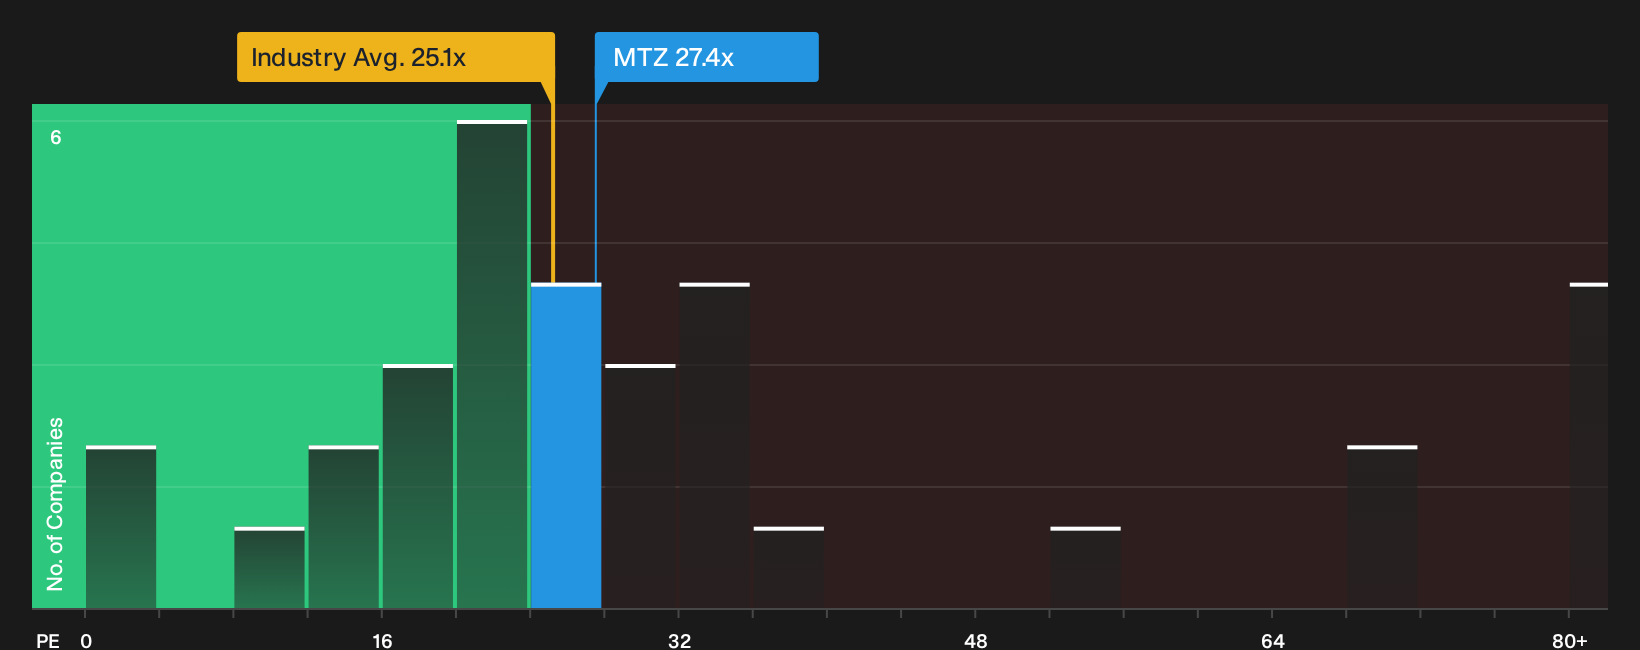
The P/E lens fits MasTec because earnings still drive most of the story investors focus on for this contractor. On that basis, MasTec trades on roughly 27.4x earnings, compared with about 25.1x for the wider Construction industry and roughly 24.5x for its peer set. That puts the stock on a premium multiple to similar businesses that also depend on project execution and capital budgets.
The internal fair-value framework, which looks at MasTec’s margins, scale, sector and risk profile, points to a higher P/E than where the shares change hands today. In other words, the current 27.4x level screens as undervalued against what that tailored benchmark implies could be justified. The gap suggests the market is applying a more cautious earnings multiple than the model, which matters if you think MasTec’s current profit base can be sustained over time. Explore the numbers behind MasTec's P/E valuation.
The MasTec Narrative: What Would Justify Today's Price?
MasTec’s valuation puzzle only really comes into focus when you spell out the future that would need to unfold for earnings, margins and contract growth to justify a meaningfully higher or lower share price than today’s. Simply Wall St Narratives on the Community page turn that idea into a set of plain, testable storylines, so instead of one ratio or model output you see the future path it assumes and can watch whether reality matches it over time.
One of the top community narratives on MasTec: 56% undervalued
"The main thing that has to go right is that MasTec converts its large ..."
Discover why this Narrative puts MasTec at 56% undervalued.
Before focusing on MasTec's valuation, there is one more angle to check
Price tags and earnings multiples only tell part of the story for MasTec, because separate research checks have flagged specific issues that deserve your attention before you lean on any valuation work. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com