


EN
Can Earnings And Grid Expansion Change The Bull Case For Nucor (NUE)?
- Nucor Corporation has already committed US$60 million to expand its Nucor Towers & Structures facility in Trinity, Alabama, adding 60 highly paid jobs and extra capacity for steel poles and related structures that support U.S. utility infrastructure.
- The Trinity expansion, alongside broader towers and structures growth, reinforces Nucor's push into higher margin downstream products tied to long duration grid and power projects.
- Next, the focus turns to how Nucor's Alabama towers expansion could reshape the existing investment narrative around downstream growth and execution.
Nucor Investment Narrative Recap
Owning Nucor means buying into a steel producer that is leaning harder into downstream products tied to long duration infrastructure work. For that to pay off, you need to see steady demand from utilities and nonresidential construction, plus clean execution on the multi year capital program. The Trinity expansion fits that playbook rather than changing it in a big way.
In the near term, the key swing factor is still how upcoming earnings stack up against guidance and recent steel price support. The biggest risk remains project execution and utilization ramp, especially at newer mills like West Virginia, if commissioning runs long or demand softens and leaves new capacity underused.
The Alabama towers project connects most directly to the existing catalyst around towers and structures, which analysts already flagged as an area expected to contribute a larger share of higher margin revenue. Extra capacity for steel poles, laydown space and galvanizing inspection gives Nucor more room to serve long run grid work if utilities keep building.
This matters alongside the broader US$15b to US$20b capital program that is moving from build to cash generation. Success here depends on Nucor keeping mills and downstream plants running efficiently while managing raw material price swings. Any stumble on new project ramp, or a drop in infrastructure related demand, would quickly test that thesis.
What The Forecasts Assume For Nucor
Nucor's narrative projects US$40.5b revenue and US$4.6b earnings by 2029. This rests on analysts factoring in 3.9% yearly revenue growth and an earnings increase of about US$1.7b from US$2.9b today.
Uncover why Nucor's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
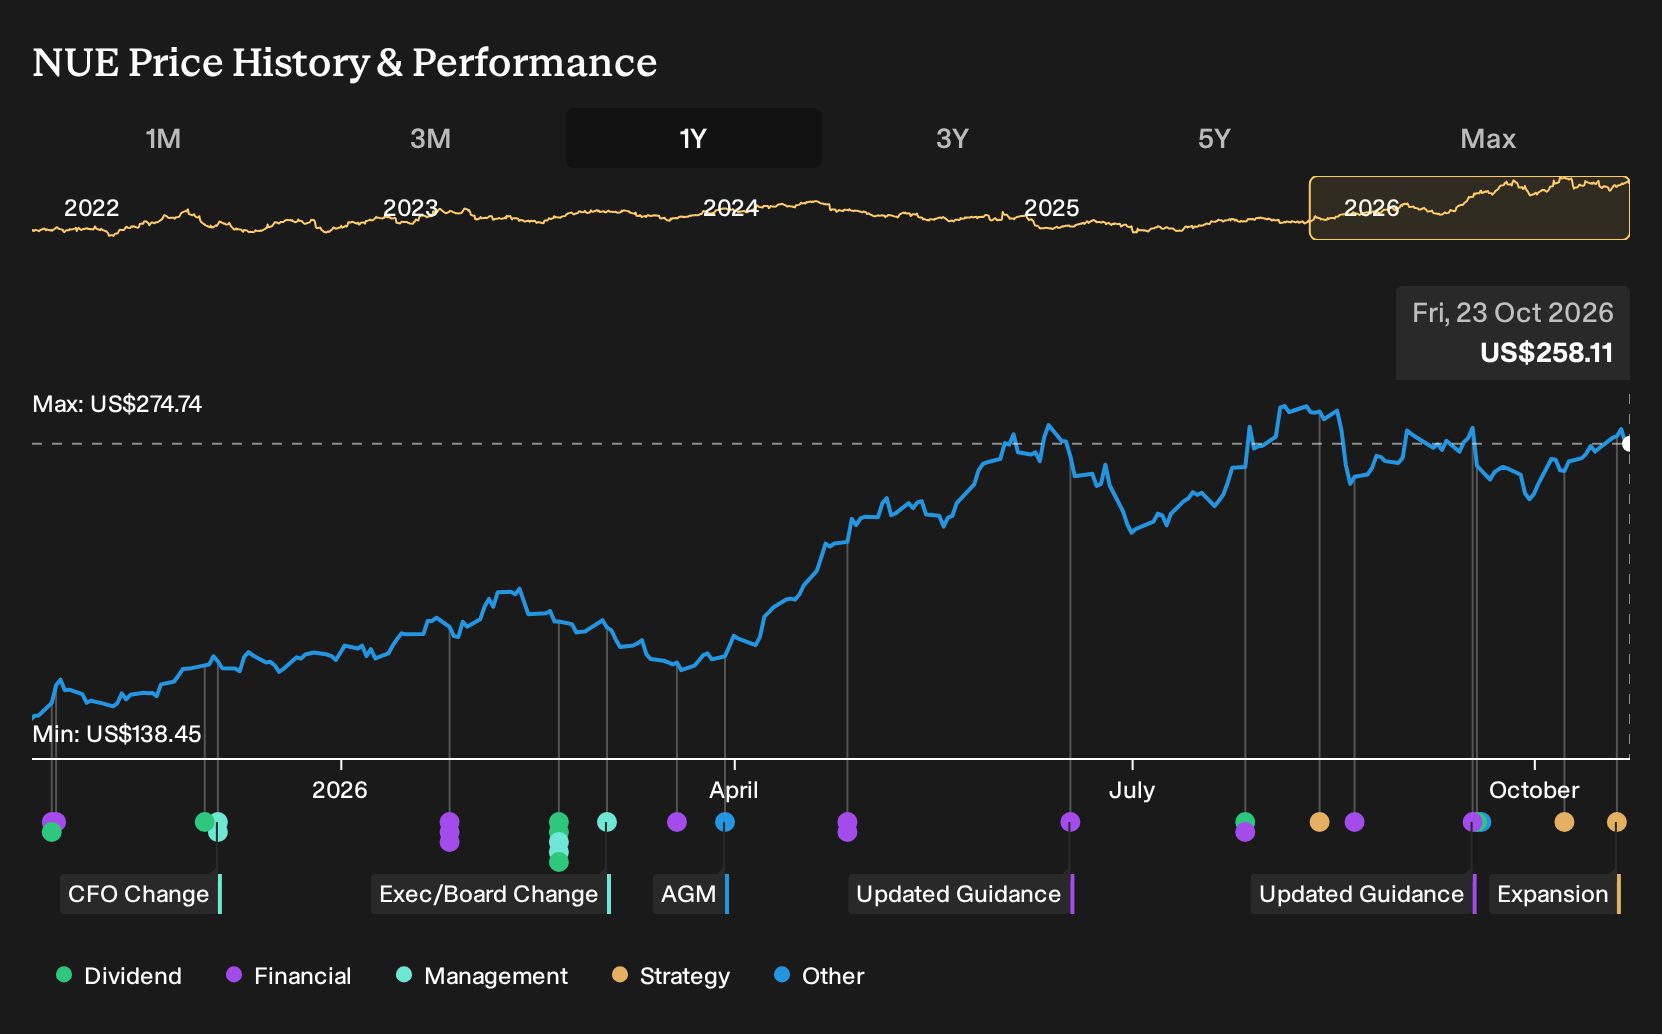
Exploring Other Perspectives
One alternate view puts Nucor's towers expansion into a much more optimistic frame. The most bullish analysts were already penciling in revenue heading toward about US$44.8b and earnings near US$5.1b by 2029. You can see how an extra US$60m grid project might nudge those expectations higher or prompt fresh debate.
Explore 3 other Nucor fair value estimates, including one that suggests as much as 63% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Nucor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nucor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nucor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nucor?
If Nucor's grid buildout story has you thinking about where else long term themes and solid execution might meet, the next step is widening your watchlist with other stocks that fit your style using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan through our hand picked 29 high quality undervalued stocks that already clear strict cash flow and balance sheet filters.
- For readers who care most about capital strength and staying power, start with a list of solid balance sheet and fundamentals (24 results) that can handle shocks without leaning heavily on fresh capital.
- Income focused investors who prefer to get paid while they wait can review a 5 dividend fortresses that screens for yields above 5% with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com