


EN
Jabil (JBL) Stock Trades At A Discount To Fair Value
Jabil has logged a very strong 363.8% share price gain over the past 5 years, and the latest pullback has investors asking a simple question. Is the current US$273.97 price still in line with what the company is earning today.
- A roughly 4.6x total return over 5 years puts a lot of weight on the idea that Jabil's earnings power can keep backing up this kind of move.
- The new 50:50 joint venture with Adani Enterprises to build AI and data center hardware in India may support expectations for future profit streams, but it can also reshape Jabil's capital needs and earnings mix over time.
- The analysts covering Jabil have run their own numbers. See what analysts think Jabil's shares could be worth.
The issue now is whether Jabil's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing Jabil against other ways to play AI infrastructure and data centers, it can help to compare it with 55 AI infrastructure stocks.
Does Jabil Look Undervalued on Earnings?
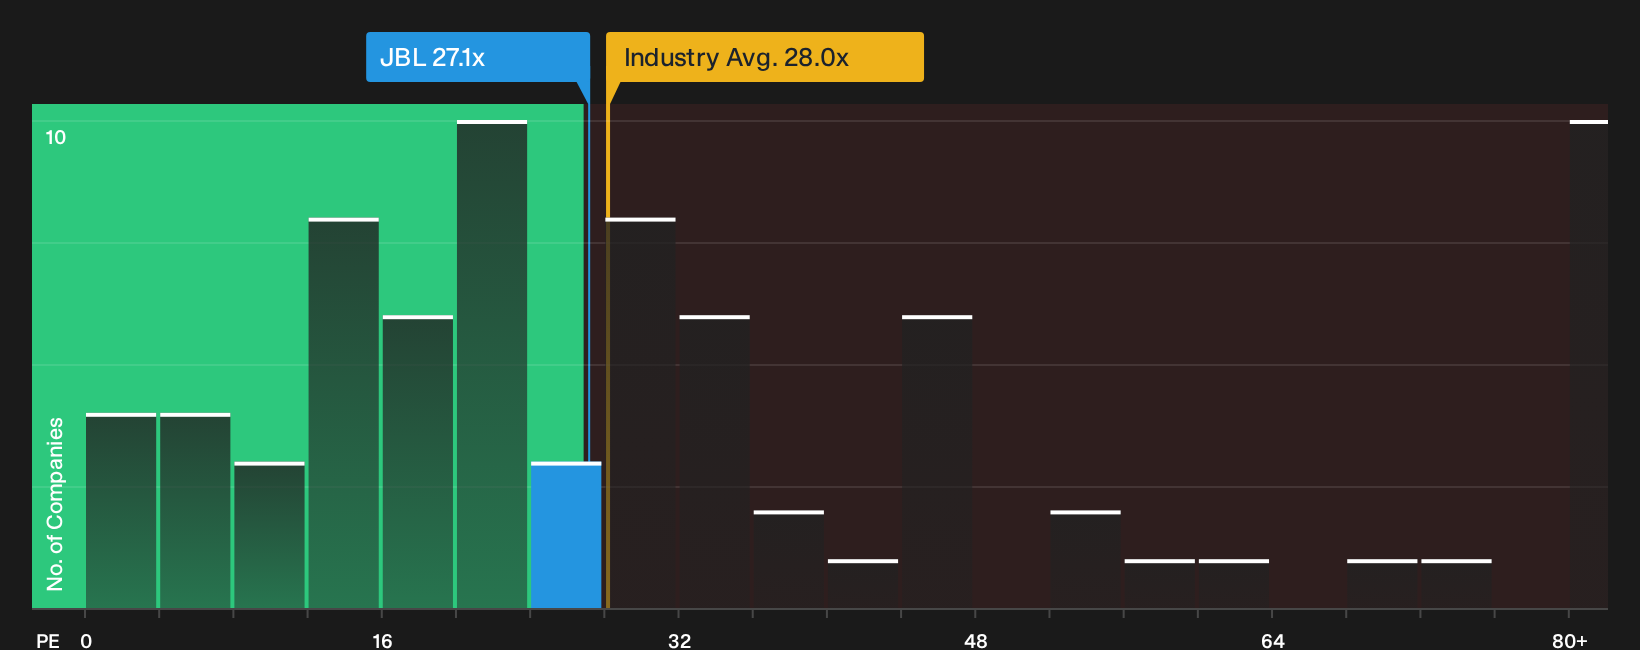
The P/E ratio fits Jabil because earnings remain the clearest anchor for how the market is pricing its manufacturing and services mix. At roughly 27.1x earnings, Jabil trades a touch below the wider Electronic industry on 28.0x and modestly above the peer group on about 25.0x. That cluster of valuations suggests investors are paying a small premium to peers for each dollar of profit, but not one that departs from sector norms.
Because the current P/E sits below the Fair Ratio benchmark implied by Jabil's own economics, the multiple appears undervalued on this earnings lens. The new Adani joint venture is relevant here because, despite attention on AI hardware and data centers, the market price still leaves some headroom against what this framework indicates could be justified. Explore the numbers behind Jabil's P/E valuation.
The Jabil Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off by spelling out which expectations for Jabil's growth, margins and earnings would need to hold for the shares to be worth materially more or materially less than today. Each narrative anchors a fair value estimate to a specific storyline about Jabil's possible catalysts and risks, so you can track over time which version of events appears to be taking shape.
One of the top community narratives on Jabil: 36% undervalued
"AI related infrastructure programs, with AI revenue guided from about US$9b in fiscal 2025 to roughly US$14.4b in fiscal 2026 and US$22.1b in fiscal 2027 along with an expanded set of hyperscale customers above US$1b each, point to a growing mix of higher value Intelligent Infrastructure work…"
Discover why this Narrative puts Jabil at 36% undervalued.
The Jabil share price is only one piece of the decision
Beyond the current valuation, Simply Wall St's checks have identified potential pressure points in Jabil's profile that an owner or prospective buyer would want to weigh carefully. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com