


EN
TeraWulf (WULF), What Is Behind The Fresh Attention?
TeraWulf (WULF) is back in focus after amending its senior secured revolving credit facility, lifting total commitments to about $400 million and adding more potential capacity through an accordion feature.
The recent credit facility amendment lands after a volatile run for TeraWulf’s stock, with the 30 day share price return down 28.08% and the year to date share price return lower by 11.15%. At the same time, the 3 year total shareholder return is very large at about 9x, which hints that enthusiasm around AI data center leases and balance sheet reshaping has cooled in the short term, while the longer record still reflects earlier optimism about the company’s shift beyond pure bitcoin mining.
Scan how investors are pricing AI data center potential across the sector by checking out 55 AI infrastructure stocks as you assess TeraWulf's new funding firepower and long-term Anthropic lease.
Analysts see fair value for TeraWulf significantly above the current US$11.32 share price, yet the stock has dropped sharply since summer. Is that discount mispricing the AI lease and new credit line, or does it signal meaningful risk?
Most Popular Narrative: 65% Undervalued
The most followed valuation story pegs TeraWulf’s fair value at $32.60, far above the recent $11.32 close, and links that gap to contracted AI and power deals rather than pure crypto exposure.
TeraWulf's recent multi-billion-dollar, multi-year hyperscale hosting agreements (for example, with Fluidstack and Google) represent a shift from a pure bitcoin mining model toward diversified, contracted revenue streams in digital infrastructure. This supports higher revenue visibility and reduces sensitivity to bitcoin price movements.
See why 146 investors see TeraWulf as 65% undervalued.
Result: Fair Value of $32.60 (UNDERVALUED)
Still, the bullish TeraWulf narrative depends heavily on flawless execution of capital intensive AI projects and continued tenant strength, which could both disappoint and re-rate the story.
Find out about the key risks to this TeraWulf narrative.
Another View: TeraWulf Looks Expensive On Sales
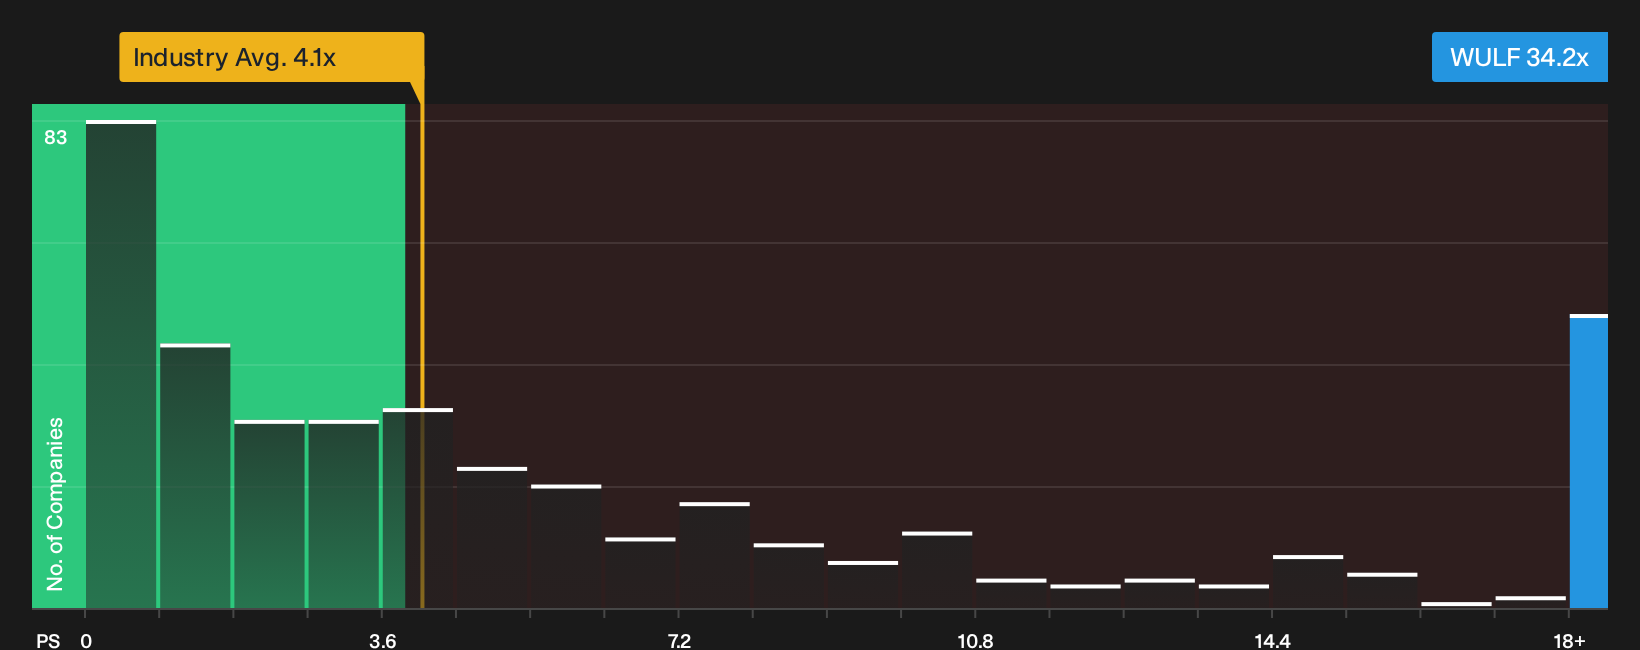
There is a very different picture when you look at TeraWulf through its P/S ratio. The stock trades at 34.2x sales compared with 4.1x for the US Software industry and 5.6x for peers, while the fair ratio sits at 16.5x, which points to meaningful valuation risk if sentiment cools.
If you lean on P/S as your yardstick, that gap raises a simple question: Is the analyst fair value story early, or already priced in twice over for a business that is still loss making?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around TeraWulf can be confusing. Move quickly to review the same valuation drivers, credit terms, and AI contracts yourself, then weigh 1 key reward and 5 important warning signs
Looking for more investment ideas beyond TeraWulf?
If TeraWulf has sharpened your focus on valuation, do not stop here. Broaden your watchlist with a few targeted filters that surface very different types of opportunities.
- Target potential mispricing by scanning companies that our models flag as high quality and trading below estimated value through 29 high quality undervalued stocks.
- Strengthen the income side of your portfolio by reviewing a curated set of higher yield payers using 5 dividend fortresses.
- Prioritise financial resilience by checking a list of solid balance sheet and fundamentals (24 results) so you are not caught off guard by weak balance sheets when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com