


EN
Did Earnings Estimates Rise Just Shift G III Apparel Group's Stock Narrative?
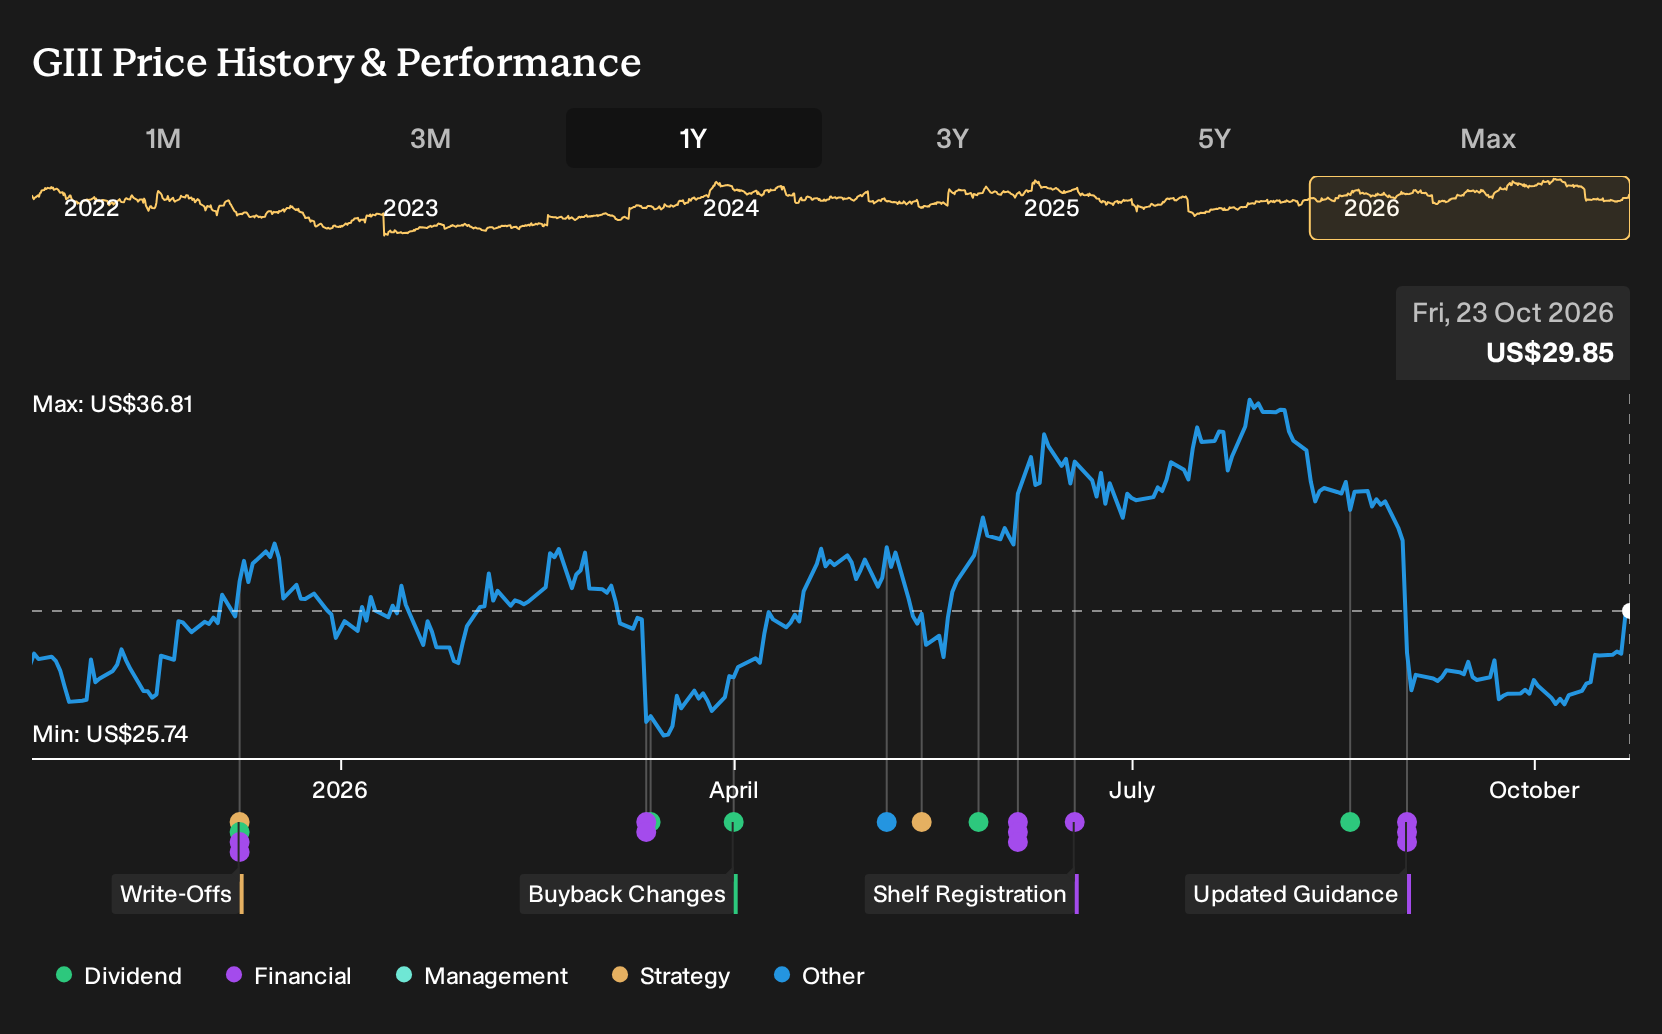
- G-III Apparel Group has recently attracted stronger analyst attention as full-year earnings estimates moved 0.7% higher over the past quarter, pointing to improving expectations for how its core apparel and accessories operations are performing.
- The business is currently outpacing the wider Consumer Discretionary sector, with G-III Apparel Group recording a 2.8% return compared with the sector’s average 10% decline, which draws focus to how its owned and licensed brands might be holding up relative to peers.
- We will now explore how this improved earnings outlook for G-III Apparel Group could influence the existing investment narrative around expiring licenses.
Scan beyond G-III Apparel Group and shortlist other potential outperformers in its broader peer group with the hand-picked 29 high quality undervalued stocks.
G-III Apparel Group Investment Narrative Recap
To own G-III Apparel Group, you need to believe the shift from expiring Calvin Klein and Tommy Hilfiger licenses toward DKNY, Donna Karan, Karl Lagerfeld and Marc Jacobs can hold up earnings even as reported revenue is expected to contract. The recent improvement in full year earnings expectations points to slightly better execution in that transition, but does not change the overall challenge.
In the near term, the key swing factor is how quickly owned labels and direct to consumer channels can fill the gap while keeping gross margin gains intact. The biggest operational risk still sits in the license roll off and any fresh disruption in supply chains or European demand, which could make already forecast earnings declines harder to manage.
With no fresh corporate announcements tied directly to this analyst sentiment shift, the most relevant reference point remains management’s broader plan to replace roughly US$1.2b of at risk license revenue, of which about US$700 million is already offset according to earlier commentary. That context matters when you see a 0.7% lift in full year earnings expectations.
You are essentially weighing whether G-III Apparel Group can keep scaling Marc Jacobs toward its long term US$1b target for the company, push more volume through dkny.com and donnakaran.com, and keep extracting cost savings that are guided to reach a US$25 million run rate by FY28. Analyst estimates moving up slightly signal some confidence in that execution, but the work of managing declining forecast earnings and traffic issues in Europe still sits firmly in front of management.
G-III Apparel Group is currently modeled on analyst assumptions that revenues reach US$2.7b and earnings land at US$97.8 million by 2029, based on an annual 2.3% decline in revenue and an earnings drop of about US$37.6 million from US$135.4 million today.
Uncover how G-III Apparel Group's fair value indicates a 16% potential upside to its current price before a discount like that starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Marc Jacobs as a potential upside swing factor for G-III Apparel Group. Before this latest sentiment shift, the bullish camp was already modeling about US$2.6b of revenue and US$110.4 million in earnings by 2029. That is a more upbeat story than consensus, and the new data could eventually push both views to adjust.
Explore 3 other G-III Apparel Group fair value estimates, including one that suggests as much as 34% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your G-III Apparel Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for G-III Apparel Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate G-III Apparel Group's overall financial health at a glance.
Looking for more investment ideas beyond G-III Apparel Group?
If you want to stress test your view on G-III Apparel Group against other potential opportunities, the Simply Wall St Screener lets you scan a wide field of companies through different lenses so you can build a list that fits your own risk and return preferences.
- For income seekers who want payouts backed by stronger fundamentals, start with a curated set of 5 dividend fortresses. This may help you focus on payout strength rather than yield alone.
- If capital preservation matters most to you right now, narrow your search to a 30 resilient stocks with low risk scores and compare how those balance sheets and risk scores stack up against G-III Apparel Group.
- When you are hunting for less crowded ideas with cleaner fundamentals, sort through a 21 high quality undiscovered gems that might not yet be widely followed by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com