


EN
T Mobile Stock Faces AI Network Breakthrough And $38 Million Customer Settlement
- T-Mobile US recently completed what Nvidia described as the first AI-RAN call on a live commercial network with Nokia and agreed to provide US$38 million in value to New York customers affected by 2024 price hikes.
- The AI-RAN milestone gives T-Mobile US an early test bed for applying AI to real-time network efficiency, while the New York settlement highlights the operational and regulatory costs tied to prior pricing decisions.
- We will now see how T-Mobile US's long term investment story could be affected by the AI-RAN progress with Nvidia.
T-Mobile US Investment Narrative Recap
T-Mobile US is still a story about turning a large 5G footprint, bundled services and AI investments into steadier cash generation. For a shareholder, the key belief is that customer growth, higher value plans and broadband adoption continue to offset heavy promotions and network spending. The upcoming third quarter 2026 report on 28 October acts as the near term check on that thesis.
The biggest swing factor right now is whether acquisition tactics like zero upfront costs and free high end devices support subscriber momentum without eroding profitability. Competitive pressure from SpaceX's Starlink Mobile and other carriers, plus regulatory and legal actions such as the New York settlement, sit on the risk side of that equation.
The New York agreement to provide US$38 million in value to customers after 2024 price hikes matters for anyone watching churn and regulatory friction at T-Mobile US. It directly links prior pricing moves to reimbursement obligations, and extends a commitment not to raise rates on certain plans until May 30, 2029.
For catalysts, that deal cuts both ways. It may help reduce near term customer dissatisfaction tied to price increases, yet it also adds evidence that plan modernization carries legal and reputational risk. Investors weighing the AI and broadband upside now need to factor in settlement costs and potential constraints on future pricing flexibility.
What The Current T-Mobile US Forecasts Assume
T-Mobile US' current analyst story leans heavily on gradual expansion rather than dramatic leaps. Forecasts point to revenue growing by 4.3% a year over the next few years, helped by the broader 5G, broadband and AI rollout. On the profit side, the consensus view is that margins rise from 11.5% today to 17.4% in three years, which is a sizeable shift in how much of each sales dollar the carrier is expected to keep as profit.
Analysts currently expect earnings to move from US$10.6b today to US$18.3b by 2029, with a wide spread of opinions around that central number. That implies an earnings increase of about US$7.7b over the period, or roughly 70% growth in absolute terms, even before layering on the expected 4.1% yearly reduction in the share count. The range between the most bullish forecast at US$22.2b and the most cautious at US$16.2b underlines how much uncertainty there still is around long term AI efficiencies, customer growth and pricing power.
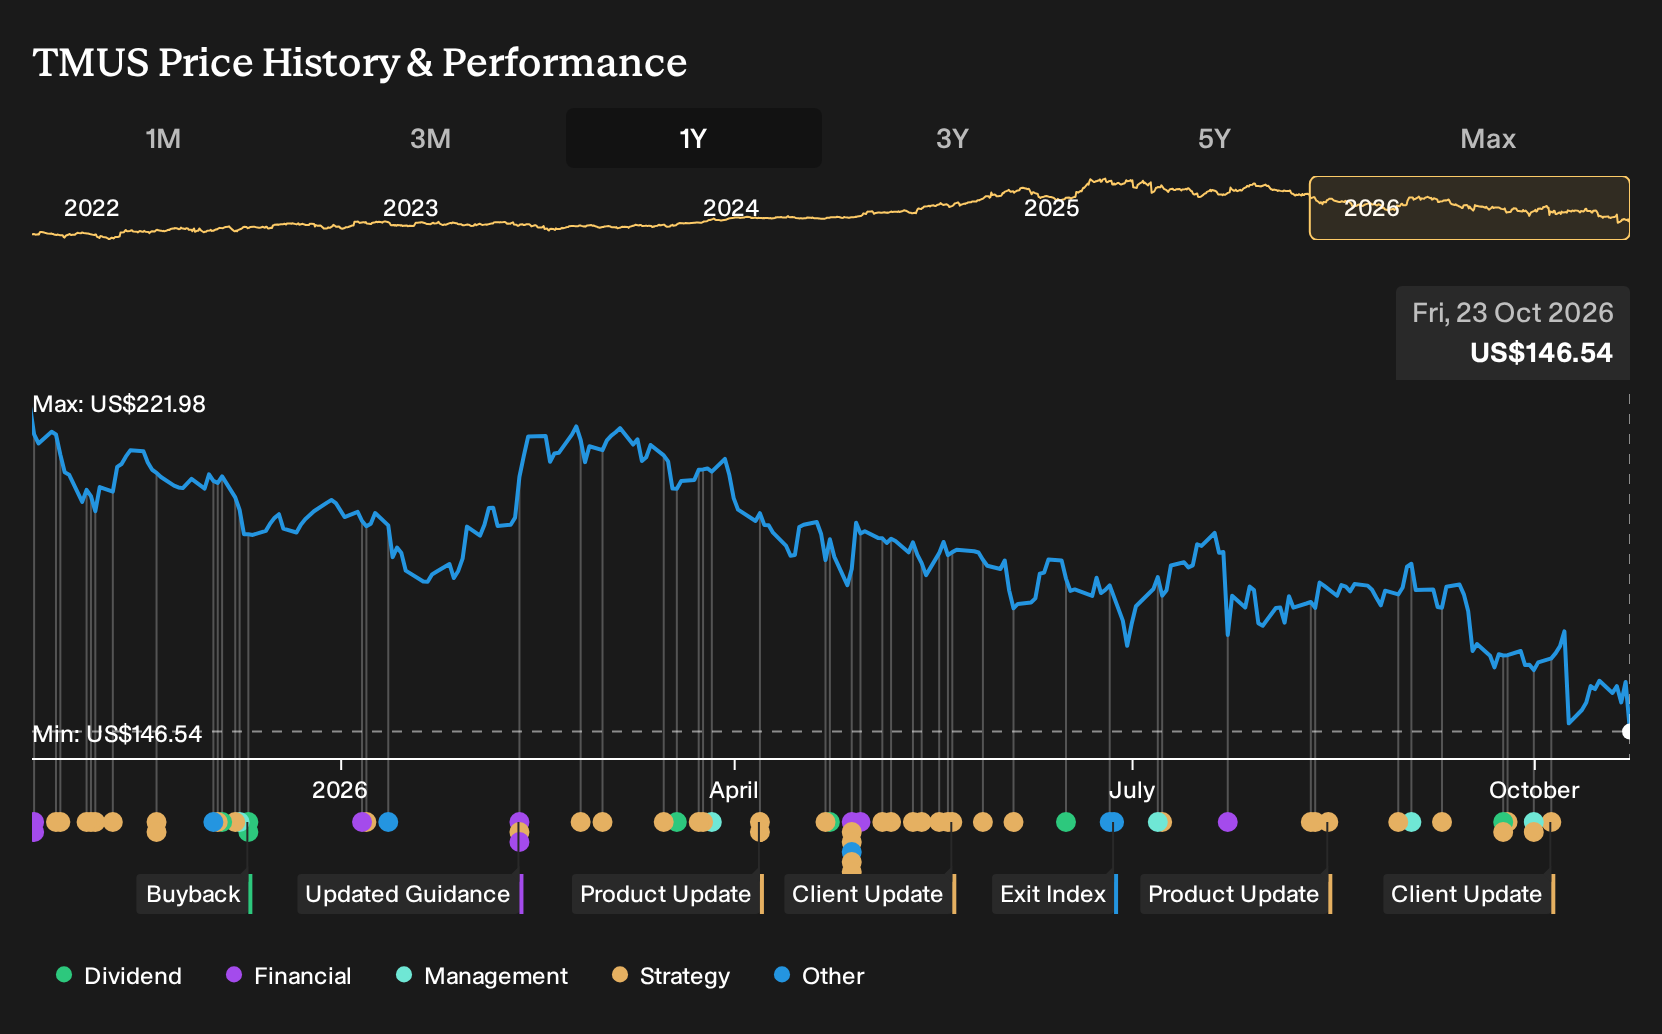
Valuation expectations sit on top of those operating assumptions. To line up with the current analyst targets, investors would need to assume T-Mobile US is earning US$18.3b on revenues of US$104.6b in 2029 and trading on a P/E of 15.1x. That multiple is slightly lower than the current 15.6x on the stock and below the 17.9x cited for the wider US wireless telecom peer group, which implies the thesis leans more on earnings growth than on multiple expansion.
T-Mobile US' narrative projects US$104.6b in revenue and US$18.3b in earnings by 2029. This requires 4.3% yearly revenue growth and an earnings increase of about US$7.7b from current earnings of US$10.6b.
Uncover why T-Mobile US' fair value indicates a 62% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For a contrasting lens on T-Mobile US, focus on the risk that heavy AI and broadband spending might deliver slower payback than hoped, even after this AI-RAN milestone. The most cautious analysts were pencilling in about US$102.3b of revenue and US$16.2b of earnings by 2029, so their story is already more restrained. Those views were set before this news, so treat them as a starting point and consider how your own expectations might shift as new information comes through.
Explore 2 other T-Mobile US fair value estimates, including one that suggests it could be worth just $236.84!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your T-Mobile US research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T-Mobile US. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T-Mobile US' overall financial health at a glance.
Looking For More Investment Ideas Beyond T-Mobile US?
If the T-Mobile US story has sharpened your view on where AI, networks and cash flows intersect, it can help to line that up against a wider watchlist. Use the Simply Wall St Screener to scan for other businesses that fit the kind of balance between growth potential, financial resilience and income that you want to target next.
- If capital protection is near the top of your list, start with companies that our models flag as relatively steady and financially robust through the 30 resilient stocks with low risk scores.
- If you want dependable income on top of price moves, focus on companies offering stronger yields and consistent payouts with the 5 dividend fortresses.
- If hunting for future market leaders appeals more, broaden your watchlist with fundamentally sound smaller players using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com