


EN
Is Compagnie de l'Odet (ENXTPA:ODET) Expensive After Q3 Revenue Jump And Bluebus Exit?
Compagnie de l'Odet (ENXTPA:ODET) just released a trading update that combined a 53% jump in third quarter revenue with a proposal to shut Bluebus production and an exceptional interim dividend.
For context, Compagnie de l'Odet’s share price has slipped over the past quarter, with a 90 day share price return down 31.22% and the year to date share price return down 28.37%, even though the 1 year total shareholder return remains positive at 3.87%.
Scan how other French-listed companies with stronger balance sheets and fundamentals are trading by jumping across to our curated list of solid balance sheet and fundamentals (205 results) while you assess Compagnie de l'Odet's latest moves.
Compagnie de l'Odet has a market value of about €4.1b, an intrinsic value estimate that sits slightly higher, and a share price that has slid hard. Is the market being too cautious after this latest update, or not cautious enough?
Preferred P/E of 39x: Is it justified?
On the latest numbers, Compagnie de l'Odet trades at a P/E of 39x, which is being applied to a share price of €967 that has fallen sharply in recent months.
The P/E ratio compares what investors are paying today for each euro of earnings. For a conglomerate that mixes oil distribution, media assets and industrial activities, that kind of earnings multiple often reflects how confident the market is in the durability and quality of profits rather than just the most recent year.
Here, earnings tell a mixed story. Profit margins sit at 3.5% compared with 36.2% a year ago, and earnings fell 90.8% over the past year after having grown very strongly on a 5 year view, while those profits are still assessed as high quality. That combination can leave investors asking whether the current P/E is pricing through a weak earnings patch, or simply assigning a rich tag to a lower return profile that includes a 0.9% Return on Equity and an underperformance relative to both the French logistics industry and the wider French market over 1 year.
The tension becomes clearer once you compare Compagnie de l'Odet's 39x P/E with reference points. The stock trades on roughly double the European logistics industry average of 19.2x and also sits well above a 19.4x peer average. That is a strong premium, and the SWS DCF model adds another angle by placing the future cash flow value at €264.96 per share compared with the current €967 price. This frames the market valuation as demanding relative to those cash flow assumptions.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 39x (OVERVALUED)
Still, the plan to shut Bluebus production and the wide gap between the DCF estimate and the current Compagnie de l'Odet share price could pressure sentiment.
Find out about the key risks to this Compagnie de l'Odet narrative.
Another view on Compagnie de l'Odet's value
The P/E premium paints one picture, but the SWS DCF model offers a very different one. On that framework, Compagnie de l'Odet's future cash flows point to a value of about €264.96 per share, well below the current €967 level. This frames the stock as expensive on this second yardstick and raises the question of which signal you trust more.
For readers who want to see how that cash flow based estimate is built line by line, it helps to walk through the full SWS DCF model before deciding how much weight to give it next to earnings multiples. Look into how the SWS DCF model arrives at its fair value.
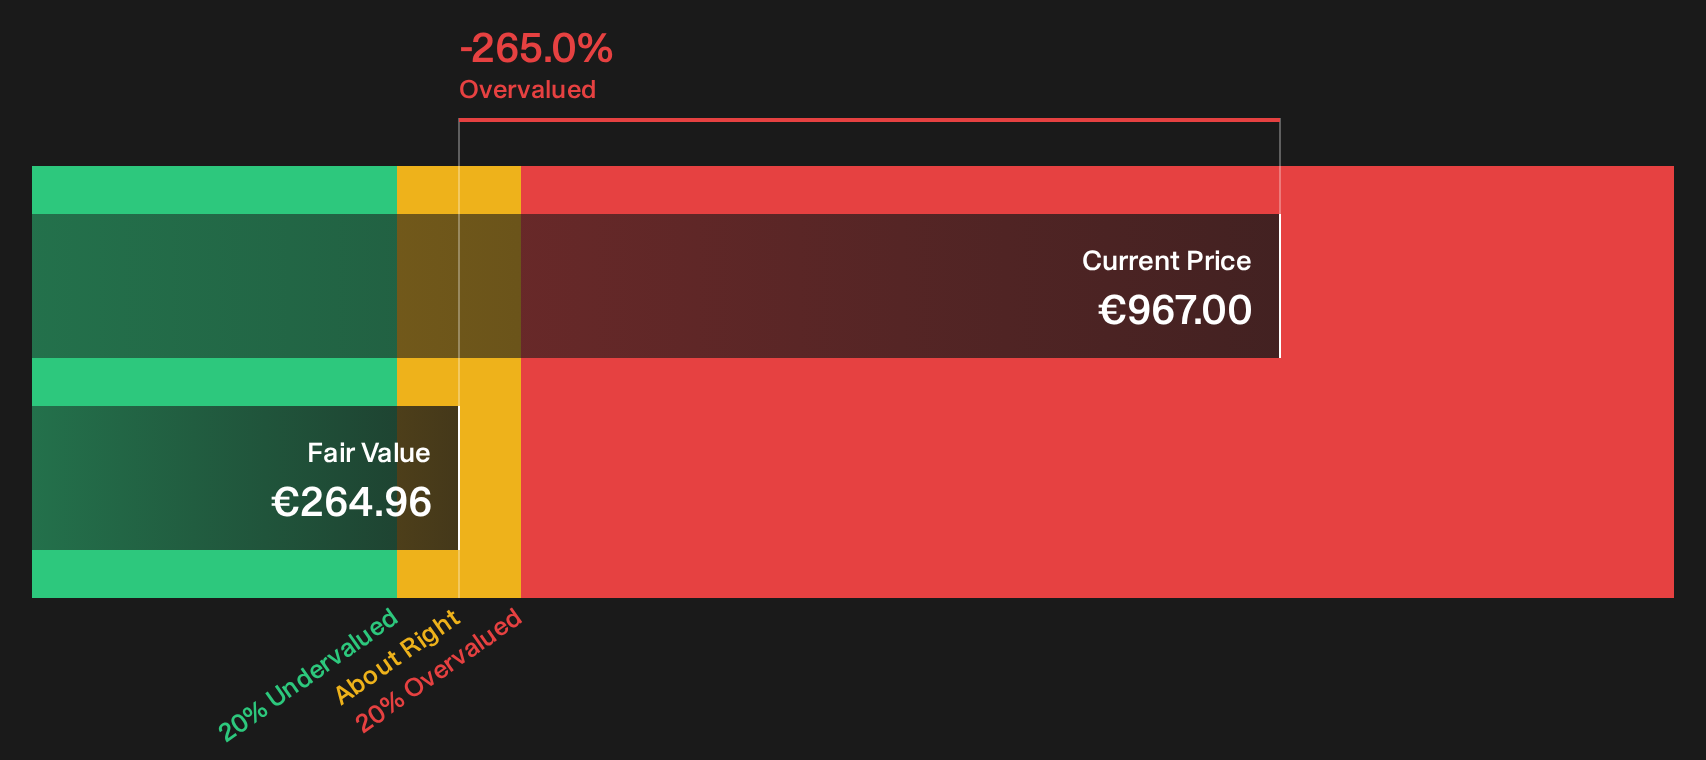
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Compagnie de l'Odet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of premium valuation and shifting operations at Compagnie de l'Odet leaves you on the fence, move quickly from headline impressions to your own assessment by reviewing the 2 important warning signs.
Looking for more investment ideas beyond Compagnie de l'Odet?
Do not stop your research with a single stock. Fresh ideas often come from comparing different business models, balance sheets and income streams side by side.
- Zero in on potential bargains by scanning companies that combine quality fundamentals with lower valuations through the 193 high quality undervalued stocks.
- Prioritise resilience by assessing businesses that score well on financial strength using the 221 resilient stocks with low risk scores.
- Highlight firms with robust finances and cleaner balance sheets by reviewing the list of solid balance sheet and fundamentals (205 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com