


EN
Did Co CEO Change Just Shift Hamilton Lane (HLNE) Investment Narrative?
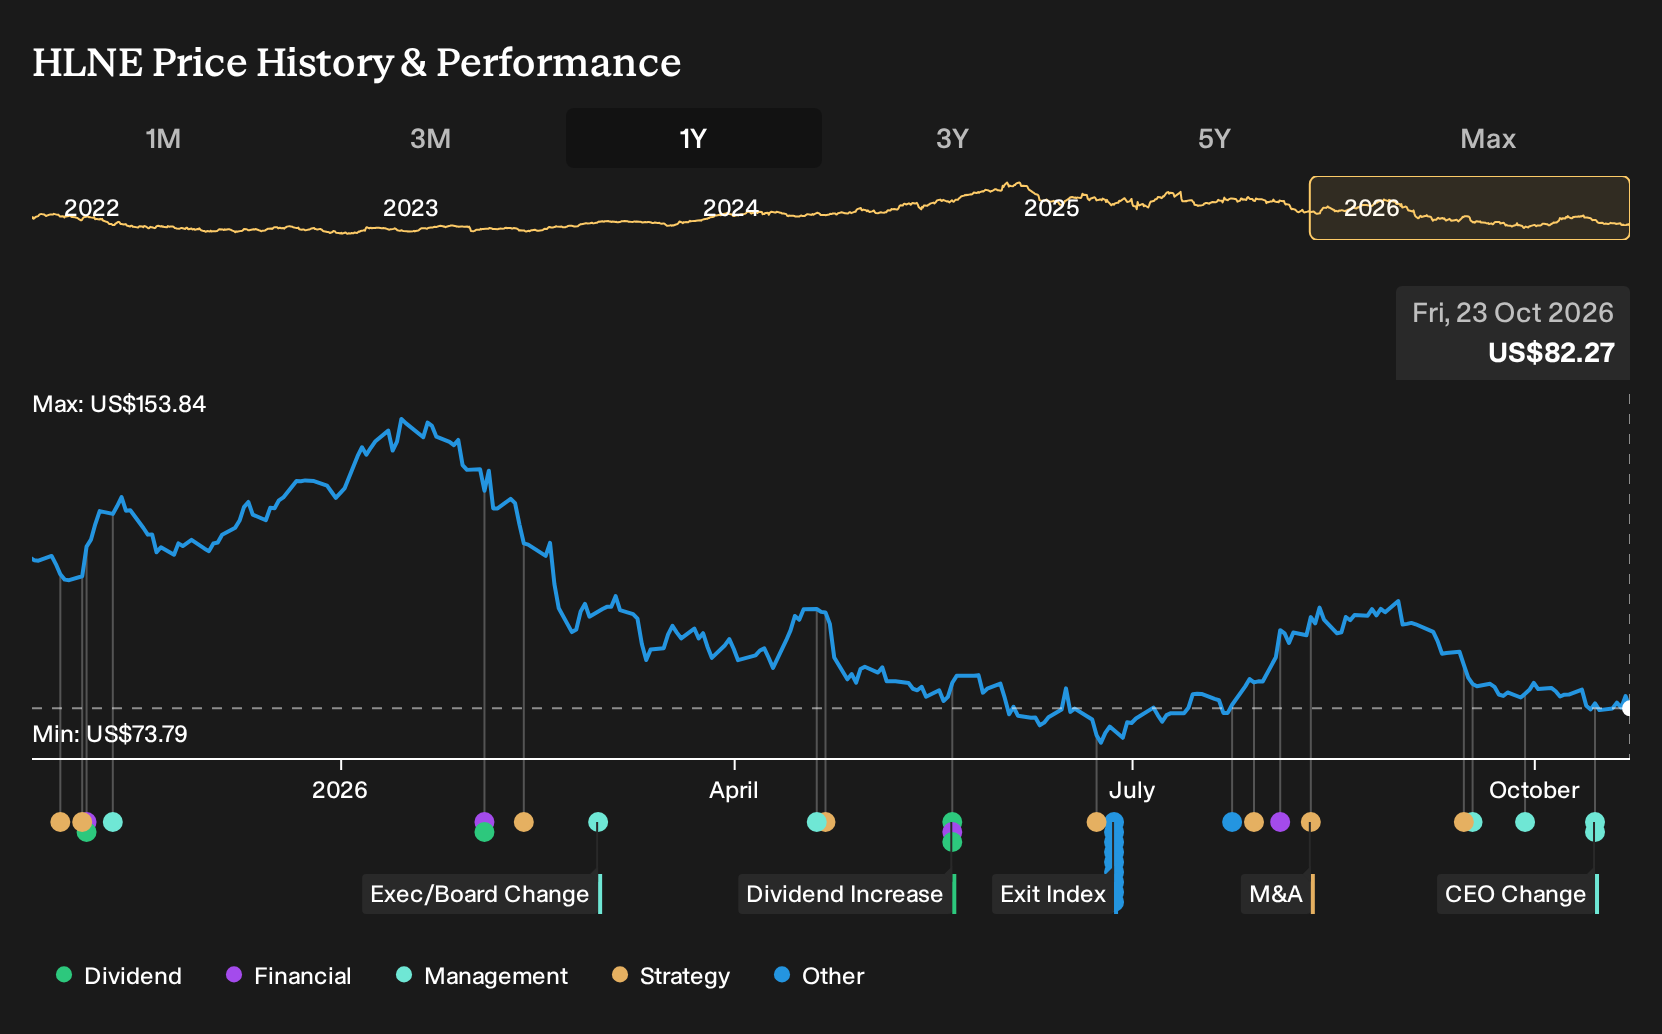
- Hamilton Lane appointed long-time director Hartley Rogers as Co-Chief Executive Officer alongside Juan Delgado-Moreira and moved former Co-CEO Erik Hirsch into an Executive Co-Chair role focused on long-term initiatives and board responsibilities.
- The reshuffle concentrates day-to-day leadership with Rogers and Delgado-Moreira while channeling Hirsch’s 25-plus years of experience into acquisitions, partnerships, and technology-focused growth projects.
- This article examines how Hamilton Lane's refreshed executive lineup, particularly Rogers returning as Co-CEO, shapes the longer-term investment narrative.
Hamilton Lane Investment Narrative Recap
To own Hamilton Lane, you need to believe its fee based private markets model can keep attracting client capital while managing regulatory pressure, competition and potential fee compression. The near term swing factor still looks tied to fundraising momentum in evergreen and customized products. This leadership shuffle, by itself, does not materially change that immediate catalyst.
The biggest current risk stays the same. Higher compliance costs and more complex structures could eat into margins if growth in fee earning AUM slows. Concentrating day to day control with Hartley Rogers and Juan Delgado Moreira may help execution, but investors should watch whether product expansion outpaces the firm’s operational capacity.
The most relevant update here is the board’s move to appoint Hartley Rogers as Co CEO alongside Juan Delgado Moreira while shifting Erik Hirsch to Executive Co Chair. For investors, this matters mainly for how Hamilton Lane runs its expanding evergreen, infrastructure and Asia oriented vehicles rather than as a pure headline about titles.
Rogers and Delgado Moreira are now clearly accountable for operating performance and global distribution, which ties directly into fee revenue. Hirsch will concentrate on acquisitions, partnerships and technology projects that could support long term efficiency. That split can influence how quickly the firm scales new channels, as well as how it manages the complexity and cost risks noted earlier.
Hamilton Lane Forecasts And What Has To Go Right
Hamilton Lane's current analyst narrative points to revenues of US$1.1b and earnings of US$496.8m by 2029. That path assumes revenue expands at 13.9% a year and earnings roughly double from US$249.2m today to reach those forecasts.
Uncover why Hamilton Lane's fair value indicates a 57% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate, more optimistic view around Hamilton Lane focuses on the Evergreen platform as a long run fee engine. Bullish analysts were already penciling in revenue of about US$1.4b and earnings of roughly US$485.2m by 2029. You might see this leadership reshuffle and wonder if those upbeat assumptions, or the consensus path, now need a rethink.
Explore 8 other Hamilton Lane fair value estimates, including one that suggests as much as 192% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hamilton Lane research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hamilton Lane. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hamilton Lane's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hamilton Lane?
If Hamilton Lane has sharpened your interest in fee based models and long term compounding, it can help to widen the lens and see how other businesses stack up on quality, resilience and income potential.
- For investors who want resilient balance sheets and fewer surprises, start with a 30 resilient stocks with low risk scores that have already cleared strict risk and quality filters.
- If dependable income matters more to you than headline growth stories, scan a curated set of 5 dividend fortresses that prioritise payout strength and consistency.
- When you want strong fundamentals without the crowd already piling in, focus on a 21 high quality undiscovered gems that pairs robust financials with relatively lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com