


EN
What Telkom Indonesia Bears Saw Before The Fall
Telkom Indonesia just reported Q2 2026 results with higher revenue and a stronger net margin than a year earlier, a type of update that often appears to support the strategic focus on broadband, data centers, and IoT. For Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia shareholders, the loss from the start of the year was 30.2%, including dividends. If you had bought on 1 January, how should this mix of operational progress and painful share performance influence expectations for Telkom Indonesia’s next phase of digital expansion?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia harder to judge, start where the gap is still open and scan 193 high quality undervalued stocks.
The Two Stories Telkom Indonesia Investors Were Choosing Between
The shares cost IDR3,470 at the start of the period, so anyone looking at Telkom Indonesia had to decide which story felt closer to reality.
The bullish narrative put Fair Value at IDR3,720. The core idea was that fast uptake of bundled digital services and IoT, supported by national digitalization programs, could help margin expansion and generate richer free cash flow for dividends and reinvestment.
The cautious storyline pointed to Fair Value of IDR3,034, using assumptions such as 12.3% revenue growth and a future P/E of 12.6x over a 5 year horizon as a ceiling rather than a stretch case.
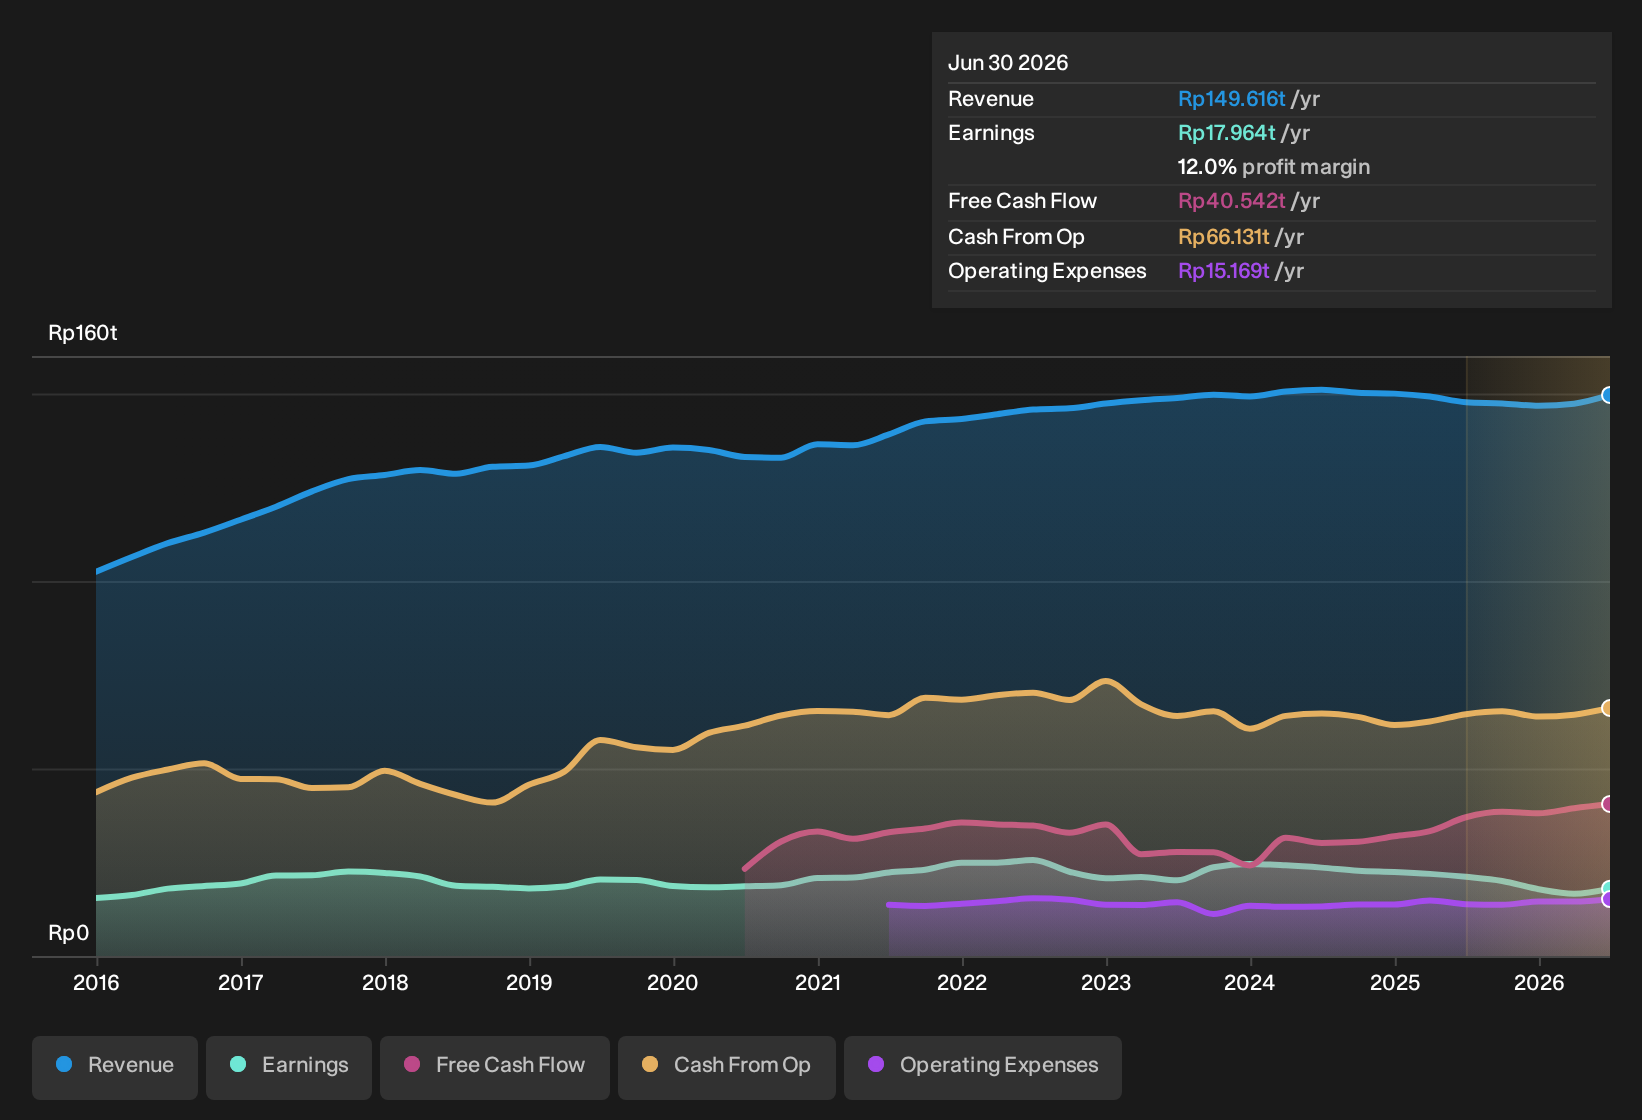
What The Results Changed For Telkom Indonesia
Revenue for Telkom Indonesia reached IDR38,689,000m in Q2 2026 compared with IDR36,365,000m a year earlier, while net income moved from IDR4,924,000m to IDR6,279,000m and net margin shifted from 13.5% to 16.2%. That pattern aligned with the more optimistic case that focused on expanding profitability and stronger cash generation.
The key assumption was margin quality. When you assess another company, check whether rising earnings come with a higher net margin on a larger top line, rather than relying only on revenue or headline profit.
What Telkom Indonesia’s Drop May Already Be Pricing In
Telkom Indonesia now trades at IDR2,240, with the Narrative’s Fair Value sitting above that level based on its own set of assumptions about the business.
The argument leans on fixed mobile convergence, group procurement and digital infrastructure. A buyer today would need to believe these moves offset pressure on legacy lines and support healthier margins over time for the fall to appear more like an opening rather than a warning.
"Telkom Indonesia's successful completion of a one-billing integration enhances fixed-mobile convergence capabilities, laying the foundation for long-term wholesale revenue growth by accelerating FMC adoption and improving customer engagement. This is likely to impact both revenue and net margins positively."
The price and this Narrative do not agree. → Uncover what this Narrative says Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia is actually worth
Looking One Step Beyond Telkom Indonesia
When you think about Telkom Indonesia, the mind usually goes straight to mobile data and broadband lines.
Look one step sideways and you find a different kind of telecom engine built on long term connectivity contracts.
This business leans on wireless and fiber to support broadband buildouts, private networks and AI driven links for large clients.
Cost programs and loyalty focused plans aim to keep those relationships stable and attractive.
If demand for richer connectivity and bundled services keeps widening, this adjacent player could influence how returns from all that network spending are shared.
That argument has a Narrative and a number behind it. → See the company one Narrative values 15% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com