


EN
Surprised By TAG Immobilien's Slide? What Investors Overlooked
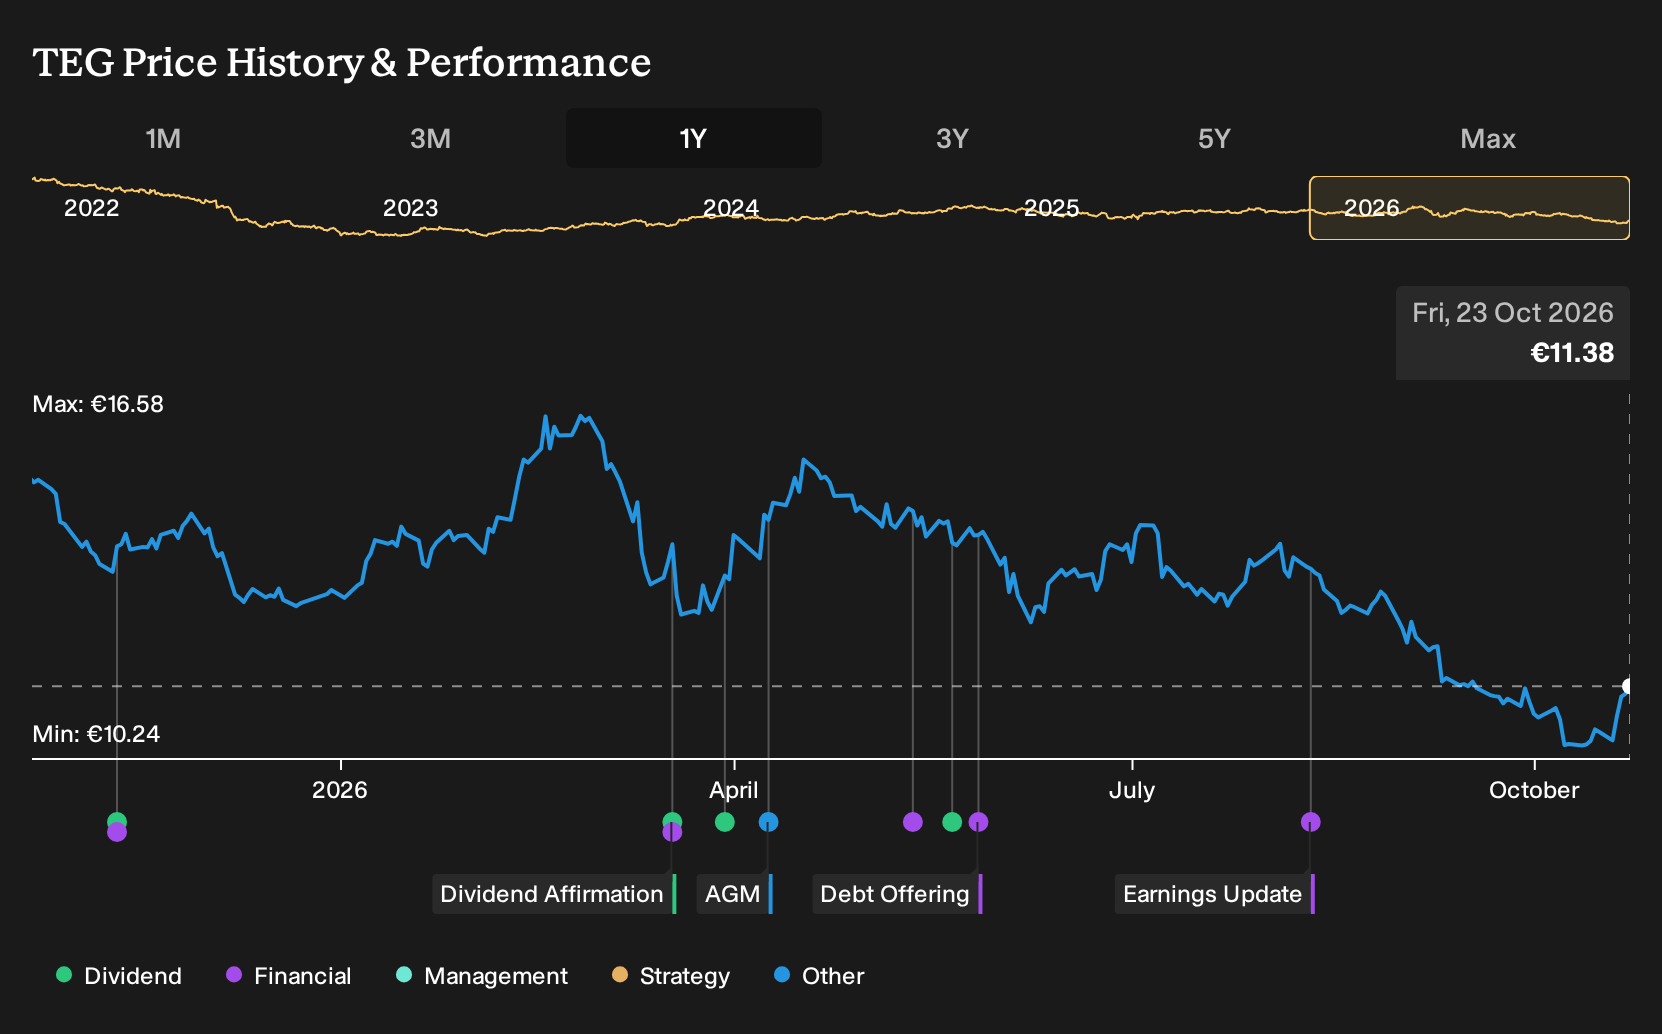
If you paused before buying TAG Immobilien in late October 2025, that hesitation avoided a painful year. Investors who held TAG Immobilien over the past year are down 23.8%, including dividends. At the time, analysts were split between upbeat German and Polish rental growth on one hand, and worries about high leverage, delayed Polish projects, and one off valuation gains on the other. If you were weighing those trade offs back then, which warning sign or optimistic assumption would you have focused on first?
TAG Immobilien has already moved. See which of 193 high quality undervalued stocks still trade below our estimates.
The Two TAG Immobilien Stories Investors Were Weighing
The shares cost €15.3 at the start, and the debate around TAG Immobilien was about whether rental growth in Germany and Poland could really carry the next few years.
The bullish story saw a Fair Value of €18.15, a price those assumptions pointed to, built on continued rental growth and portfolio modernization, plus an assumed revenue decline of 24.0% paired with an 82.5% profit margin over three years.
The bearish view pointed to a Fair Value of €13.7, based on concerns that demographic pressures and tighter regulation would curb demand, with revenue expected to fall 29.5% a year even as margins were assumed to reach 89.8%.
What The TAG Immobilien Results Actually Tested
For TAG Immobilien, the cleanest datapoint was the Q2 2026 report. Revenue was €213.599m against €207.029m a year earlier, while net income excluding extra items dropped from €110.71m to €76.449m. Net margin moved from 53.5% to 35.8%. That pattern, higher sales but weaker profitability, influenced both the optimistic and cautious interpretations of the results.
The lesson travels easily. When a thesis leans on margin expansion, you track not just revenue and profit, but the ratio between them in every set of results.
What TAG Immobilien's Lower Price Now Asks You To Believe
TAG Immobilien trades at €11.38, well below the level where earlier debates took place. The selected Narrative’s Fair Value sits above the current price and relies on the idea that rental momentum, asset values, and balance sheet strength can outweigh demographic and regulatory pressure.
For that view to hold, a buyer today would need to assume that like-for-like rental growth and Polish expansion translate into durable cash flow and support the higher Narrative figure.
"The company possesses a strong balance sheet, with a loan-to-value ratio reduced to 45.3 percent and a very healthy cash position of 870 million euros, indicating significant financial flexibility to pursue growth initiatives and withstand adverse market movements, which underpins long-term earnings stability."
The price and this Narrative do not agree. → Uncover what this Narrative says TAG Immobilien is actually worth
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 33% below our estimate - converts tax-efficient retail and regional private equity targets into fee-based inflows.
- Company 2 - 30% below our estimate - expands AI-centric B2B and video collaboration gear as consumer markets soften.
- Company 3 - 49% below our estimate - supplies AI data center power and liquid cooling as hyperscalers add capacity.
Three companies from the same screener. Open every one of the 205 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com