


EN
Swire Pacific (SEHK:19) Sees Earnings Views Improve, Is The Stock Fully Priced?
Recent analyst commentary around Swire Pacific (SEHK:19) has focused on sharply higher earnings expectations and sizeable upward revisions to consensus forecasts, a shift in outlook that traders often interpret as a fresh signal to reassess valuation.
Swire Pacific’s recent rerating has come alongside a strong share price move, with the stock at HK$103.5 and a year to date share price return of 62.48%. The 1 year total shareholder return of 63.34% and 5 year total shareholder return of 211.51% point to momentum that investors are now reassessing against these upgraded earnings expectations.
Scan how Swire Pacific’s rerating compares with other potential breakout opportunities by reviewing our hand picked list of 193 high quality undervalued stocks in similar market conditions.
Swire Pacific is now only a few HK dollars below the average analyst target, yet still flagged as trading at a discount to intrinsic value. Where does fair value really sit after a move like this?
Most Popular Narrative: 2% Undervalued
The most followed narrative currently pegs Swire Pacific’s fair value at about HK$105.46, only slightly above the latest close at HK$103.5, which puts the focus squarely on whether the long term growth plan and cash flows can support that gap.
Swire Pacific's expansion of its premium property brands (Taikoo Li, Taikoo Hui) and ongoing development pipeline in Mainland China, where demand is described as being underpinned by rising urbanization and population growth, is presented as positioning the Property division for recurring rental and trading income, supporting both revenue and earnings stability.
See why 4 investors see Swire Pacific as 2% undervalued.
Result: Fair Value of HK$105.46 (UNDERVALUED)
Still, the story around Swire Pacific can change quickly if Hong Kong and Mainland China office demand stays weak, or if aviation earnings prove more volatile than expected.
Find out about the key risks to this Swire Pacific narrative.
Another View on Swire Pacific’s Valuation
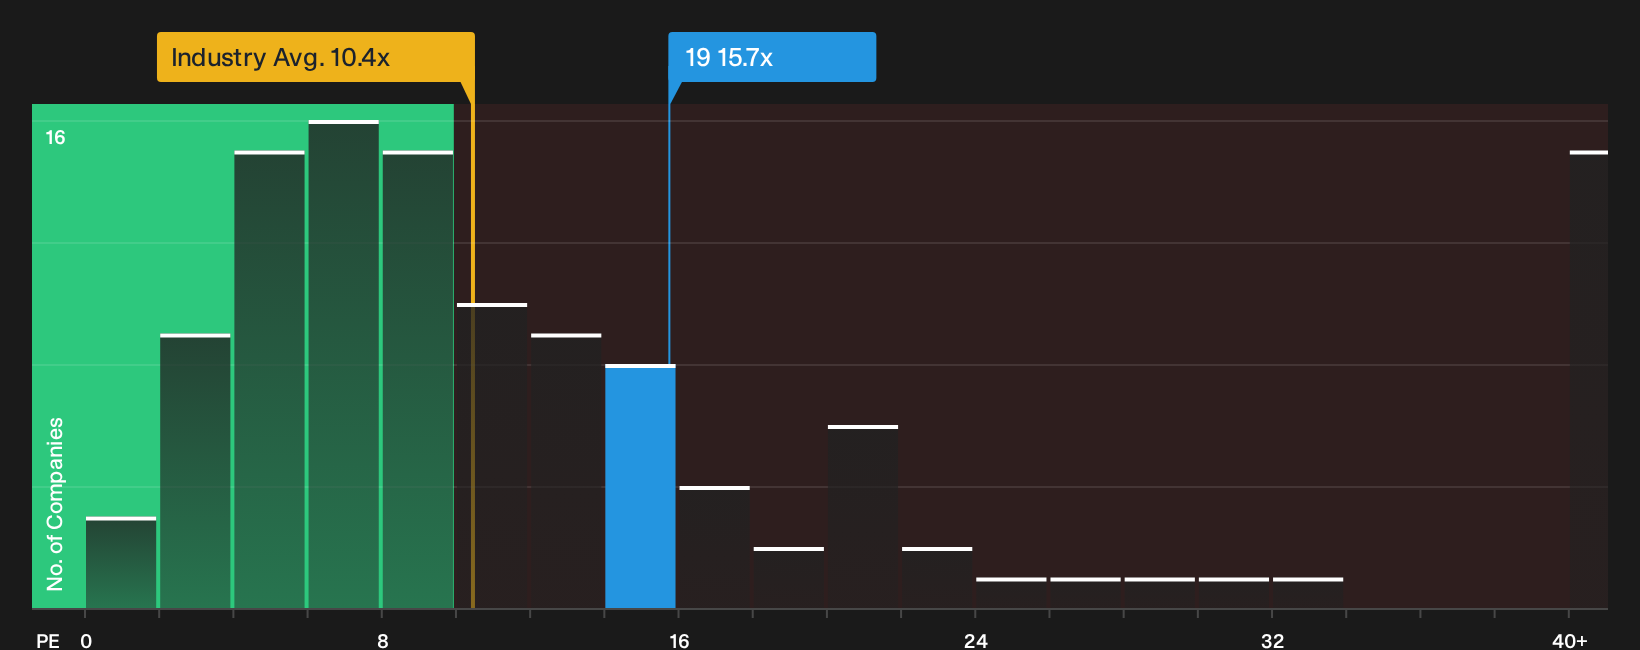
The story shifts when the focus moves from discounted cash flows to the current P/E. Swire Pacific trades on 15.7x earnings. That is well above Asian Industrials at 10.4x, a peer group at 8.7x, and even a fair ratio estimate of 9.4x.
This richer multiple suggests investors are already paying a premium for the recent rerating, while the fair ratio hints at room for that P/E to compress if expectations cool. Which signal do you trust more when the price is this close to fair value estimates?
Before leaning too heavily on any one metric, it is worth stress testing how this earnings multiple stacks up across different peers and scenarios, then weighing that against your own risk tolerance and holding period. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mix of optimism and caution around Swire Pacific match your own view, or does the balance of risks and potential rewards look different once you study the numbers directly? To test your perspective against the current data, review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Swire Pacific?
If Swire Pacific has sharpened your thinking on value, do not stop here. Broaden your watchlist with a few targeted screens that surface very different types of opportunities.
- Hunt for overlooked upside by reviewing a curated 613 high quality undiscovered gems that combines strong fundamentals with limited analyst attention.
- Prioritise resilience and sleep better at night by scanning a 221 resilient stocks with low risk scores that filters for companies with more durable profiles.
- Focus on financial strength first by working through a list of solid balance sheet and fundamentals (205 results) so you are not caught holding fragile businesses when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com