


EN
What’s Behind Frontline (FRO) Stock’s Latest Move?
The realignment of global crude trade routes due to geopolitical shifts has tightened tanker capacity and lifted shipping rates, putting Frontline (NYSE:FRO) and its long haul fleet directly in focus for income oriented energy investors.
Recent market action shows that Frontline has been on a strong run, with a 1 month share price return of 10.92% and a 90 day share price gain of 37.19%, contributing to a very large year to date share price return of 157.24% and a 1 year total shareholder return of 160.60%. Together, these figures signal powerful momentum that investors are linking to tighter tanker supply and firmer rate expectations rather than short term headlines.
Scan the crude tanker space for other potential beneficiaries of rerouted oil flows and tight capacity by reviewing our hand picked list of 29 high quality undervalued stocks.
Frontline looks tied to a powerful crude tanker story, yet the share price has already run hard in anticipation. Is this still a solid income vessel at a fair ticket, or has enthusiasm outrun value?
Most Popular Narrative: 55% Overvalued
Frontline last closed at $52.94, while the most followed narrative on the stock, according to LunaRodas, places fair value at $34.07 per share. That gap is large enough that readers focusing on income now have to weigh a stretched price against a rich tanker cycle.
TheGapReport: Frontline plc (FRO) Q2 2026 (may 22 - aug 28)
Frontline reported its August 2026 results against a backdrop it had spent the previous quarter describing as unprecedented. The May call established a framework: the Strait of Hormuz was effectively closed, the market was unlike anything in twenty-plus years of industry memory, and Frontline was navigating without a playbook. Three months later, that framework largely held, but the language around it shifted in ways worth examining. The company that described a hectic political landscape in May now describes an ocean of profits. The analytical question is what changed, what did not, and what quietly stopped being said.
See why 6 investors see Frontline as 55% overvalued.
Result: Fair Value of $34.07 (OVERVALUED)
Still, Frontline’s story could be challenged if concerns about the tanker order book grow into real oversupply, or if management’s confidence outpaces disciplined capital allocation.
Find out about the key risks to this Frontline narrative.
Another View: What Frontline’s Earnings Multiple Is Saying
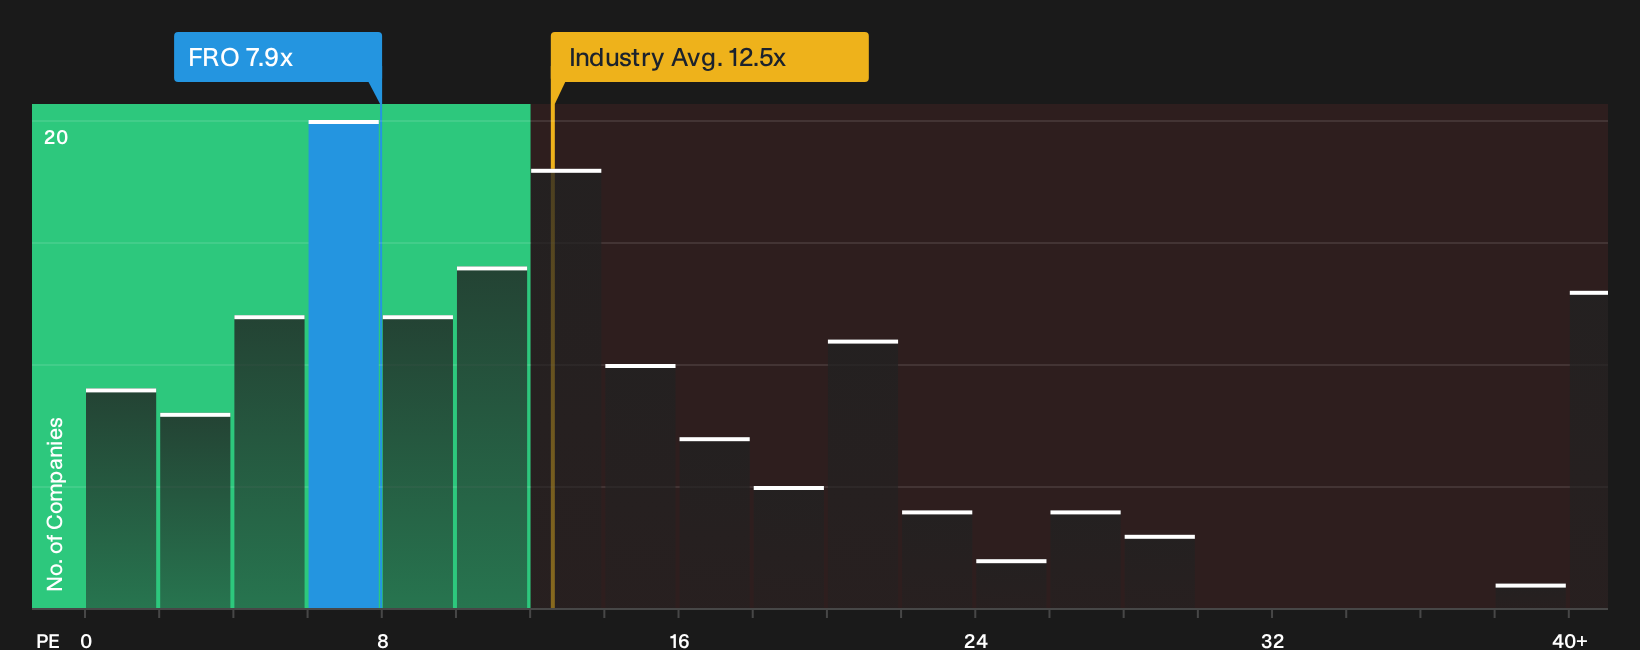
The LunaRodas narrative flags Frontline as 55% overvalued at $52.94 versus a fair value of $34.07, yet the market’s own yardstick tells a different story. On a P/E of 7.9x, the stock trades well below the US Oil and Gas group at 12.5x and peers at 22.7x, and only slightly above a fair ratio of 7.2x. That gap suggests less margin of safety if earnings cool, but also leaves room if the market leans closer to peer style pricing.
For investors asking whether the current price is stretching beyond what earnings support or simply reflecting a different read of risk, the valuation breakdown can sharpen that view. In particular, it may help clarify how far the P/E might drift toward the fair ratio or industry levels over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Momentum, valuation tension and mixed signals on Frontline create a charged backdrop. Move quickly to test the numbers yourself and stress test the thesis using 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Frontline?
If Frontline has sharpened your focus on where capital can work harder, broaden the opportunity set by scanning other setups that fit your risk and income goals.
- Target resilience first by reviewing a 30 resilient stocks with low risk scores that filters for businesses built to handle tougher conditions without wild swings.
- Hunt for dependable cash returns through a curated pool of 5 dividend fortresses that prioritise income strength alongside balance sheet support.
- Spot early stage upside by checking a focused group of 7 elite penny stocks with strong financials where solid fundamentals meet higher return potential for patient investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com