


EN
eBay (EBAY) Cuts 9% Of Staff, Is The Upside Already Priced In?
eBay (EBAY) has moved sharply into cost cutting in 2026, with a new decision to reduce its global headcount by about 9% as part of a wider restructuring plan.
eBay’s latest restructuring headlines land after a strong run, with the share price at US$121.41 and a year to date share price return of 39.46% suggesting momentum has been building rather than fading. The 1 year total shareholder return of 26.50% and very large 3 year total shareholder return above 200% frame these job cuts as a late stage move in a longer rerating story. The double digit 30 day share price return hints that investors have been reassessing both earnings power and risk as expectations for higher revenue and free cash flow filter into sentiment.
Scan how other consumer and ecommerce platforms are reshaping their cost base and pricing power with our curated 29 high quality undervalued stocks, which share stronger balance sheets and free cash flow support than many headline stocks.
Bulls see eBay using fresh cost cuts to squeeze more cash out of a premium rated marketplace. Bears see late cycle pruning after a long rerating. Which case does the current valuation actually back up?
Most Popular Narrative: 15.7% Overvalued
On the most widely followed valuation view, eBay’s recent close of $121.41 sits above an implied fair value of $104.94. This puts the current cost cutting push against a richer starting point than headline multiples alone might suggest.
This is not a standalone acquisition. It is the second to last step in a multi year, traceable architecture: PSA partnership (May 2024), Turner board seat (November 2024), PowerPacks JV (March 2025), Power Packs trademark (July 2025), Cohen 100 billion performance award (January 2026), eBay bid (May 2026), then (implied) Collectors acquisition, then (implied) tZERO integration. The eBay filings only show one move on a much larger board.
See why 4 investors see eBay as 16% overvalued.
Result: Fair Value of $104.94 (OVERVALUED)
Still, this GameStop convergence story around eBay could falter quickly if financing terms tighten or if regulators scrutinise the concentration of collectibles more aggressively.
Find out about the key risks to this eBay narrative.
Another View: What eBay’s P/E Is Really Saying
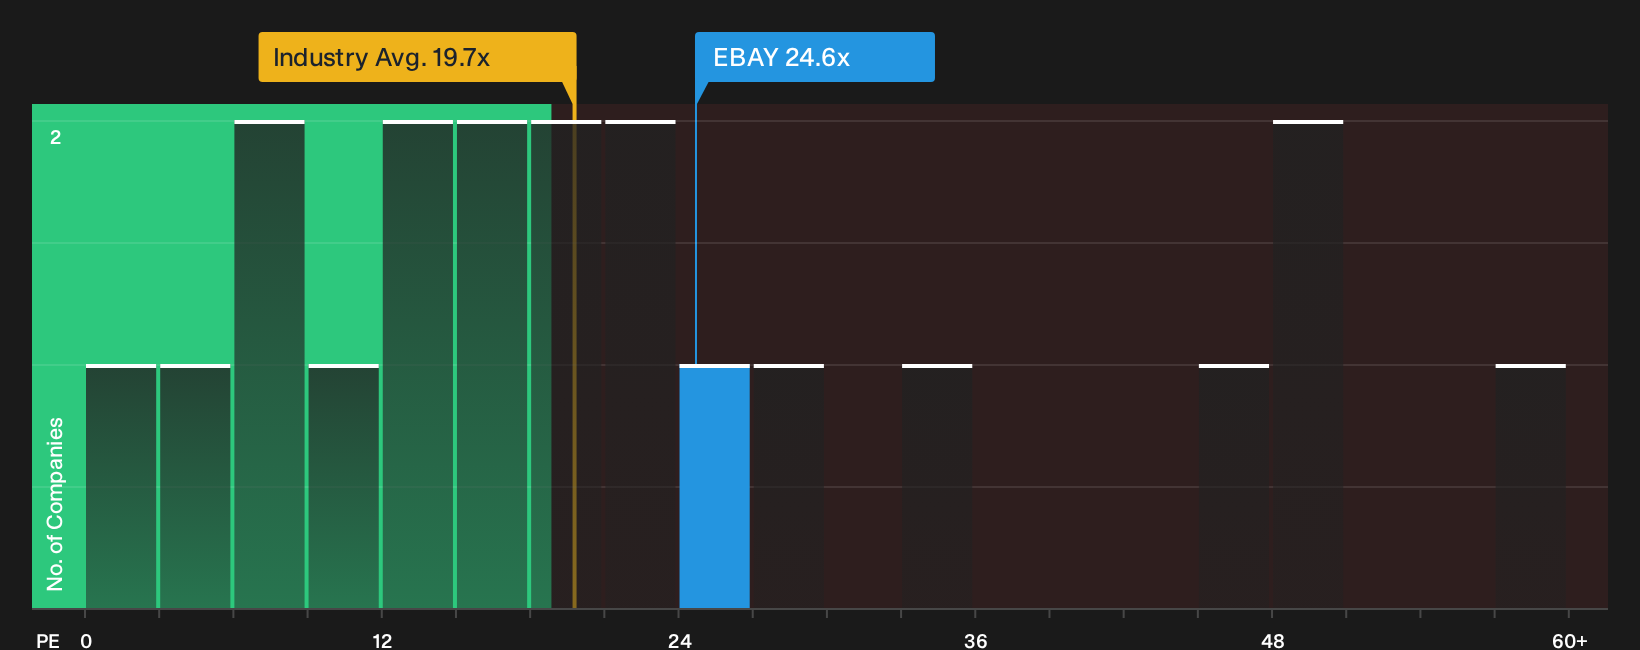
The first narrative paints eBay as 15.7% overvalued versus an inferred fair value of $104.94. On simple earnings multiples, the picture changes. eBay trades on a 24.6x P/E, only slightly below peers at 25.2x, yet meaningfully above a fair ratio of 19.5x that the market could gravitate toward.
That gap suggests investors are paying a premium that recent profit trends and forecast growth may struggle to justify, especially with net margins easing from 20.8% to 18.3% and earnings growth running behind both the Multiline Retail industry and broader US market. If the story behind that richer multiple weakens, how much multiple compression risk are shareholders really comfortable with?
See what the numbers say about this price in our valuation breakdown, then decide how you want that trade off between premium and risk to look in your portfolio See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this combination of optimism and caution around eBay feels familiar, consider it a cue to act promptly and evaluate the evidence for yourself while sentiment is still fresh. Start by assessing both the potential upsides and the noted downsides through 3 key rewards and 1 important warning sign.
Want more ideas beyond eBay?
Ready to widen your watchlist with fresh, numbers first ideas that could complement or contrast your view on eBay without guessing where the market goes next?
- Target punchy upside potential with carefully filtered opportunities using our focused 7 elite penny stocks with strong financials so you are not relying on hype alone.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (24 results) that puts financial resilience and fundamentals at the center of your next decision.
- Hunt for under the radar potential before the crowd catches on by scanning 21 high quality undiscovered gems that already show solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com