


EN
Metro (HMSE:B4B0) Could Be 81% Below Fair Value Following Its Valuation Check
Metro (HMSE:B4B0) shares have drawn attention after recent trading left the stock at €7.24, with year to date performance and valuation metrics giving investors fresh context for this wholesale-focused retailer.
Recent trading shows that Metro’s 1 day share price return declined 1.36%, although the year to date share price return of 26.57% and a 1 year total shareholder return of 32.60% indicate that momentum has been building rather than fading.
Track how Metro fits into the wider wholesale and retail rebound by scanning our hand picked 193 high quality undervalued stocks.
The sharp year to date gain in Metro, alongside a fresh daily drop, raises a simple puzzle. Does this price now echo improving fundamentals, or a swing in sentiment that valuation can test next?
Preferred Multiple of 0.1x P/S: Is it justified?
Metro screens as inexpensive on its preferred yardstick, with a P/S ratio of 0.1x, compared with peers on 0.2x and the wider European consumer retailing group on 0.4x, despite the last close sitting at €7.24.
The P/S ratio compares the market value of the equity to annual revenue, which can be a useful reference for wholesalers where sales volumes are large and profit margins can be thin or even negative. For Metro, investors are paying roughly €0.10 in equity value for each euro of the €33,139.0m in yearly revenue.
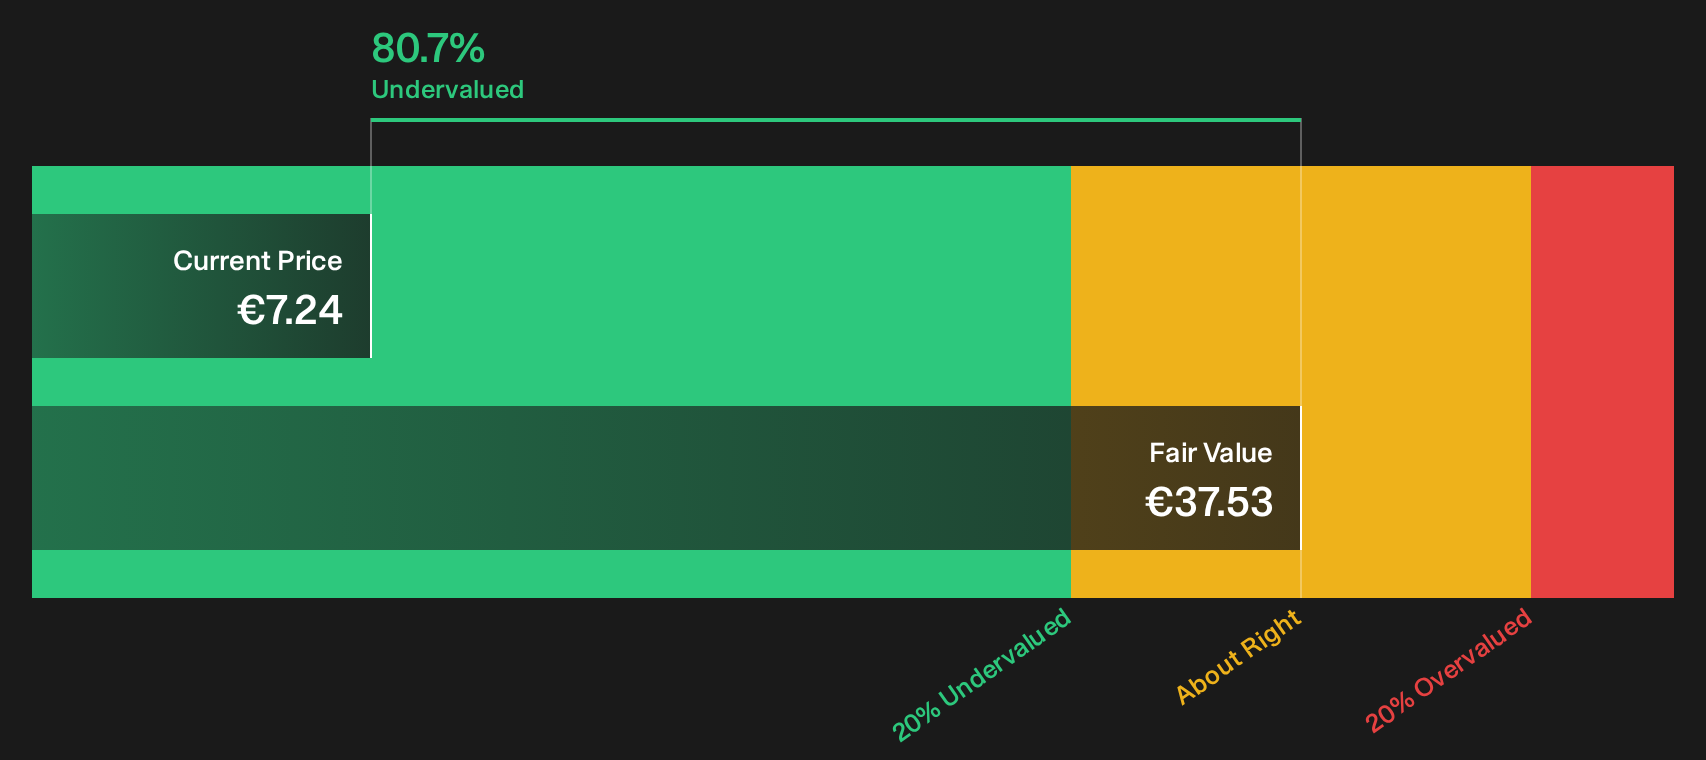
This discount is visible in more than one lens, since the stock is also flagged as trading 80.7% below one internal fair value estimate and is described as good value on this same 0.1x P/S benchmark against direct peers on 0.2x. That suggests the market is attaching a lower value to each euro of Metro’s wholesale revenue compared to similar retailers, even though the core activity is the same type of food-focused trade.
The gap versus the broader European consumer retailing sector is even wider, with the industry average at 0.4x P/S, which is four times Metro’s level. This is a strong relative discount that indicates subdued expectations reflected in the current €7.24 share price when set beside both immediate peers and the sector as a whole.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 0.1x (UNDERVALUED)
Still, Metro’s recent net income loss of €264.0m and its wide spread of international operations leave plenty of room for earnings pressure or regional setbacks to challenge this discount story.
Find out about the key risks to this Metro narrative.
Another View On Metro’s Value
Price to sales paints Metro as cheap, yet the SWS DCF model points to something even starker. With our future cash flow value estimate at €37.53 per share versus the current €7.24 price, the stock screens as heavily undervalued. Is this a margin of safety or a sign that cash flow assumptions are too optimistic?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Metro for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does this setup feel too cautious or not cautious enough? Act quickly, examine the numbers yourself, and weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Metro?
Once you have a view on Metro, widen the lens and use fresh filters to hunt for other potential opportunities before the market prices them differently.
- Target potential income anchors by scanning for companies with steady payouts using the 225 dividend fortresses.
- Hunt for quality at a discount by reviewing the 613 high quality undiscovered gems before others start paying attention.
- Prioritise resilience by focusing on businesses with cleaner finances through the list of solid balance sheet and fundamentals (205 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com