


EN
Independent Bank (INDB) Earnings Strength Puts Its Valuation Question Back In Focus
Independent Bank (INDB) stock is in focus after the company reported third quarter results featuring higher net interest income, stronger net income and lower net charge offs compared with the same period last year.
Independent Bank shares trade at US$83.72 after a 4.8% 7 day share price return and a 3.1% gain over the past month, while a 14.4% year to date share price return and a 24.9% 1 year total shareholder return suggest that momentum has been building around the recent earnings jump, lower net charge offs and the completed buyback program.
Spot fresh momentum stories around Independent Bank by scanning a curated set of 30 resilient stocks with low risk scores that pair earnings power with balance sheets built to handle tougher credit cycles.Independent Bank’s recent climb arrives alongside stronger earnings, lower net charge offs and a finished buyback, which raises a simple tension: Are you paying for a better business or for a mood shift around the stock as valuation comes into focus next?
Most Popular Narrative: 10.4% Undervalued
Independent Bank is priced at $83.72 against a widely followed narrative fair value of $93.43, so the current story leans toward a discount that rests on how its loan mix, fee streams and capital returns evolve from here.
Rebalancing the loan book away from transactional commercial real estate toward relationship-based C&I and selected commercial real estate, including the 10% annualized C&I expansion in Q2 2026 alongside a reduction in investment CRE and construction, points to a mix shift that could support more stable net interest income and credit costs over time.
See why 5 investors see Independent Bank as 10% undervalued.
Result: Fair Value of $93.43 (UNDERVALUED)
Still, the Independent Bank story can change quickly if criticized office loans lead to higher credit costs or if core system conversion expenses remain elevated longer than planned.
Find out about the key risks to this Independent Bank narrative.
Another View on Independent Bank’s Valuation
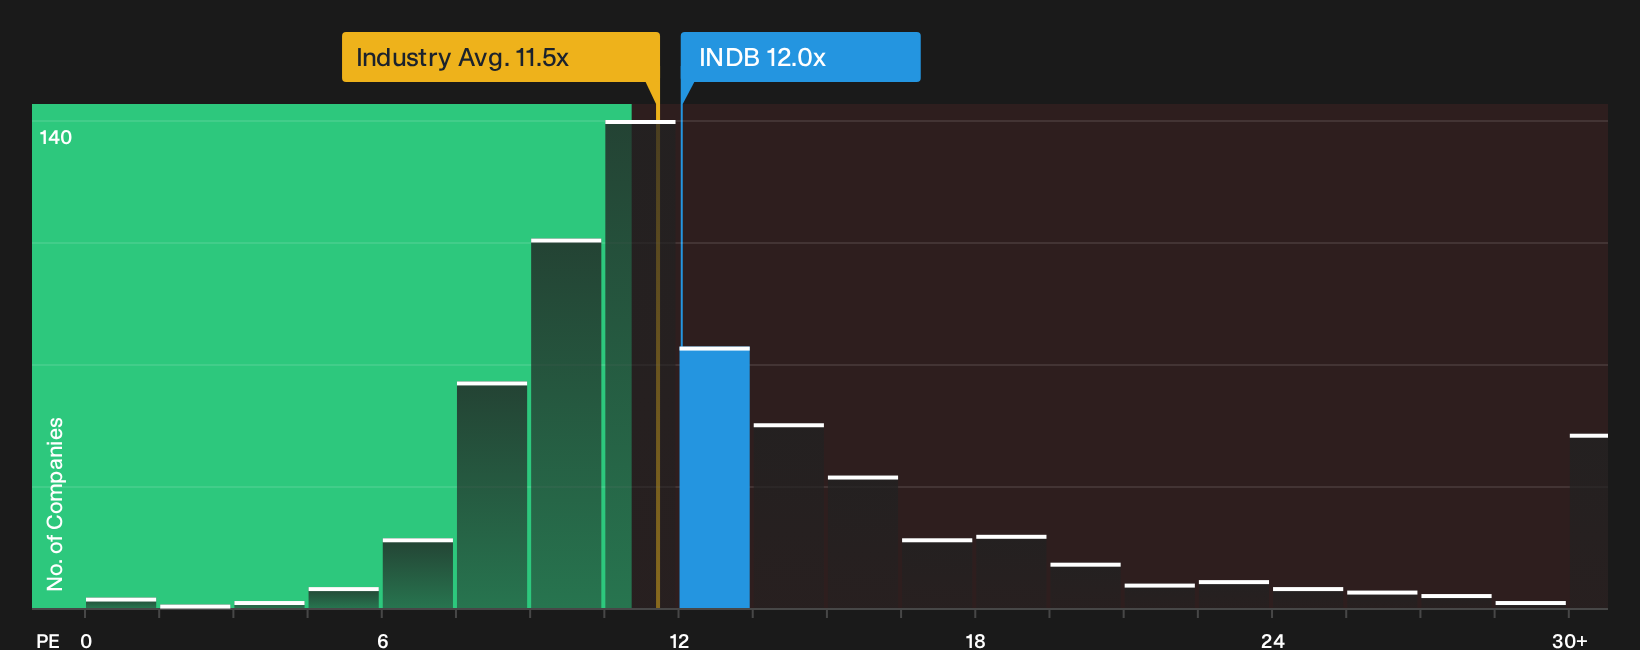
The first story around Independent Bank leans on fair value and future cash flows, yet the standard P/E check tells a cooler story. The stock trades at about 12x earnings, slightly above the US Banks sector at 11.5x and roughly in line with a 12x fair ratio, so the upside case looks tighter and more about execution than a simple bargain.
If you want to see how that earnings based view stacks up against a fuller regression driven fair ratio, and what that might mean for future repricing risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Independent Bank can be useful if you move quickly and stress test the story against your own expectations and risk tolerance. To weigh both the concerns and potential upsides side by side, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Independent Bank?
If Independent Bank has sharpened your focus, do not stop here. Fresh ideas elsewhere could help balance your portfolio and highlight risks you might otherwise miss.
- Target stronger risk control by scanning a 30 resilient stocks with low risk scores that prioritise resilient earnings profiles and balance sheets built to handle rougher conditions.
- Hunt for potential mispricing with a 21 high quality undiscovered gems that surfaces under-followed businesses showing solid fundamentals and cleaner financial stories.
- Build a more durable income stream through a 5 dividend fortresses that focuses on higher yielding companies with the financial capacity to keep paying shareholders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com