


EN
Hecla Mining (HL) Could Be 37% Below Fair Value Following Record Silver Production
Record silver production, lower all in sustaining costs, and a stronger cash position at Hecla Mining (HL) have pushed investors to reassess what they are willing to pay relative to current cash flow estimates.
Despite the operational progress, Hecla Mining’s share price has pulled back, with the stock down 23.86% over the past month and 26.60% year to date. At the same time, the 1 year total shareholder return of 7.04% and a very large 3 year total shareholder return of 238.37% show that longer term momentum has been strong, but is now fading in the short term as investors reassess growth potential and risk around cash flow expectations.
Spot opportunities across precious metals by benchmarking Hecla Mining against a curated 10 top silver producer stocks that are also contending with production swings, cost control, and shifting sentiment.Hecla Mining now trades well below analyst targets and an estimated intrinsic value, even after strong operational headlines. Is this a market overreaction to cash flow risk, or a rational discount on a premium story?
Most Popular Narrative: 37% Undervalued
Hecla Mining's most followed narrative pegs fair value at $22.08 using an 8.71% discount rate, compared with the recent $13.85 close. This puts the current pullback squarely against a valuation framework built around softer revenue, lower margins, and a richer future earnings multiple.
Hecla is poised to benefit from accelerating demand for silver driven by ongoing global electrification and renewable energy growth, as silver is critical for EVs and solar panels. This positions the company for potential top-line revenue expansion and greater leverage to rising silver prices.
Elevated inflation and persistent macroeconomic uncertainty are fostering stronger investor demand for precious metals as safe havens, which can underpin higher realized silver prices and margin expansion for Hecla's silver-focused portfolio.
See why 65 investors see Hecla Mining as 37% undervalued.
Result: Fair Value of $22.08 (UNDERVALUED)
Still, the Hecla Mining narrative hinges on tight execution, since rising capital needs at Keno Hill and potential shareholder dilution from deleveraging could quickly erode that perceived valuation gap.
Find out about the key risks to this Hecla Mining narrative.
Another View On Hecla Mining’s Valuation
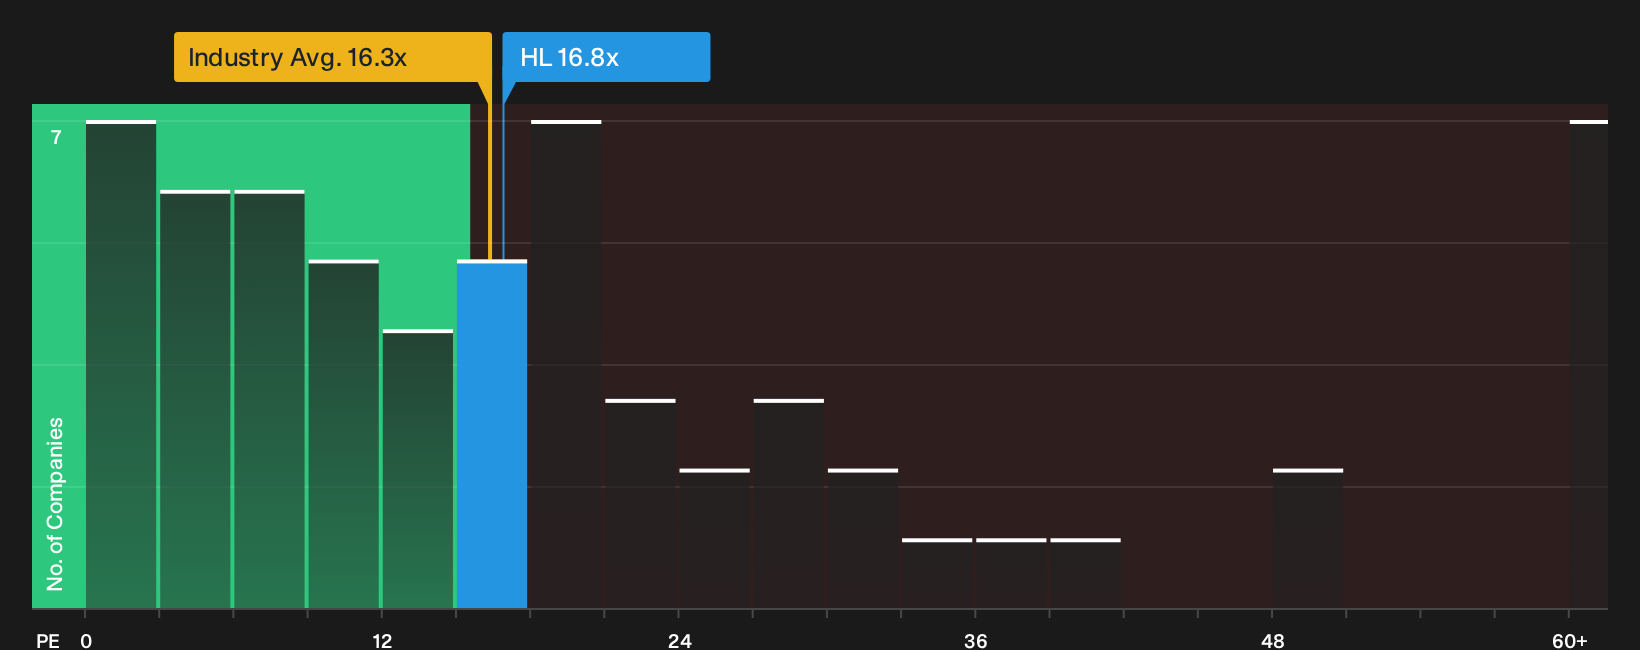
Here is the twist. While the most popular narrative sees Hecla Mining as materially undervalued on future cash flows, the simple earnings multiple tells a tighter story. HL trades on a P/E of 16.8x, slightly richer than the US Metals and Mining sector at 16.3x and above the 15.3x peer average. That premium suggests the market already bakes in some quality and growth, which reduces the margin of safety if the bullish cash flow path does not play out as hoped.
If you want to see how a price tag built on future cash flows compares with this earnings snapshot, take a look at the SWS DCF workup for Hecla Mining, then decide which lens you trust more for sizing position risk and upside. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Hecla Mining’s valuation and risk profile make this a moment to move fast, study the data in detail, and decide whether the current pullback fits your own thesis. To weigh both sides of the story, start with our breakdown of 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Hecla Mining?
If Hecla Mining has sharpened your focus on valuation and risk, use this pullback as a prompt to refresh your broader watchlist with fresh possibilities.
- Target long term compounding potential by reviewing a 29 high quality undervalued stocks that combines quality fundamentals with attractive pricing.
- Strengthen portfolio resilience by scanning a list of solid balance sheet and fundamentals (24 results) that can help cushion tougher market phases.
- Spot earlier stage opportunities by checking a 21 high quality undiscovered gems before attention and pricing move away from you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com