


EN
Why PACS Group (PACS) Could Be 20% Below Fair Value Following Its Guidance Upgrade
Guidance revision puts PACS Group in focus
PACS Group (PACS) raised its 2026 adjusted EBITDA outlook to $640 million to $660 million and revenue guidance to $5.75 billion to $5.85 billion after integrating 20 Texas facilities from the Eduro Healthcare acquisition.
Recent trading has been strong for PACS Group, with a 30-day share price return of 15.35% and a year-to-date share price gain of 20.58%. The 1-year total shareholder return of roughly 3x hints that investors are reassessing both growth potential and risks around the upgraded guidance and acquisition progress.
Scan how PACS Group compares with other healthcare operators showing strong balance sheets and cash flows in our hand picked list of solid balance sheet and fundamentals (24 results) for this part of the market.
PACS Group has just rallied hard while sitting below the average analyst target and above some intrinsic value estimates. The gap between those reference points is where the valuation work really starts.
Most Popular Narrative: 20% Undervalued
The most followed narrative for PACS Group places fair value at $59.75, above the last close of $47.64. This frames the recent rally as only a partial catch up to those expectations.
Rising demand for post-acute and long-term care from an aging U.S. population, combined with PACS Group's expanding footprint of over 35,000 beds, creates room for continued top line growth as occupancy and patient volumes increase, supporting higher revenue and earnings.
Systematic improvement of newly acquired and turnaround facilities from low single digit margins toward the high single digit and low double digit margin profile of mature sites should unlock embedded profitability, lifting consolidated net margins and EBITDA over time.
See why 14 investors see PACS Group as 20% undervalued.
Result: Fair Value of $59.75 (UNDERVALUED)
Still, PACS Group faces real trip wires, including heavier reliance on state Medicaid frameworks and the execution risk involved in integrating more than 100 recently acquired facilities.
Find out about the key risks to this PACS Group narrative.
Another View: PACS Group Through The Earnings Multiple
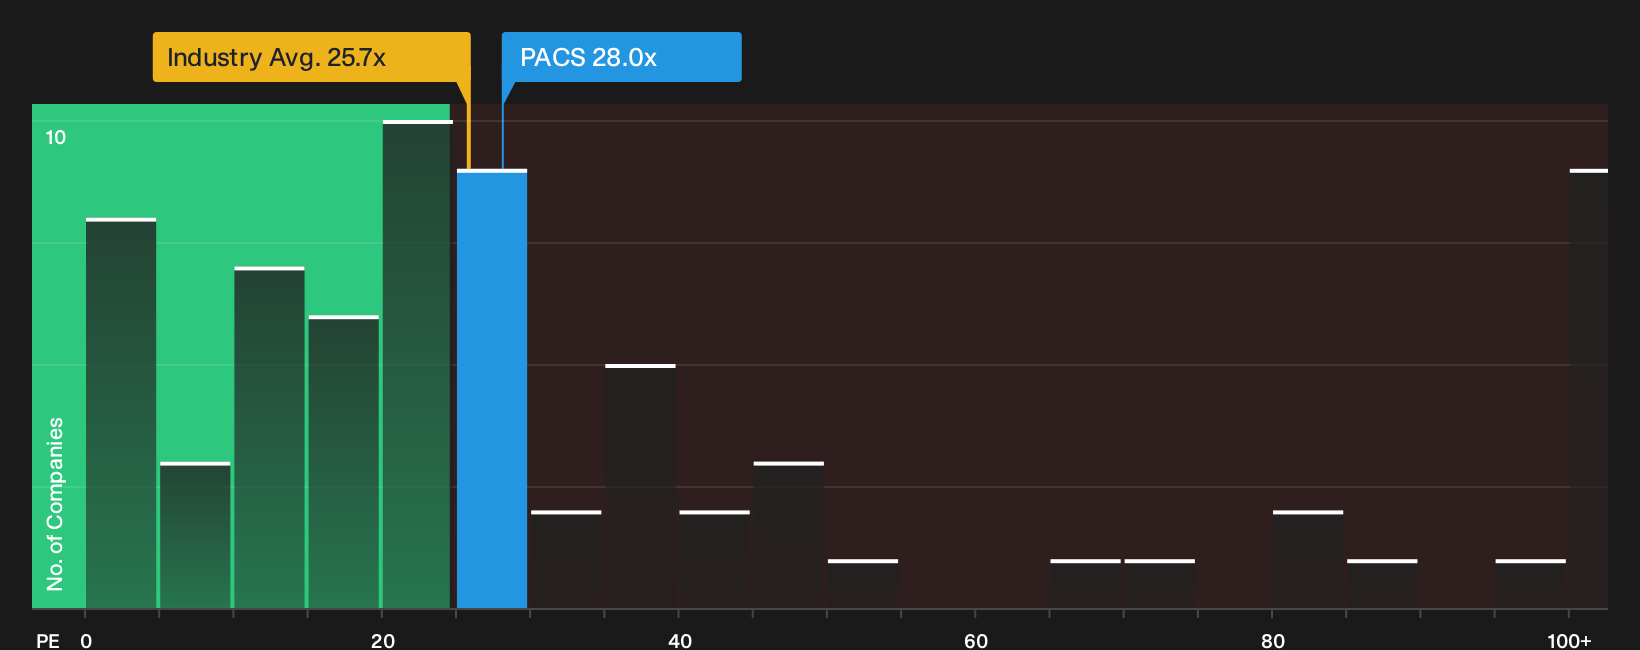
The first narrative leans on analyst fair value of $59.75, yet the current P/E of 28x puts PACS Group on a richer tag than both direct peers at 20x and the wider US Healthcare sector at 25.7x. The fair ratio sits even higher at 40.8x, raising the question of which reference point investors might prioritize when risk and potential upside appear to pull in different directions.
For a clearer sense of what those ratios imply in practice, and how they might adjust if expectations change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early conviction are forming around PACS Group. If this upgrade story feels time sensitive, check the full picture of risks and bright spots through 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond PACS Group?
If PACS Group has your attention, you may want to broaden your watchlist with a few focused stock ideas sourced from the Simply Wall St Screener.
- Target stability first by checking companies that score well on resilience and capital strength in our 30 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price by scanning businesses with strong fundamentals filtered through our 29 high quality undervalued stocks.
- Build a watchlist of potential future standouts by reviewing financially robust smaller players via our 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com