


EN
What AMAG Austria Metall (WBAG:AMAG)'s Award Winning Alloy Means For Shareholders
- AMAG Austria Metall recently received the ALUMINIUM Innovation Award 2026 for its AMAG CrossAlloy.57 alloy, which combines high strength, formability, weldability and corrosion resistance and is designed for production using scrap based inputs that support circular economy principles.
- The award, together with an €86.6 million European Investment Bank loan for greener, recycling focused alloy production and equipment upgrades, points to AMAG Austria Metall placing greater emphasis on higher specification, potentially higher margin alloys for aerospace, defense and robotics customers while seeking more efficient use of raw materials.
- We will now look at how AMAG Austria Metall's award winning CrossAlloy.57 and recycling investments could influence the existing investment narrative.
Scan beyond AMAG Austria Metall and find peers that are pushing recycling focused metals technology with our curated list of 613 high quality undiscovered gems.
AMAG Austria Metall Investment Narrative Recap
To own AMAG Austria Metall, you need to believe that its push into higher margin rolled and specialty alloys can offset working capital swings, relatively high P/E and modest forecast growth. The ALUMINIUM Innovation Award for CrossAlloy.57 fits that view by reinforcing the move toward more complex, specification heavy products tied to aerospace, defense and robotics.
The near term swing factor still sits in cash conversion and leverage, not awards. First half 2026 showed negative operating and free cash flow alongside higher net debt to EBITDA of 2.7x. If working capital and metal price effects stay volatile, that remains the key risk even as premium alloy volumes gain share.
The €86.6 million European Investment Bank loan is the announcement that matters most next to the CrossAlloy.57 recognition. It links directly to AMAG Austria Metall’s plan to expand recycling focused alloy output and upgrade equipment, which speaks to the same premium, low carbon aluminium narrative that underpins the recent award.
For you as a shareholder, that funding can support higher specification recycling capacity as a concrete catalyst, while also lifting balance sheet sensitivity to weak cash generation. Debt is currently not well covered by operating cash flow, and dividend cover by free cash flow is thin, so execution on these funded projects will likely remain under close scrutiny.
AMAG Austria Metall's current analyst narrative points to revenues of €1.7 billion and earnings of €72.6 million by 2029. That profile assumes revenue growth of 2.8% per year and an earnings increase of €21.3 million, from €51.3 million today to the 2029 consensus figure.
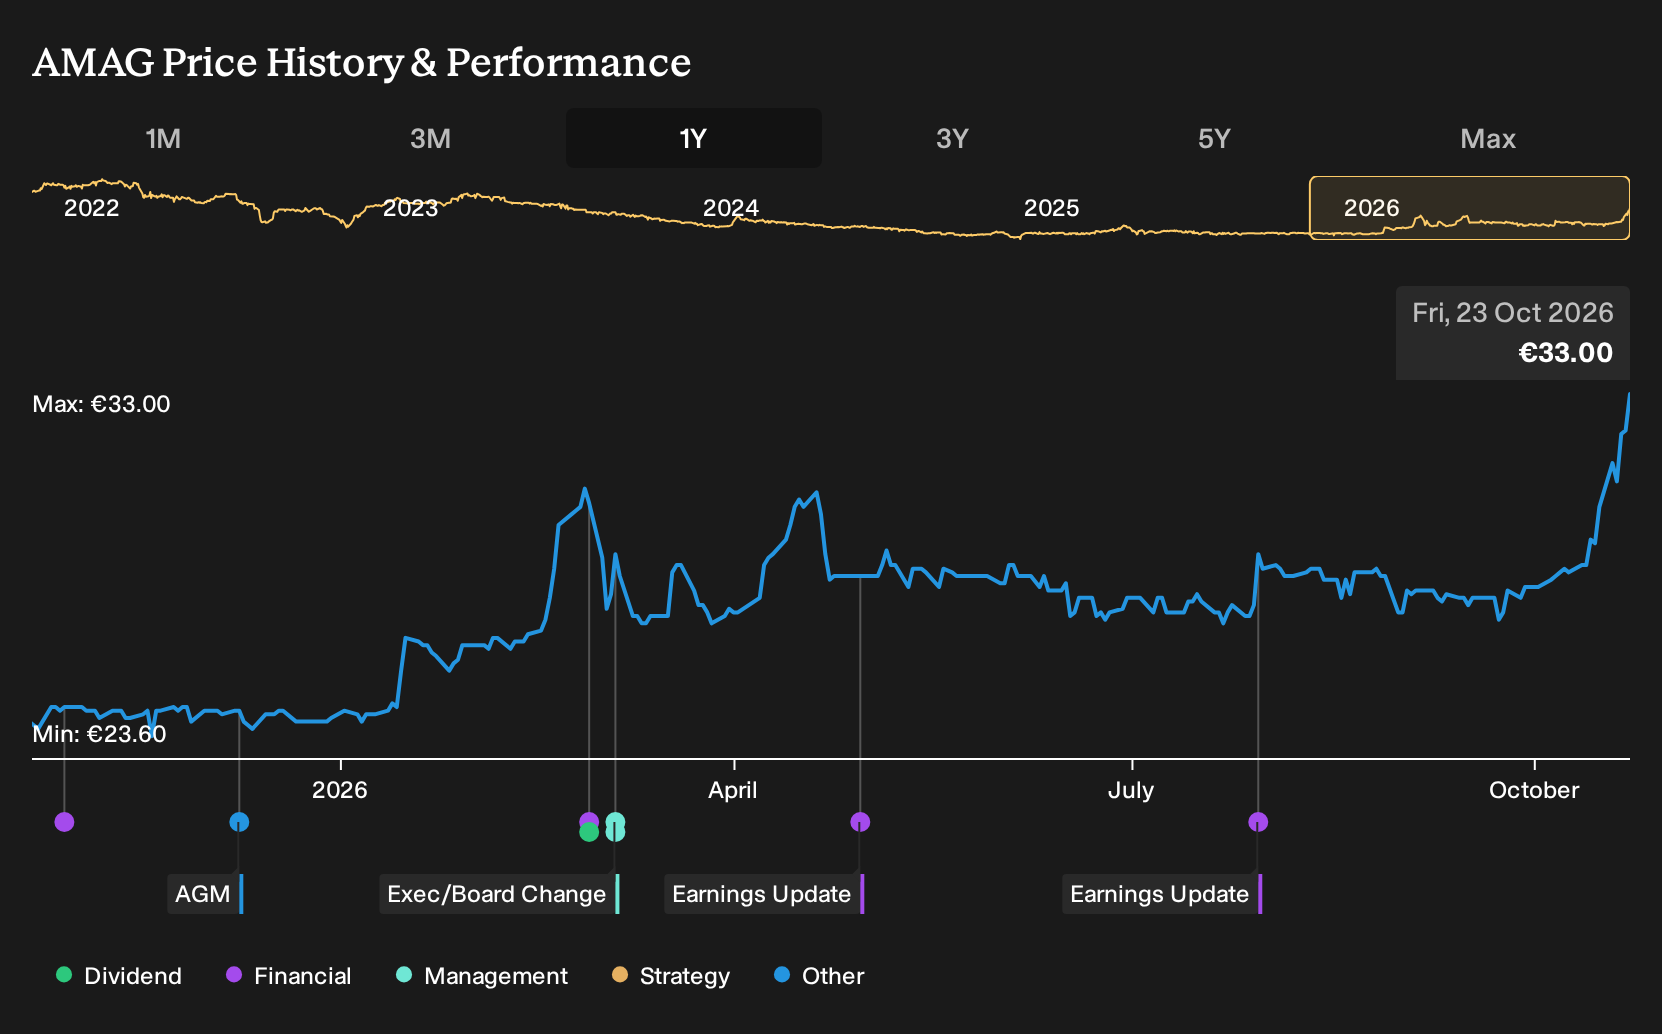
Uncover why AMAG Austria Metall's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view focuses less on AMAG Austria Metall’s award winning alloy and more on recycling input risk. Some bearish analysts worry that rising competition for scrap could squeeze Casting and Rolling margins, which ties into the CrossAlloy.57 story. Before this news, they were only pencilling in €1.6b revenue and €70.4 million earnings by 2029. That is a more cautious script than the consensus. This award plus the EIB funding may eventually push some of those expectations higher or lower. Use that gap in opinion as a prompt to test your own thesis against several different scenarios.
Explore another AMAG Austria Metall fair value estimate, including one that suggests as much as 6% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AMAG Austria Metall research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AMAG Austria Metall. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMAG Austria Metall's overall financial health at a glance.
Looking for more AMAG Austria Metall sized ideas?
You do not need to stop your work at AMAG Austria Metall. Use the Simply Wall St Screener to line up a wider watchlist and compare how different businesses stack up on quality, value and resilience.
- If you want potential mispricing on your radar, start with companies that currently screen as 193 high quality undervalued stocks based on fundamentals.
- If capital preservation sits high on your priority list, filter for 221 resilient stocks with low risk scores that score well on financial strength and volatility.
- If balance sheet quality matters most to you, scan our list of solid balance sheet and fundamentals (205 results) and see which businesses meet your standards.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com