


EN
Is Grindr (GRND) Cheap Following Its Freddie Acquisition?
Grindr (GRND) is in focus after announcing plans to acquire Freddie, a telehealth platform centered on PrEP and HIV prevention. The move is reshaping how investors think about the app’s future earnings power.
Recent trading tells a mixed story. Grindr’s share price is down 13.25% over the past month and 11.63% over 90 days, yet year to date it is still up 2.78%. That sits against a 1-year total shareholder return that has declined 9.16%, but a very large 3-year total shareholder return of about 2.3x suggests that investors who bought earlier are still sitting on sizeable gains. The Freddie deal now tests whether that earlier optimism about growth potential still holds.
Scan how Grindr’s healthcare pivot compares with other high-growth digital platforms by lining it up against our hand picked 21 high quality undiscovered gems in similar monetization sweet spots.
Grindr’s Freddie deal now turns into a live test. Are you looking at a healthier underlying business being re-rated, or mostly a mood swing in how the market feels about the story today?
Most Popular Narrative: 99% Undervalued
Grindr’s most followed narrative pins fair value at $975 per share, far above the last close of $13.68. This frames the Freddie acquisition as one small step inside a much larger thesis about what this platform could become over time.
At that point, today's ~$2.7 billion market cap begins looking less like a technology company and more like an early-stage infrastructure investment in the global gay economy.
The market currently appears to be asking:
“How much is Grindr worth?”
The correct question is:
“How much is gayness worth?”
And nobody has successfully calculated that number.
Because gayness is infinite.
See why 2 investors see Grindr as 99% undervalued.
According to Bradley_Lordo, that fair value implies Grindr trades at roughly a 99% discount, using a discount rate of about 9.09% and leaning heavily on high revenue growth, a profit margin near 17%, and future earnings multiples that assume the platform matures into a broader “Gaynet” ecosystem. The narrative treats the 23.3% expected annual earnings growth and 15.3% forecast revenue growth as fuel for compounding cash flows inside a niche that the author views as structurally self renewing. This is a very different lens to short term price moves around the Freddie news.
That gap between the $975 narrative fair value and the current $2.38b market cap also sits beside Simply Wall St’s own DCF output, which estimates future cash flow value at $39.79 per share and frames the stock as trading about 65.6% below that model. Both views lean on discounted future cash generation rather than today’s P/E of 27.8x, although the narrative clearly stretches far more optimistic assumptions about how much monetisation and ecosystem breadth Grindr might eventually achieve.
Result: Fair Value of $975 (UNDERVALUED)
Still, the Grindr narrative leans on aggressive long term assumptions and carries balance sheet questions, so weaker user monetization or funding pressure could quickly puncture that optimism.
Find out about the key risks to this Grindr narrative.
Another View: What Grindr’s P/E Is Telling You
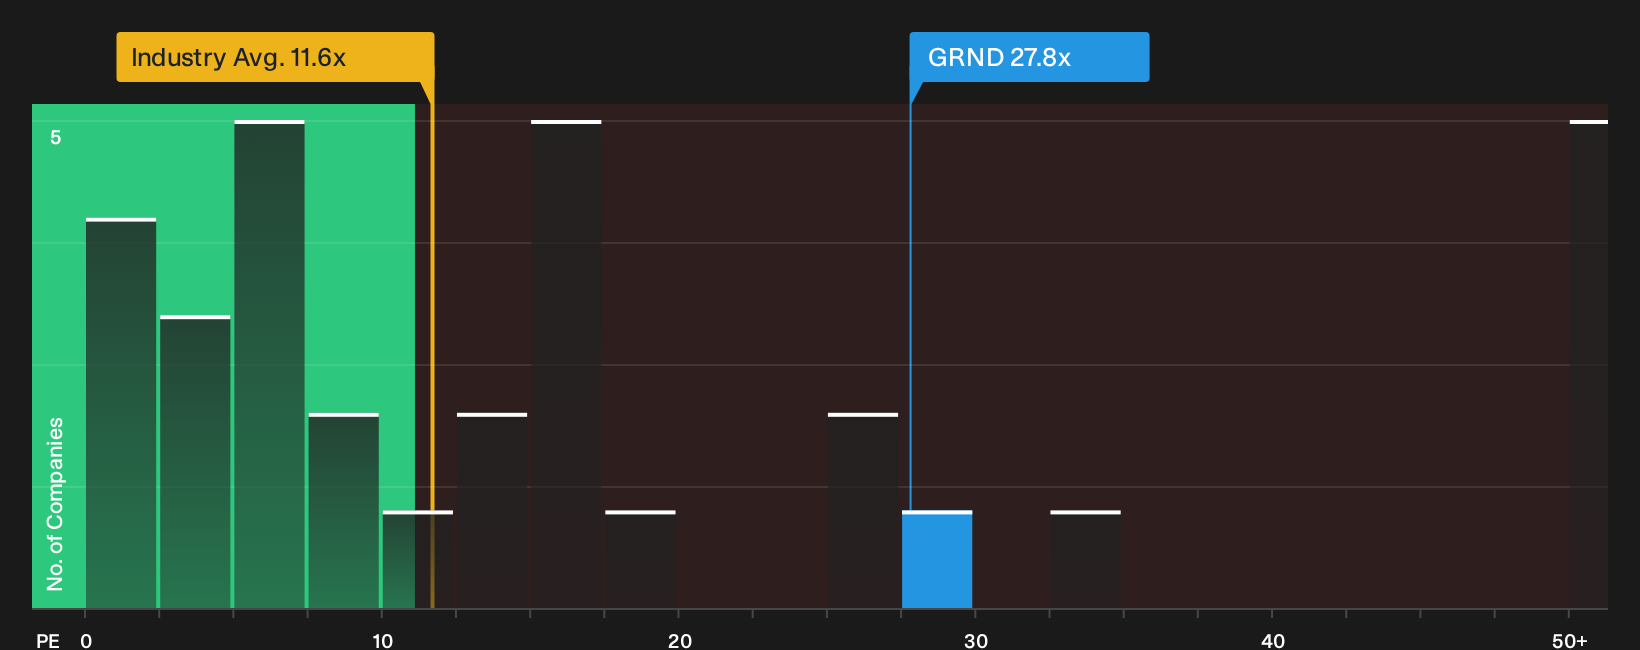
Grindr looks cheap on the narrative and our DCF work, yet the market is paying a rich 27.8x P/E today. The fair ratio sits at 21.1x, while peers average 12x and the wider Interactive Media and Services group is around 11.6x. That higher multiple can signal either confidence in future earnings or extra valuation risk if expectations slip.
To see how those earnings expectations stack up against what comparable companies trade on, and where the P/E might drift toward over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the Grindr story so far seems divided between significant potential and notable concerns, consider acting promptly and evaluating both perspectives for yourself using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Grindr?
Grindr might be front of mind today, but building real resilience comes from lining up a few high quality candidates, not just one headline stock.
- Target long term compounding potential by scanning a curated 29 high quality undervalued stocks that combine quality fundamentals with discounted share prices.
- Strengthen portfolio durability by checking a list of solid balance sheet and fundamentals (24 results) that can better handle funding shocks and tighter credit conditions.
- Reduce gut wrenching volatility by reviewing 30 resilient stocks with low risk scores that score well on stability and business quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com