


EN
How Anthropic AI Deal Will Impact Akamai Stock Investors
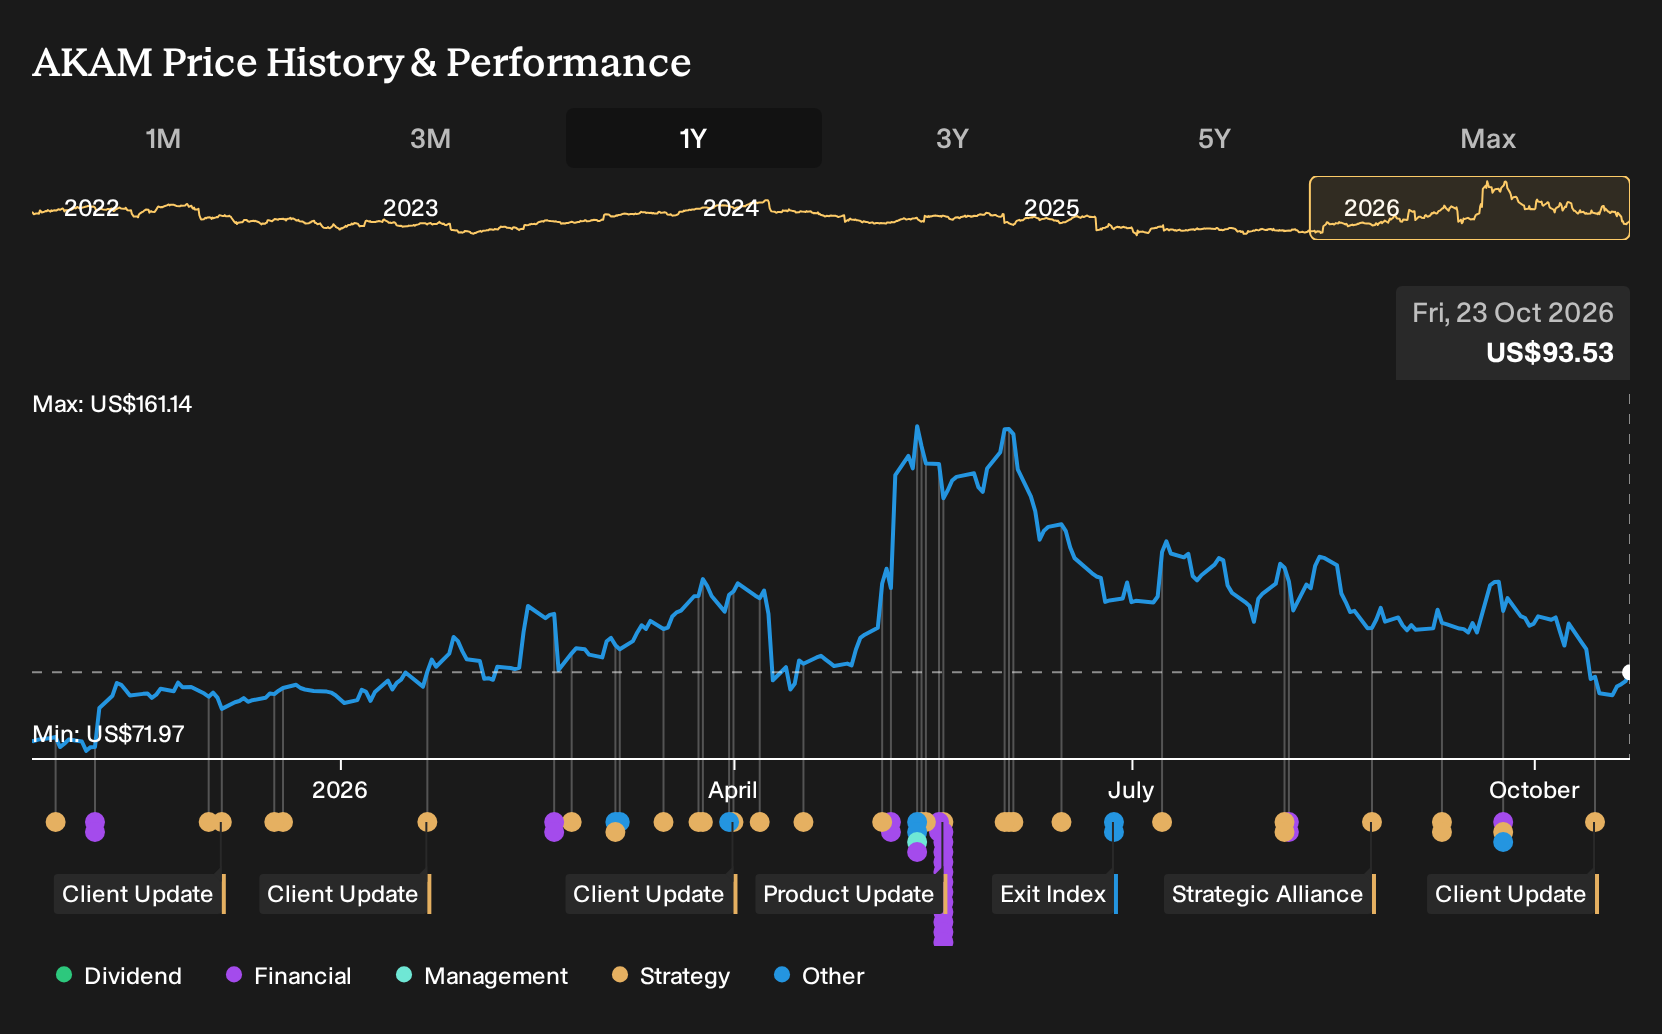
- Akamai Technologies disclosed a multiyear AI infrastructure agreement with Anthropic valued at US$11.6b, alongside broader cloud computing adoption across software, media, logistics, and healthcare clients seeking high performance CPU, GPU, and storage capacity.
- The Anthropic deal and recent customer wins indicate that Akamai Cloud and its NVIDIA RTX PRO 6000 Blackwell GPU offerings are becoming important infrastructure for AI training, inference, and mission critical workloads across several industries and regions.
- We will now look at how Akamai Technologies' Anthropic AI deal could influence the existing investment narrative around its cloud buildout.
Akamai Technologies Investment Narrative Recap
To own Akamai Technologies, you need to buy into a pivot away from a shrinking legacy delivery business toward higher value security and cloud infrastructure services. The recent Anthropic deal and fresh AI cloud wins support that shift. The key near term catalyst is clear: management has to show that early AI deployments actually translate into recurring usage on the new cloud platform.
The biggest near term risk is execution on a very heavy buildout. Akamai plans roughly US$5.5b in Anthropic related CapEx, with 2026 CapEx at about 40% of revenue. If GPU and CPU sites ramp slower than expected or miss the targeted cash gross margin range, operating margins and cash generation could come under pressure.
The recent wave of Akamai Cloud Computing customer adoption is the clearest operational proof point tied to these catalysts. Software and SaaS clients are moving model training, inference, and core microservices to Akamai infrastructure across APJ, EMEA, and North America. That broadening usage matters if you care about whether the Anthropic buildout can support more than one flagship tenant.
The same announcement also highlights the concentration risk. A single North American technology innovator, a logistics provider displacing several legacy clouds, a developer platform migrating 1,500 microservices, and media or healthcare clients all increase reliance on a smaller group of large AI and data heavy projects. If workload scaling, migrations, or disaster recovery deployments slow, expected CIS recurring revenue and margin progress could be delayed.
Akamai Technologies' current analyst narrative points to revenues of US$7.2b and earnings of US$738.3m by 2029, built on assumed 18.8% yearly revenue growth and an earnings increase of about US$327m from US$411.0m today.
Uncover why Akamai Technologies' fair value indicates a 70% potential upside to its current price. This upside could narrow faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Akamai Technologies’ potential margin expansion rather than just revenue. Before this news, the bullish camp was already pencilling in about US$7.9b of sales and US$1.1b of earnings by 2029. You can now ask whether this fresh AI demand justifies those richer forecasts or pushes them higher.
Explore 3 other Akamai Technologies fair value estimates, including one that suggests as much as 70% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Akamai Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Akamai Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Akamai Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Akamai Technologies?
If the Akamai Technologies story has sharpened your view on AI infrastructure, it can help to widen the lens and scan for other businesses that fit your preferred mix of quality, valuation, income, or risk profile. The Simply Wall St Screener lets you filter the market using fundamentals rather than headlines, so you can focus on companies that align with your own thesis and time horizon.
- Prefer resilient balance sheets over big promises? Start with a list of solid balance sheet and fundamentals (24 results) to see which businesses pair strong finances with consistent fundamentals.
- Hunting for mispriced quality? Use a 21 high quality undiscovered gems to surface lesser known companies that still show robust underlying metrics.
- Want fewer surprises? Begin with a 30 resilient stocks with low risk scores that screens for businesses with lower risk scores and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com