


EN
What Regeneron Pharmaceuticals Buyers Were Betting On
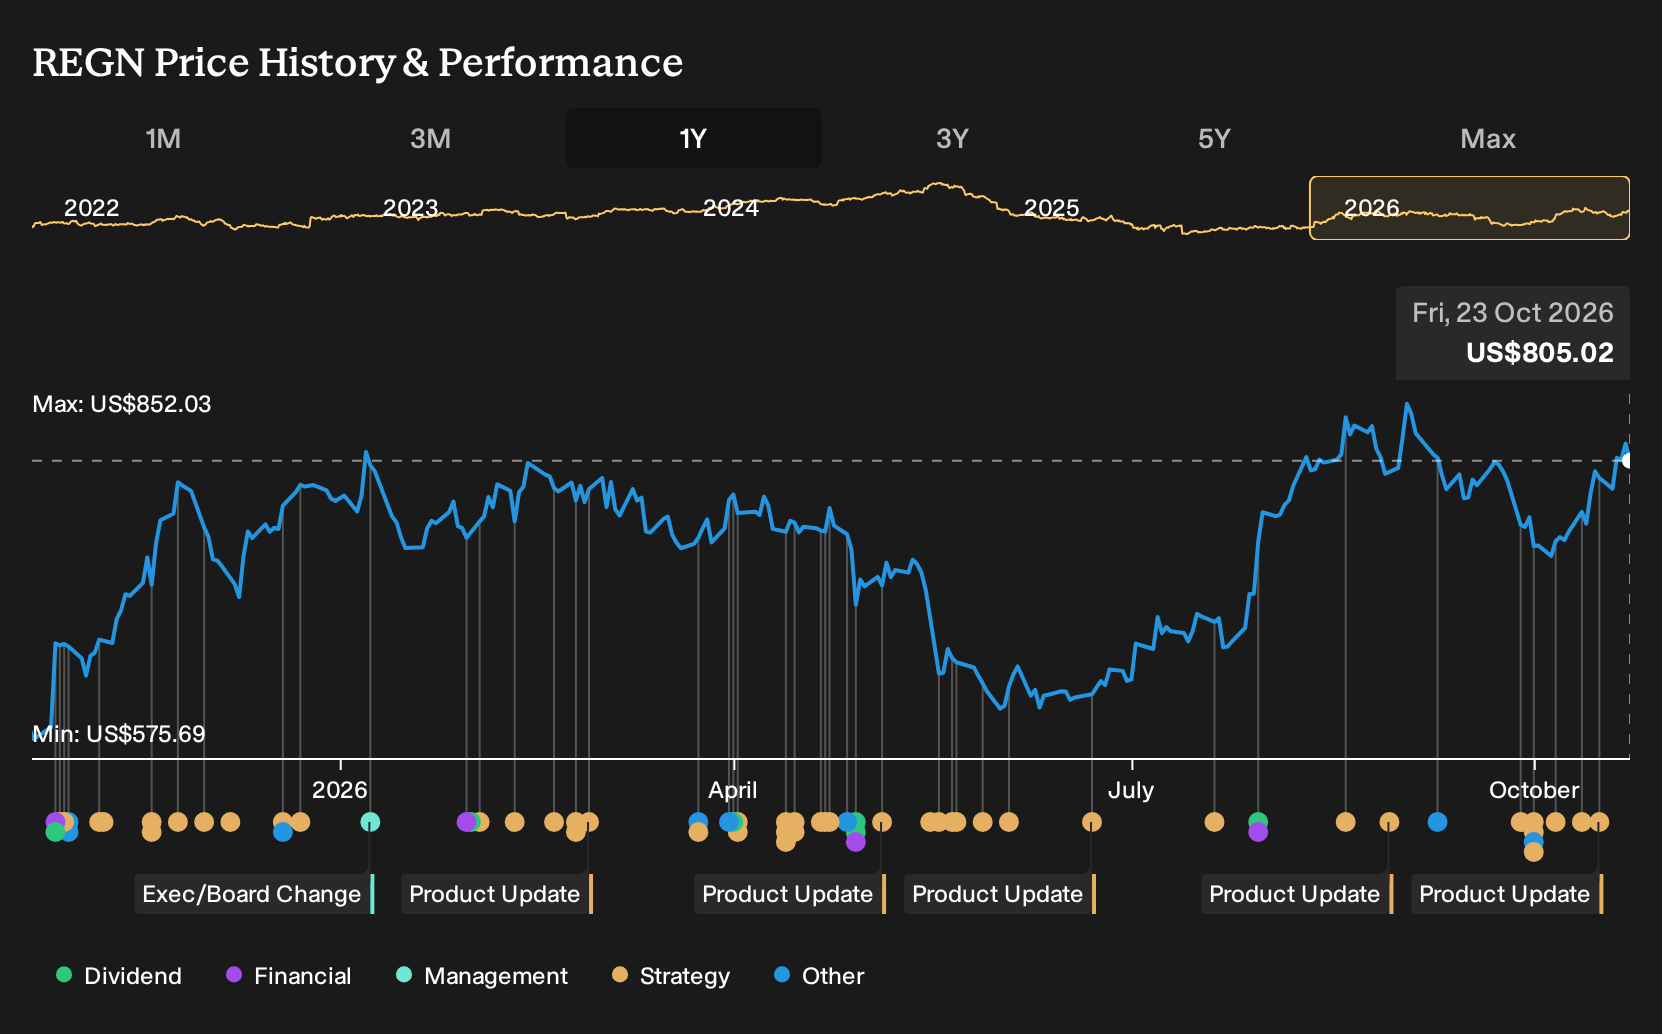
If you had bought Regeneron Pharmaceuticals on 23 October 2025 and simply sat tight, the result would look very different after a year of pipeline headlines, pricing deals and a failed melanoma trial hitting the courts. Holding Regeneron Pharmaceuticals over the past year would have returned 40.0%, including dividends. If that decision were on the table again today, how much weight would you give to early worries about EYLEA reliance and healthcare reform versus the breadth of new programs now coming through?
Regeneron Pharmaceuticals is not the only name tied to this theme. Zero in on 34 healthcare AI stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On Regeneron Pharmaceuticals
The shares cost US$576 at the start of the period, so any view on Regeneron Pharmaceuticals in late 2025 hinged on which story you believed about its next few years.
The bullish narrative pointed to a Fair Value of US$722, a notional target price based on assumptions like 5.4% annual revenue growth and a 30.1% profit margin supported by a broad pipeline and global access plans.
The bearish case anchored on a Fair Value of US$540 and focused on US healthcare reforms, pricing pressure, and the risk that biosimilars and alternative therapies could steadily erode EYLEA driven earnings and margins.
What The Facts Did To The Regeneron Pharmaceuticals Argument
The most powerful update came from cemdisiran, where positive Phase 3 data in gMG and multiple regulatory filings supported the idea that Regeneron Pharmaceuticals could broaden beyond EYLEA. At the same time, Q2 2026 figures showed revenue at US$4,290.7m but net income at US$1,296.9m, with net margin falling from 37.9% to 30.2%. Overall, the evidence cut both ways.
The key lesson is simple. When a story hinges on pipeline breadth protecting earnings, always match each new program to hard figures such as later net margin and absolute profit, not just headline trial wins.
What Regeneron Pharmaceuticals' Price Now Asks You To Believe
Regeneron Pharmaceuticals now trades at US$805, with this Narrative’s Fair Value sitting below that level based on its own assumptions rather than any hard rule.
The Narrative leans on concentrated product risk, legal cases and higher research spending, and it argues that newer franchises must carry more of the earnings load. Anyone paying today’s price is effectively assuming the pipeline offsets these pressures, so how do the highlighted trial and regulatory risks affect that bet?
"The main factor that has to go right is that Regeneron Pharmaceuticals converts its broad pipeline and newer franchises such as EYLEA HD, Libtayo, cemdisiran and Pasatru into durable earnings streams that offset pricing pressure and legal and regulatory risks. Despite management highlighting late stage assets such as cemdisiran in generalized myasthenia gravis and other complement, coagulation and obesity programs as part of a more diversified multi franchise model, any setback in pivotal data or regulatory reviews would leave Regeneron Pharmaceuticals more dependent on existing products at the same time that pricing pressure and competitive products weigh on revenue growth and long term earnings visibility."
The price and this Narrative do not agree. → Uncover what this Narrative says Regeneron Pharmaceuticals is actually worth
Another Way To Play Regeneron?
Looking at Regeneron, you are weighing pipeline depth against product concentration. One step away, there is a different kind of healthcare scale.
Instead of relying on a few therapies, this other group spreads pharmaceutical and device work across many platforms.
It commits significant resources to drug discovery and deal making, feeding a busy queue of late stage programs and approvals.
Complex treatments for cancer, immune disorders and brain conditions, plus advanced surgery and vision tools, target areas where medical need and pricing power can remain connected.
If Regeneron anchors your watchlist, how does that broader multi platform model reshape your sense of risk and opportunity?
That argument has a Narrative and a number behind it. → See the company one Narrative values 21% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com